Big family home after retirement: Should you sell, downsize or simply stay put?
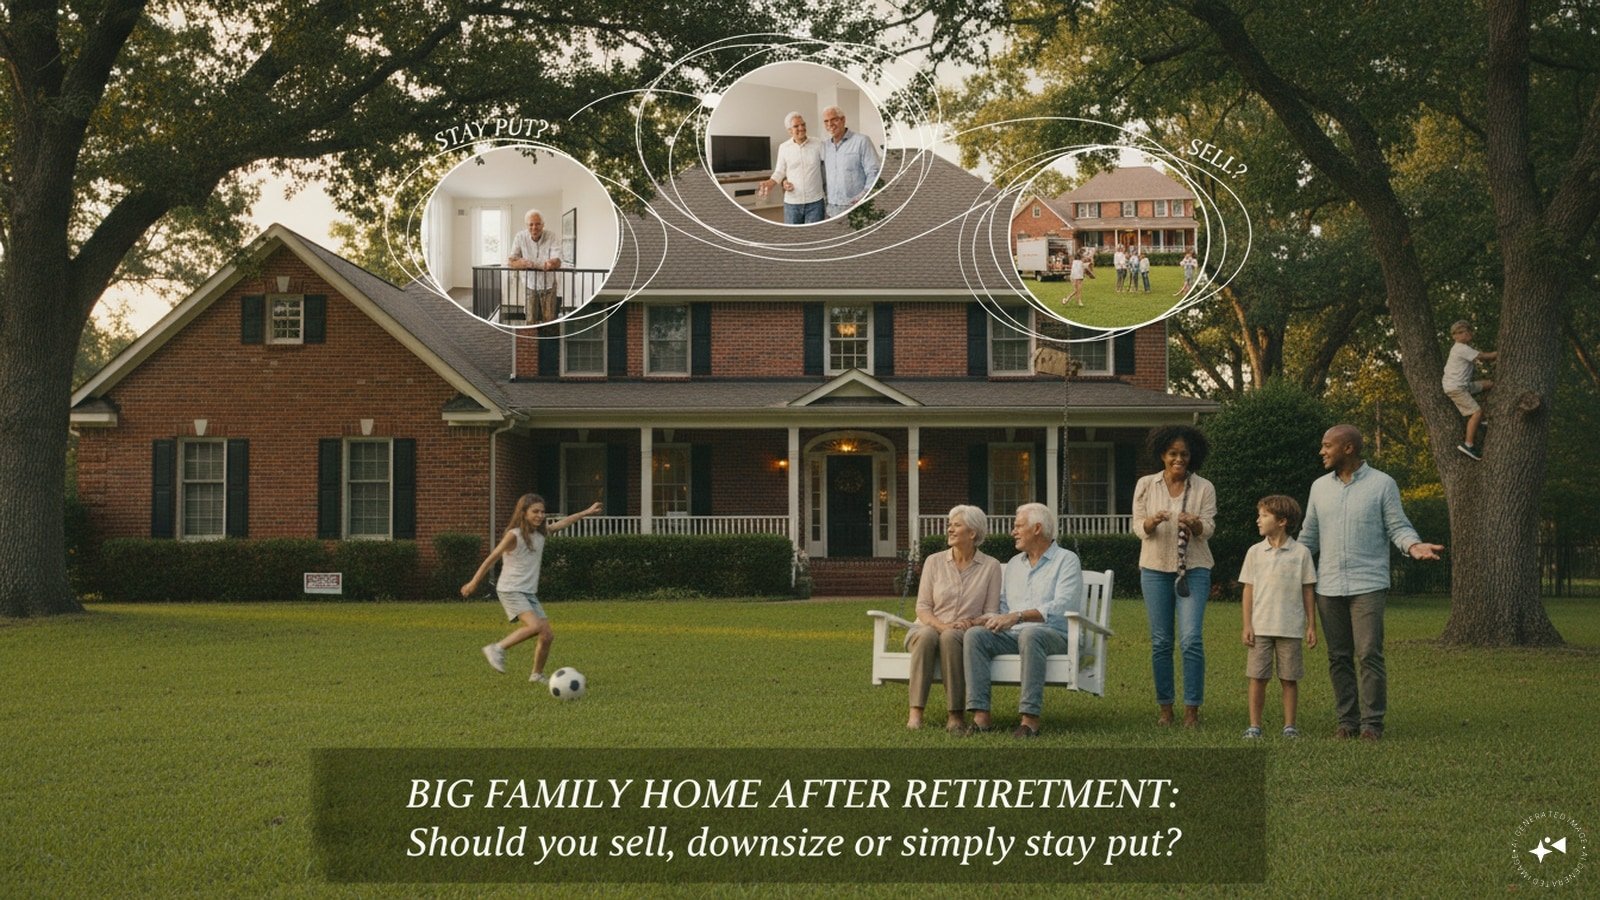
New business data points to the fact that A large family house can feel like a financial safety net after retirement. But when children move out, retirees can find themselves maintaining a property that is far bigger than they need. Selling it and moving to a smaller home can release money, but it additionally means giving up a familiar place that may have been the family home for decades.
The question becomes more pressing when most of the family's wealth is tied up in the house and there is not enough regular income to meet expenses.
Look at what the house costs you every year
The easiest place to start is with the actual cost of keeping the property. A large house can mean elevated maintenance, repairs, property tax, electricity bills, security costs and domestic help expenses.
There is additionally the question of how much of the house is being used. If a retired couple occupies two rooms in a four-bedroom house, paying to maintain the remaining space may not make much financial sense.
But the numbers should not be the only consideration. The location may be convenient, children may visit frequently and the house may carry considerable emotional value. Selling a family home simply because it appears too large can create regret if the replacement property does not work for the family.
Downsizing can put cash back into the retirement plan
Suppose a retired couple sells a house for Rs 2 crore and buys a smaller apartment for Rs 80 lakh. Ignoring taxes and transaction expenses for the illustration, Rs. 1.2 crore would stay from the sale.
That amount could provide an additional financial cushion. It could be kept partly for emergencies and partly invested according to the couple's risk capacity and income needs.
That stated, this calculation works only if the surplus is actually preserved. Buying another expensive property, spending heavily on renovations etc. can quickly reduce the money released by downsizing.
Tax implications additionally need to be checked before the sale.
Think around life at 70, not just life at 60
A house that is comfortable immediately after retirement may not stay convenient ten or fifteen years later.
Stairs can become a problem. Travelling long distances to a hospital may become tiring. Access to grocery stores, public transport and family can matter more than having extra bedrooms.
This is where a smaller apartment in a well-connected area can be useful. Some retirees may additionally consider senior living or renting after selling the family home. These options come with their own costs, including monthly charges, healthcare fees and other services, so they need to be compared carefully.
Do not turn a property decision into a cash-flow problem
Selling the house only makes sense if the money released improves the retirement position. A retiree who already has adequate income and savings may gain little from moving out of a comfortable home.
The opposite can be true when a large property represents most of the family's wealth. Someone may own a Rs. 2 crore house but have limited monthly income and a small emergency fund. In that situation, having substantial wealth on paper does not necessarily mean having enough money available for regular expenses.
Before making the decision, work out the anticipated sale proceeds, taxes and selling costs. Then calculate the price of the replacement home, moving expenses and the amount that would actually stay. Factor in future rent if you decide not to buy another property.
A large family home can be worth keeping if it is affordable, well located and still useful. But if it is consuming money that could otherwise backing retirement, downsizing may be worth considering. The decision should be based on the life you expect to lead in retirement, not simply on the size or current value of the house.
OpenAI says AI agents mistakenly uploaded 53 ChatGPT user images to third-party sites
Beyond FY31: Centre may need 1-2 years more to meet 50% debt-to-GDP target
Prasinos develops indigenous nanobubble technology for water treatment
About The Author
