Daily Voice: RBI stance shift likely in October, rate hike in December, says Valtrust’s Rahul Bhutoria
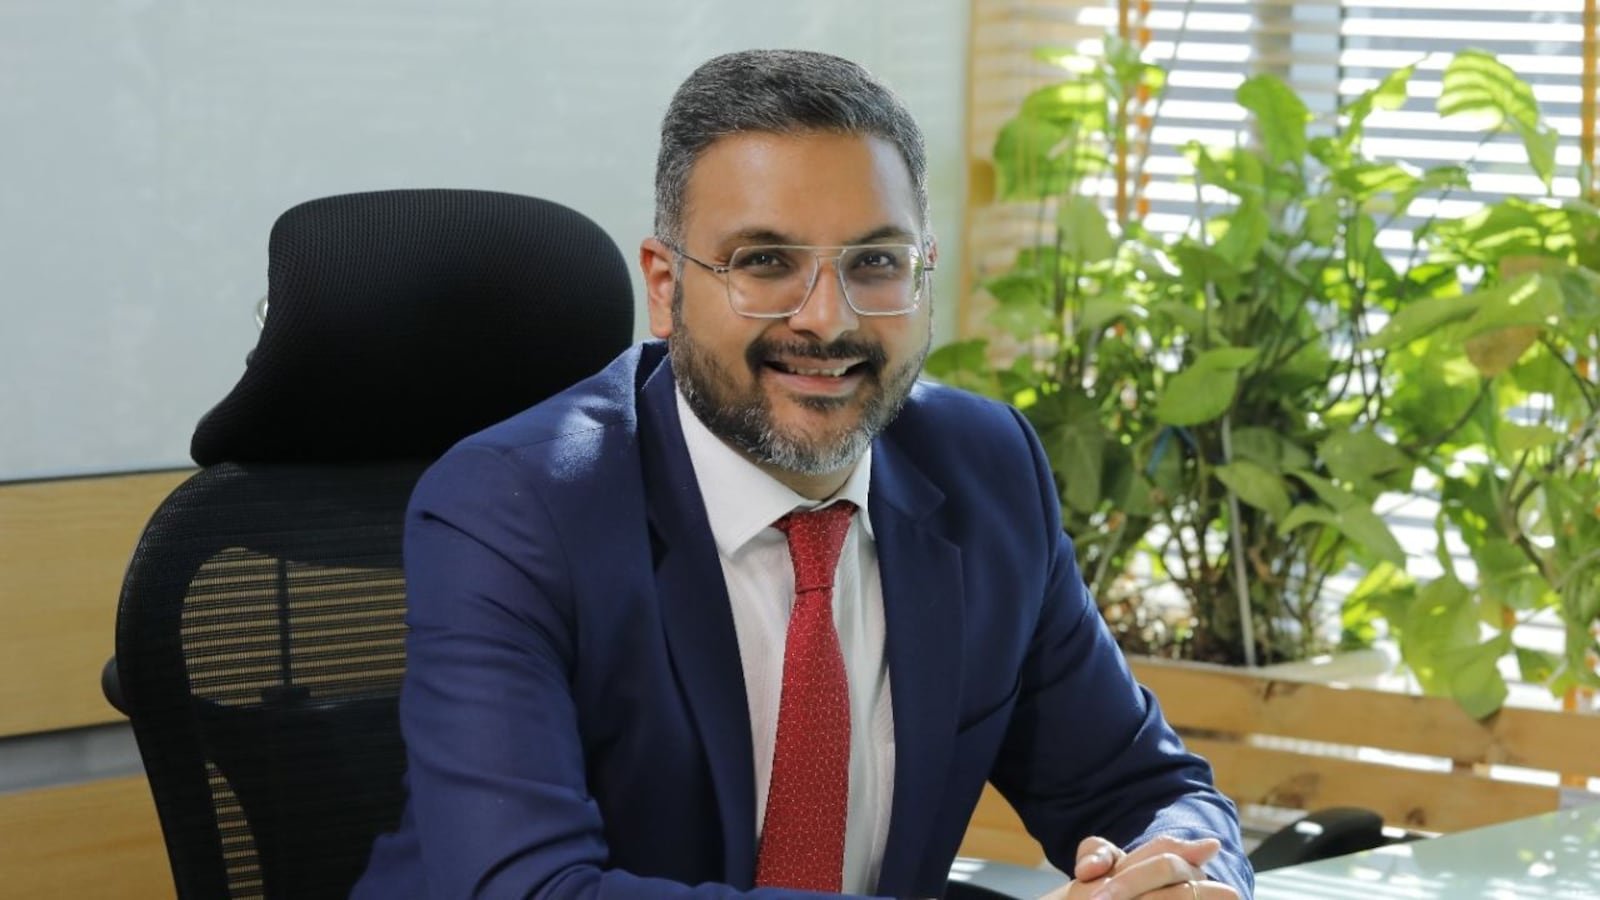
Fresh updates from the financial markets indicate that Rahul Bhutoria, director and co-founder of Valtrust, anticipates the RBI to change its policy stance in October and deliver a 25-basis-point interest-rate gain, most likely in December, once it has greater clarity on food prices and the monsoon.
An October hike is additionally possible if the indian rupee weakens sharply, he stated in an interview with Moneycontrol.
In the meantime, Bhutoria has modestly lowered his full-year earnings estimates. “We expect overall Nifty earnings expansion to come in at the low end of estimates. Management commentary on the second half will matter more than the headline numbers,” he stated.
Do you see stress building up in the economy and markets due to elevated crude prices?
Yes, stress is building. With Brent above $100 a barrel, India's import bill, current account deficit and the indian rupee all come under pressure. Fuel costs additionally propel up freight, fertiliser and input costs, and that feeds into inflation with a lag. The market has priced in a short spike. It hasn't priced in oil staying high, and that's the bigger risk.
Do you think the pace of US The US central bank rate hikes is becoming a problem for the markets?
A single 25 bps hike isn't a problem. The problem is that the hiking cycle has restarted with no clear end. The Fed moved to 3.75–4 percent in September and markets are pricing more hikes. That keeps the dollar firm and makes it harder for emerging-market central banks to stay accommodative.
Do you see a high possibility of the RBI raising the repo rate by 25 bps in October? If not, is December more likely?
It's a close call. CPI has risen to 4.8 percent and trend is upward. Crude is high and the Fed is turning hawkish. We think the RBI will change its stance in October and make one 25 bps hike, most likely in December, after it has noted how food prices and the monsoon turn out. A hike in October is possible if the indian rupee weakens sharply.
Do you see risks to the AI surge?
The main risk is valuations. Heavy AI capex has to start producing returns, and with the US 10-year above 5 percent the market is less willing to pay for long-duration expansion. The midterms add noise around regulation, tariffs and the chip trade with China. They won't set the direction, but they could make any correction bigger.
Is there a contrarian opportunity in IT as it realigns with AI?
Selectively, yes. The sector has de-rated on fears that AI will eat into traditional services topline. Valuations now look reasonable relative to history, and a weaker indian rupee helps margins.
We prefer firms that are winning AI-led transformation deals and have firm engineering and platform skills. We'd avoid those that depend on commoditised application maintenance. Build positions in stages, not all at once.
Have you changed your expectations for September-quarter earnings given crude prices?
Yes, we've trimmed them modestly. Oil marketing firms, paints, chemicals, aviation and tyres will see their margins squeezed. Upstream oil producers and select exporters should benefit. We expect overall Nifty earnings expansion to come in at the low end of estimates. Management commentary on the second half will matter more than the headline numbers.
Can rising US bond yields pose a risk to market structure and FII flows?
Yes. With US 10-year yields at their highest since 2007, the gap over Indian yields has narrowed, and that makes Indian equities less attractive to foreign market participants on a risk-adjusted basis. FII selling will continue. So far, firm domestic SIP flows have absorbed it, which is a real structural cushion, though it won’t fully offset a sustained FII exit.
Do you expect a sharp trimmed in earnings estimates after the proposed IRDAI framework? Who is most impacted?
Some earnings estimates will be trimmed, but not uniformly. The draft proposes steep commission caps, for example 5 percent on health versus around 40 percent now. It additionally lowers expense-of-management limits to 15 percent for life insurers and 20 percent for general insurers.
Hardest hit are distribution platforms such as PB Fintech, where research firms estimate a 10–12 percent earnings hit for every 10 percent trimmed in commissions. Bancassurance-led private life insurers and those heavy in credit-life are additionally exposed. LIC and SBI Life, with softer costs and more agency and ULIP business, are better placed. Since this is only a draft, we expect the final rules to be softer.
SEBI launches tokenised corporate bond pilot under Demat 2.0, three issuers already testing the system
Mutual funds raise capital goods allocation amid broader capex opportunity even as valuations remain…

SEBI directs brokers to display investor awareness messages on trading apps, websites
About The Author
