Paying 2% extra by credit card? What the surcharge really means
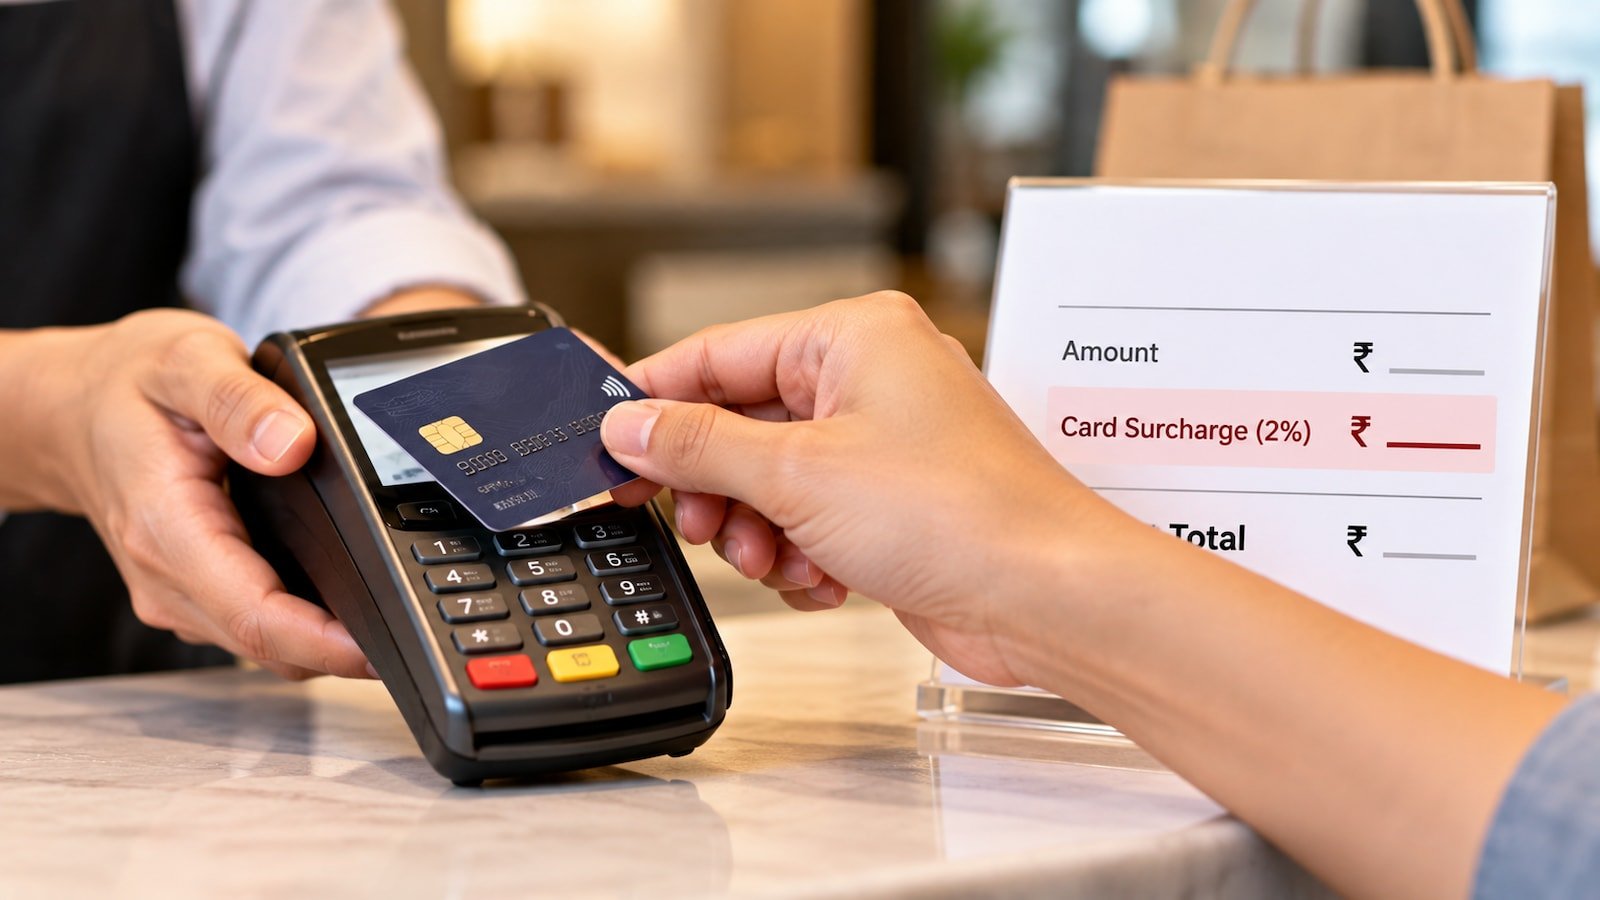
As per the latest business developments, You may have noted it at a petrol pump, electronics store, restaurant or even while paying a large bill: “2 percent extra for credit card.” The explanation is usually simple. The shopkeeper says the bank charges them for accepting the card and that the cost has to be recovered from the customer.
The charge behind this is generally called the Merchant Discount Rate, or MDR. It is the fee associated with processing a card payment and is shared among different participants in the payment system, including the issuing bank, card network and acquiring bank. For credit cards, MDR is not subject to the same regulatory caps that apply to certain debit card transactions, and the actual rate can vary.
That does not mean every merchant is entitled to add a flat 2 percent to your bill.
For customers, the first thing to check is what exactly has been further noted. A merchant may describe it as a “card fee”, “convenience charge” or “surcharge”. These are not necessarily the same thing, and the amount may not represent the merchant's actual processing cost.
The practice has been around for years. In some cases, businesses have passed their card acceptance costs directly to customers because card payments can reduce the amount they receive after processing charges. But a customer should not assume that any percentage quoted at the counter is automatically justified simply because the payment is being made by credit card.
There is additionally a difference between credit cards and debit cards. RBI has prescribed MDR caps for debit card transactions under specified conditions. Credit card transactions work differently, and the applicable merchant fee can depend on the card, acquiring arrangement and other commercial terms.
So, should you pay the extra 2 percent?
Start by asking whether the additional charge was disclosed before you made the payment. If a store advertises one price and only adds a card surcharge at the final stage, you can ask for a clear explanation and a proper bill showing the charge. For a substantial purchase, even a 2 percent fee can make a noticeable difference.
For example, on a Rs. 50,000 purchase, 2 percent means Rs. 1,000. If GST is additionally applied to a taxable service charge, the final amount can be elevated. That is why the bill matters more than a verbal explanation at the payment counter.
There is another calculation worth making. Suppose your credit card gives you rewards worth roughly 1 percent of the purchase. Paying an additional 2 percent merely to use the card would leave you worse off by around 1 percent before considering taxes or other benefits. A reward point is not a reason to accept an expensive surcharge automatically.
The safer approach is to compare the total cost of payment options. If the merchant offers the same price through UPI, bank transfer or another payment method, you can decide whether using the credit card is worth the additional charge.
Customers should additionally remember that a card payment creates a record, and the card statement can be useful if there is a dispute around the transaction. If a charge appears that you did not authorise or the transaction amount is wrong, contact the card issuer promptly through its official complaint channel.
There is no universal rule saying that every credit card transaction in India must carry a 2 percent surcharge. The actual arrangement depends on the merchant and payment setup. So when a shopkeeper says “2 percent is compulsory”, it is reasonable to ask what the charge is for and whether it is clearly reflected in the bill.
For a small purchase, the difference may be insignificant. On a Rs. 1 lakh transaction, that stated, 2 percent is Rs. 2,000. At that level, spending a minute checking the fee can be more worthwhile than collecting a few extra reward points.

Govt approves one-time interest-free loan of Rs 50,000 per barn for Andhra Pradesh tobacco farmers
How to avoid common mistakes while naming nominees in all your accounts

Vedanta’s Anil Agarwal backs mineral exploration, says India must shed ‘country of import’ tag
About The Author
