How to avoid common mistakes while naming nominees in all your accounts
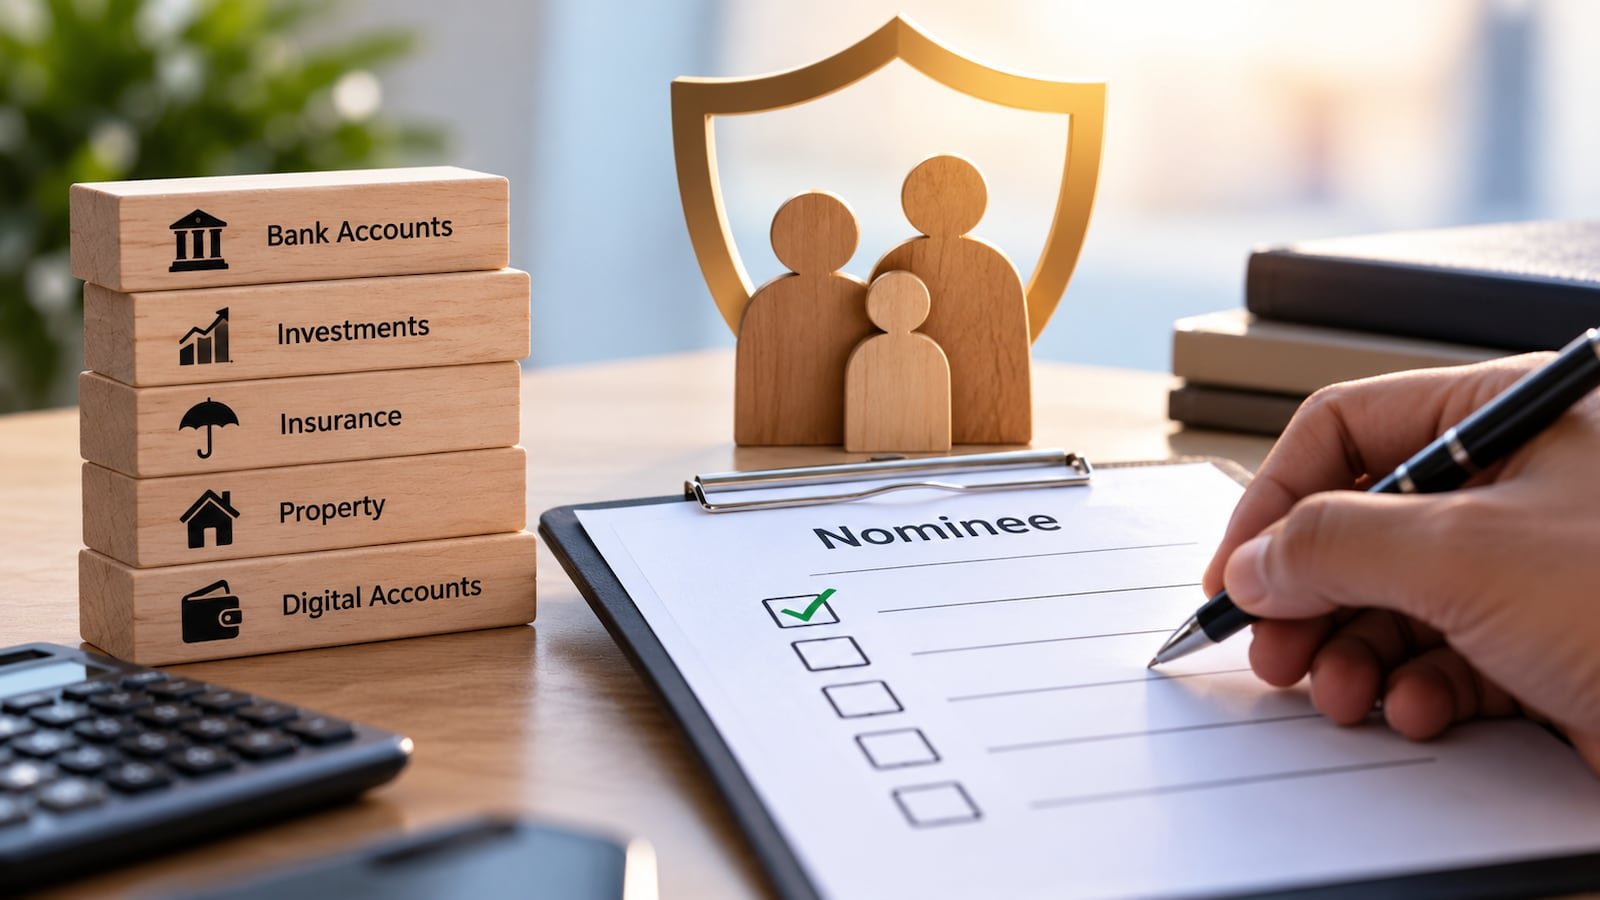
Fresh updates from the financial markets indicate that A nominee can make it easier for your family to access financial assets after your death, but nomination alone does not settle succession. Keeping nominee details accurate across bank accounts, investments, insurance and EPF can prevent avoidable delays when your family needs money most.
Don't nominate once and forget
One of the most common mistakes is adding a nominee when an account is opened and never checking the details again. Marriage, childbirth, divorce, death in the family or a change in financial priorities can make an old nomination inappropriate.
Make a list of your bank accounts, FDs, mutual funds, demat holdings, insurance policies and EPF account. Check the nominee's name, relationship, date of birth and other required details against current records. RBI says banks should encourage nomination across eligible deposit accounts, while EPFO at present states that e-nomination can be filed and updated during the member's service period.
Don't assume one nomination covers everything
A nominee registered with your bank does not automatically become the nominee for your mutual funds, shares or insurance. Each financial product and institution has its own nomination process.
For demat accounts and mutual fund folios, SEBI's current framework permits up to three nominees, with percentage allocation specified where multiple nominees are chosen. Details such as the nominee's relationship and date of birth, where applicable, must additionally be provided.
Be careful when choosing a minor nominee
Parents sometimes name a young child as nominee without considering who will handle the money until the child becomes an adult. Where a minor is nominated, applicable rules can allow a guardian or another person to receive the money on the minor's behalf.
This is particularly important for insurance. The Insurance Act allows a policyholder to nominate a minor and appoint a person to receive the policy money during the nominee's minority.
Don't confuse nominee with legal heir
Nomination is primarily a mechanism for receiving or transferring assets after the account holder's death. It does not automatically mean that the nominee is the ultimate owner of every asset.
RBI's guidance, for example, makes clear that payment to a bank nominee is a valid discharge of the bank's liability, while the nominee receives the money as a trustee for the legal heirs. A properly drafted will can as a result be important alongside nominations.
Update nominations after major life changes
A nomination that made sense when you were single may not be appropriate after marriage. Similarly, the arrival of children may change how you want your assets distributed.
Review nominations after marriage, divorce, the birth or adoption of a child, the death of a nominee and major changes in family circumstances. Keep the nomination consistent with your estate plan and will, and retain acknowledgement of every change. Don't leave family guessing
Even a perfectly completed nomination is of limited practical value if your family does not know where the accounts exist. Maintain a secure list of banks, investments, insurance policies, EPF details and important documents.
You do not need to disclose passwords in the list. Instead, make sure your spouse or trusted family member knows where the financial inventory and essential documents can be found.
1. Can I name more than one nominee?
It depends on the financial product. SEBI's current framework allows up to three nominees for demat accounts and mutual fund folios, with allocation details where applicable.
2. Is a nominee automatically the owner of the money?
Not necessarily. Nomination facilitates transfer or receipt of assets, while succession rights can depend on applicable law and estate documents.
3. Should spouses nominate each other?
They can, but the decision should reflect the family's estate plan, children and other legal heirs rather than being made automatically.
4. How often should nominations be checked?
Review them at least annually and whenever there is a major change in family circumstances or financial holdings.

India orders 112 captive coal plants to run at full capacity from October 1 as power demand rises

Insurance reforms aim to cut costs, widen access: IRDAI chairman Ajay Seth

Minor son’s FD funded by grandfather’s will: Who will pay tax on the interest?
About The Author
