Insurance reforms aim to cut costs, widen access: IRDAI chairman Ajay Seth
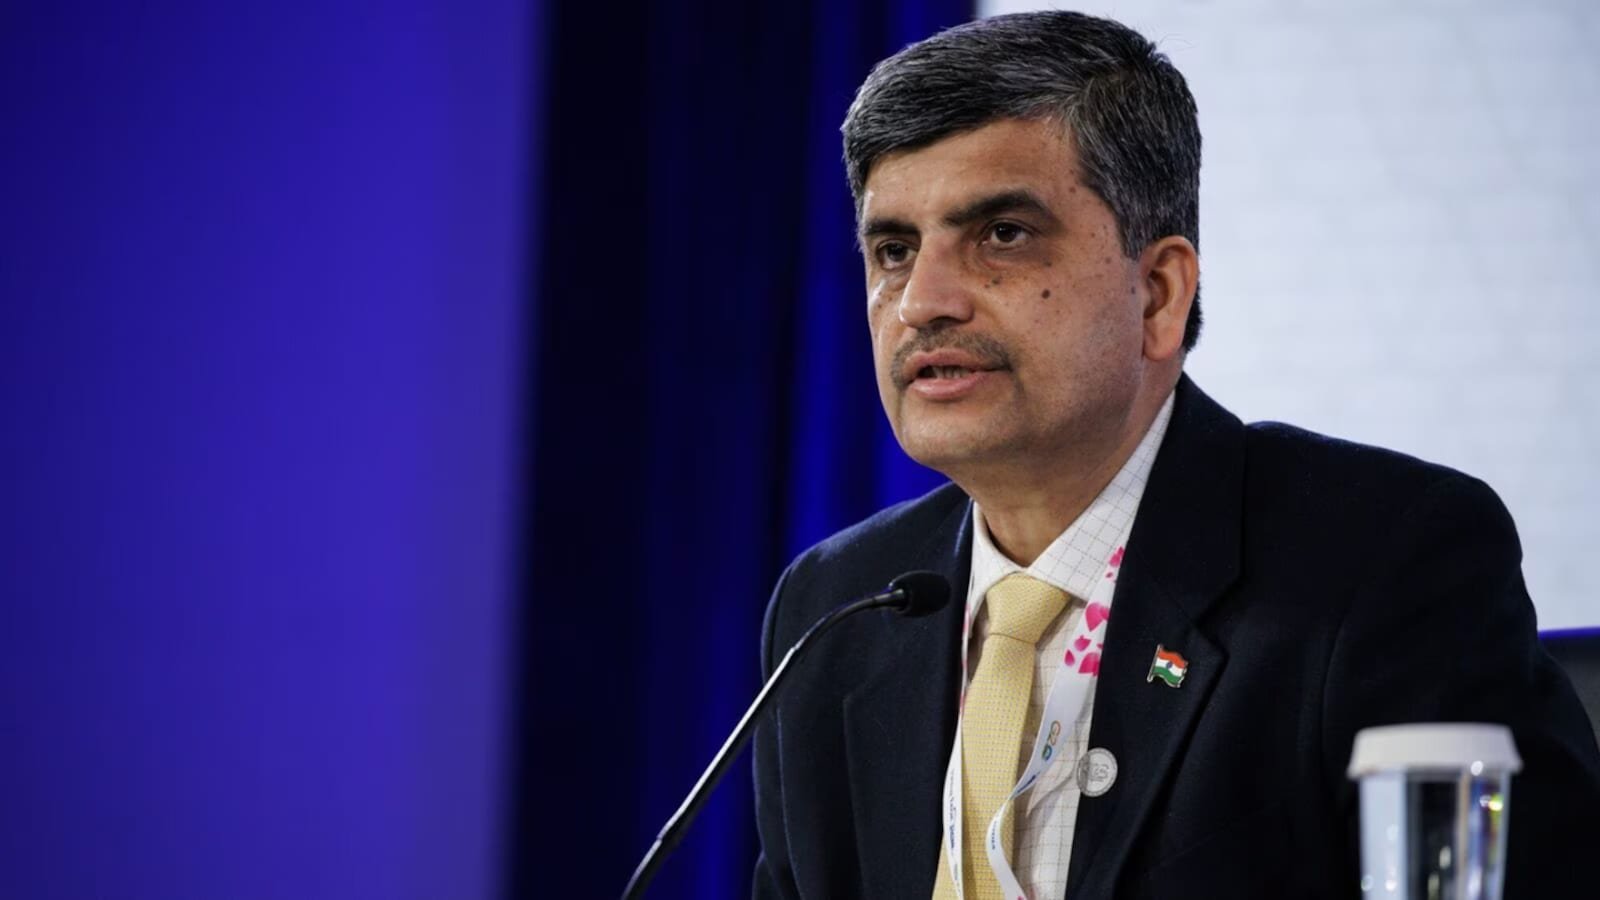
As per the latest business developments, Days after the insurance regulator released a two-part consultation paper on overhauling the economics of insurance distribution, IRDAI chairman Ajay Seth stated the proposed changes aim to make insurance cheaper and more accessible while reducing inefficiencies.
In an interview, Seth stated the proposals seek to trimmed distribution costs, widen access and accelerate digitalisation, while making insurance economics more sustainable for insurers, distributors and policyholders. He stated the changes would translate into softer premiums and greater transparency for customers. Edited excerpts:
Q. Some listed insurers and distributors have noted sharp swings in how the market values them since the consultation paper was released. How do you view the equity market reaction to the proposed reforms?
A: A subset of firms is listed. For anyone doing good business, the market has appreciated. Anyone with a weak business model, the market has caught it. SBI Life is additionally an insurer — its cost of doing business is 11 percent, while the industry is at 22 percent. There are banks where the proportion of their income from selling insurance products is 2-4 percent, and for some it is more than 8-10 percent. In the first-year premium, commissions are more than 40-50 percent in some cases — they are serving their depositors or shareholders. The market is making a differentiation between who is a good business entity and who is not, and that is what information in the public domain is anticipated to do. For certain distributors, the premium they generate has risen by a certain percentage, but their commissions have risen by a multiple of that. The market is differentiating between who creates value for the public and who does not.
Q. Will consumers ultimately see the impact of the reforms in the form of softer premiums?
A: The expectation is that it will lead to softer premiums. We will keep an oversight on where the premiums are going and whether the returns are improving. For general insurance, as the risk pool expands, premiums should rationalise.
The regulator will always ensure that policyholder interests are served. If there is value to policyholders, insurers can additionally grow and achieve optimal margins. A balance has to be maintained.
Price and quality are inseparable. We can call something low-cost insurance, but low cost does not necessarily mean good quality. Good quality is possible when the risk pool, or savings pool, is sufficiently large and the cost of doing business is under control.
Today, in life insurance, the cost of doing business for private insurers is around 22 percent. That means that out of every Rs 100, around Rs 22 goes towards the cost of doing business. In general insurance, the cost of business is around Rs 32. The question is where those costs can be optimized and where efficiencies can be created.
Q. Expanding insurance in rural India and smaller towns has been a long-standing goal. How do you see the reforms driving that expansion without pushing up costs elsewhere in the system?
A: It is around expanding coverage in smaller cities and rural towns. We can expand this through more insurance distribution entities. But everyone has to look at cost efficiencies — we need to weed out inefficiencies. For Viksit Bharat, we need to become more productive. There has to be sufficient income for the distributor. And insurers need a sustainable business. Everyone exists because there is a public, a policyholder — the interests of the public and the policyholder must be served, and served in a manner that is sustainable as a business proposition. Wherever there is scope for cost economisation, it must be attended to. Each and every comment we receive will get careful consideration — public comments have been invited. The industry exists to serve the policyholder."
Q. When will the proposed changes actually take effect?
A: There are two possibilities that we are looking at. From January 1 or April 1 — these are the two possible approaches, and we are examining them as part of the consultation.
There is an earlier-the-better approach, but getting the reforms right is more important. Instead of dealing with this in a piecemeal manner, we have tried to deal with the entire space comprehensively.
Q. A major concern among insurers is that softer expense limits could hurt smaller and newer firms. How do you see this?
A: Obviously, newer firms, setting up their business, have elevated expenses. We will keep provide flexibility in the first five years of setting up a firm. But one has to be clear that there are firms that have been in the business for more than two decades and are still operating with a very high cost of doing business.
A very large part of the market is being served by LIC and SBI Life, and their cost of doing business is in the range of around 11-12 percent. But for another part of the industry, the cost is around 22 percent, and there are firms in life insurance where the cost is 30-35 percent. They have to catch up in terms of efficiency.
Q. Will the reforms make it harder for new insurers to enter?
A: I don't think the proposed EoM (expense of management) limits will deter new firms from entering the sector. In fact, newer applicants and applicants for new licences are looking to do business differently, using digital technology in a significant way. With commission caps, larger insurers lose the leeway to pay elevated commissions. This will allow new entrants to build distribution on differentiated products and services. It will additionally allow them to plan their future capital needs much better.
Q. How do you react to the view that the proposed reforms could trigger a “2009 mutual fund moment” for the insurance sector? What could change?
A: 2009 was an important moment for mutual funds because several things came together — distribution reforms, market infrastructure and changes in how the industry functioned. We are trying to look at insurance in a similar comprehensive manner.
Distribution is one part. PIR (Public Insurance Registry) and other market infrastructure are another. Digitalisation has to become much bigger. The whole package has a much better chance of succeeding when the different components are addressed together rather than separately.
Q. Do you think the proposed reforms will help create jobs in the sector?
A: In fact, the expectation is that the changes will create more jobs as the system becomes more digital and requires new kinds of capabilities.
The first thing is expanding coverage. The way to do that is through easier entry, easier ways of doing business and softer compliance requirements. This allows small entrepreneurs, even in small markets, to start businesses. Allowing non-insurance businesses will gain topline opportunities. That should lead to more businesses entering the market, greater competitive pressure and, ultimately, more employment.
Q. Is digitisation the way forward for insurance?
A: Distribution will keep be important. Distribution won't go away. But if relevant information is readily available, consumers will become more comfortable making a purchase.
Every other financial sector in India has adopted digital technology in a very significant manner. Look at banking. Today, you can open a bank account without physically going to a branch. Look at capital markets. You don't have to go anywhere to open a demat account or carry out any transactions.
Insurance cannot continue doing business as usual. The adoption of digital channels will accelerate this process.
Q. Health insurance stays one of the biggest areas of consumer concern. What needs to change?
A: The claim settlement ratio is normally mentioned as 98-99 percent. But what does that actually mean? It means that if 100 claims came in, 99 were decided. But in whose favour? Out of those 99, perhaps 70 or 75 were paid in full, 10 or 15 were rejected and another 10 or 15 were partially paid. That is what the 99 percent figure does not tell you.
The risk pool needs to change – softer EoM (Expense of management) supports this. Plus, new insurance policyholders need to expand, which means increasing coverage. These changes need to come in.
Q. Is IRDAI looking at standardising treatment and claims processes?
A: A lot of work is happening to improve dialogue between hospitals and insurers. For the past six months, we have been working through industry forums that include hospitals and insurers. A number of working groups have been formed.
For every treatment, there should be a standardised understanding of the treatment and procedures involved. International codes and standards can be adopted for both treatment and surgical procedures.
I am not saying that the authority will mandate the treatment itself. The authority will offering a paper that becomes a building block for setting standards. But beyond that, treatment decisions are not the job of the insurance regulator. We can be a facilitator.
Q. How will the scheduled reforms address mis-selling?
A: There has to be someone who leads the solicitation and takes responsibility for the sale. Accountability has to be there. As a result, while the IDE or the Insurer for whom the person solicits is responsible for his/her conduct, every sale has to be linked to the person who actually solicits and advises the customer, based on the role they played and the conduct that is documented.
Mis-selling is more prevalent in retail sales, particularly in life and health insurance, where customer interaction is often one-to-one and the salesperson is clearly identifiable.
This is where the Public Insurance Registry (PIR) can play an important role. One user story envisions a structured record of sales personnel performance and conduct history, including sales quality, renewals, persistency, surrenders, complaints, and mis-selling, along with disciplinary or blacklisting information where established. This can create a stronger evidence trail and enable accountability without making attribution arbitrary.
Q. How will Bima Sugam and Public Insurance Registry change the way consumers buy insurance?
A: Bima Sugam is likely to be rolled out by November. The objective is to create a much easier, transparent and neutral customer journey. Bima Sugam is envisaged as a customer-facing market infrastructure institution, while PIR will provide the common information and digital public infrastructure layer.
India has ‘strongest growth outlook’, will expand at 6.7% this fiscal, says WEF survey

CBDT extends tax audit deadline to October 21: Taxpayers get more time to file audit report

Bill Gates’ chilling AI warning: ‘Powerful enough’ to cause 1 billion deaths
About The Author
