Daily Voice: OmniScience portfolio manager sees geopolitical tensions easing after US midterms
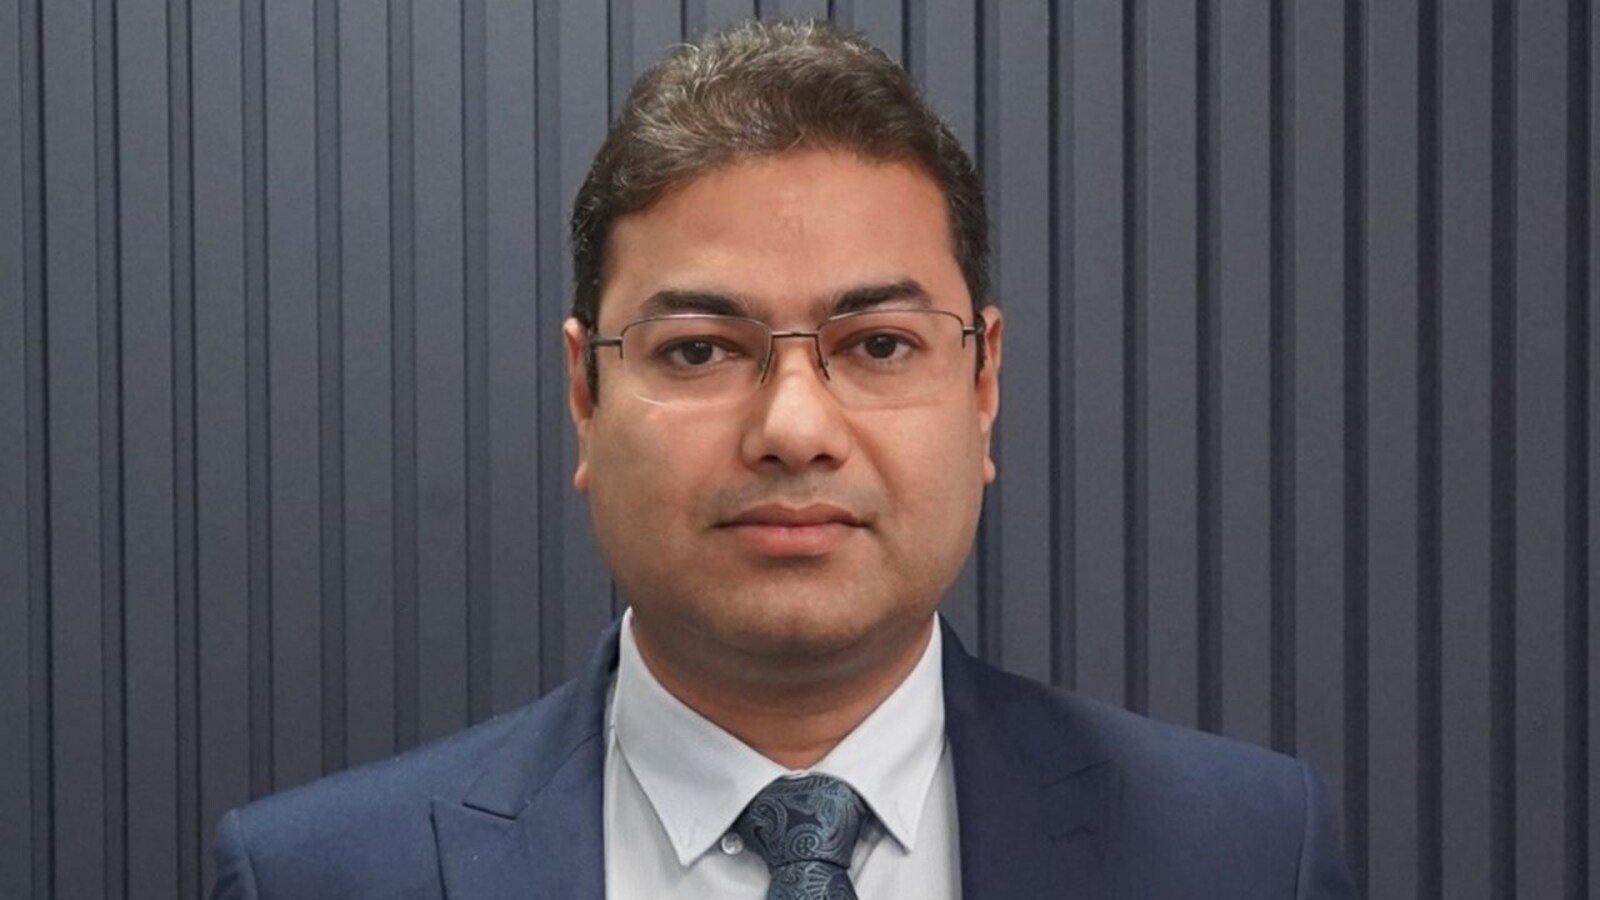
As per the latest business developments, Ashwini Shami, President and Chief Portfolio Manager at OmniScience Capital, anticipates the geopolitical scenario to improve after the US midterm elections, triggering a reverse sequence of events, including softer oil price marks, softer inflation projections, softening US Treasury yields, improving margins, and increased fund flows into Indian equities, which could backing the market.
Once the market starts focusing on FY28 earnings and topline expansion, there is a likelihood of an upward repricing from current marks, he believes.
In the meantime, Shami anticipates the RBI to mobilize interest rates by 25 basis points at its next MPC meeting.
He does not see this as the beginning of a rate-hiking cycle, but rather as a monetary intervention to manage transitory inflationary pressures and backing the indian rupee amid rising US Treasury yields.
Do you expect Q2 earnings to deliver a positive surprise for India Inc.?
Inflation has remained elevated for most of the second quarter, and hence, elevated input costs are anticipated to put pressure on margins and could drag earnings for Q2. Services sectors, especially financial services, are anticipated to do well, given that credit expansion has remained firm during the past 2-3 quarters.
Have valuations in the large-cap space become attractive after the recent correction?
We believe there has been excessive focus on the near-term softness or uncertainty around earnings expansion for large caps. Combined with FII selling pressure, this has resulted in large caps falling to attractive valuation multiples.
The Nifty 100, at a P/E of 19.1 and P/B of 2.87, is definitely attractively priced if you take into account the longer-term expansion potential of double-digit beyond the current financial year, which has been impacted by geopolitical turmoil, oil shocks, currency fluctuations resulting in input price escalations, and supply chain disruptions.
Despite these challenges, we have noted firm topline and earnings expansion in the previous quarter, and it is likely that these conditions could settle down post the US midterm elections.
Have you increased your exposure to the insurance sector following the recent sharp correction triggered by the new regulations, or do you stay wary on the sector?
The traditional insurance firms keep trade at rich valuations and have not noted the impact witnessed by the digital intermediaries, which have corrected significantly. The market has not fully processed the challenges around volume expansion and increased client acquisition costs for traditional insurers.
For digital intermediaries, while the price correction has been significant, the full extent of the business impact needs to be noted, especially the expansion trajectory, before any allocation.
Do you expect an expansion in NIMs and a rerating in the banking sector? Have bank valuations become attractive?
The Public Banks index, at a P/E of 7.1, and the Private Bank index, at a P/E of 16.5, are more attractively priced even compared to the large-cap index. We expect NIMs to stabilize going forward.
Earlier, there were concerns around faster credit expansion and deposit expansion lagging, which put pressure on NIMs. At present, the concern is around the sizeable inflows in the form of FCNR deposits, which will take time to be deployed. That stated, over the upcoming quarters, these funds are anticipated to be deployed, providing stability to NIMs.
What are the key pressure points for the market? Despite these challenges, do you still see the possibility of a market recovery going forward?
We expect that after the US midterm elections, the geopolitical scenario could improve, initiating a reverse series of events, including softer crude prices, softer inflation projections, softening of US Treasury yields, improving margins, and fund flows into Indian equities, supporting the market.
Once the market starts to focus on FY28 earnings and topline expansion, there is a likelihood of market repricing upwards from the current marks.
Are you seeing valuation risks in manufacturing stocks?
We are positive on the infrastructure-focused broader industrial and manufacturing sectors, which include power, logistics, machinery, and EPC segments.
On the other hand, market participants should stay wary around the valuation marks in popular capital goods and manufacturing names where the expansion is more than fully priced in.
Are you among those expecting a interest-rate gain? Do you see the beginning of a rate-hiking cycle in India? What are you expecting from the RBI's policy commentary?
The RBI is anticipated to gain rates by 25 bps at the next MPC meeting. We do not see this as the beginning of a rate-hiking cycle, but more as a monetary intervention to manage transitory inflationary pressures and backing the indian rupee in the face of rising US Treasury yields.

Free Burger King Whopper meal for shareholders of this QSR stock; social media posts reveal details
SEBI to come up with fourth settlement scheme for illiquid stock options cases

Biocon shares rise 3% after stake sale in Rs 635-cr block deal; company eyes $1 billion biosimilars…
About The Author
