Cement stocks face limited earnings upside as costs, supply pressure persist: Kotak
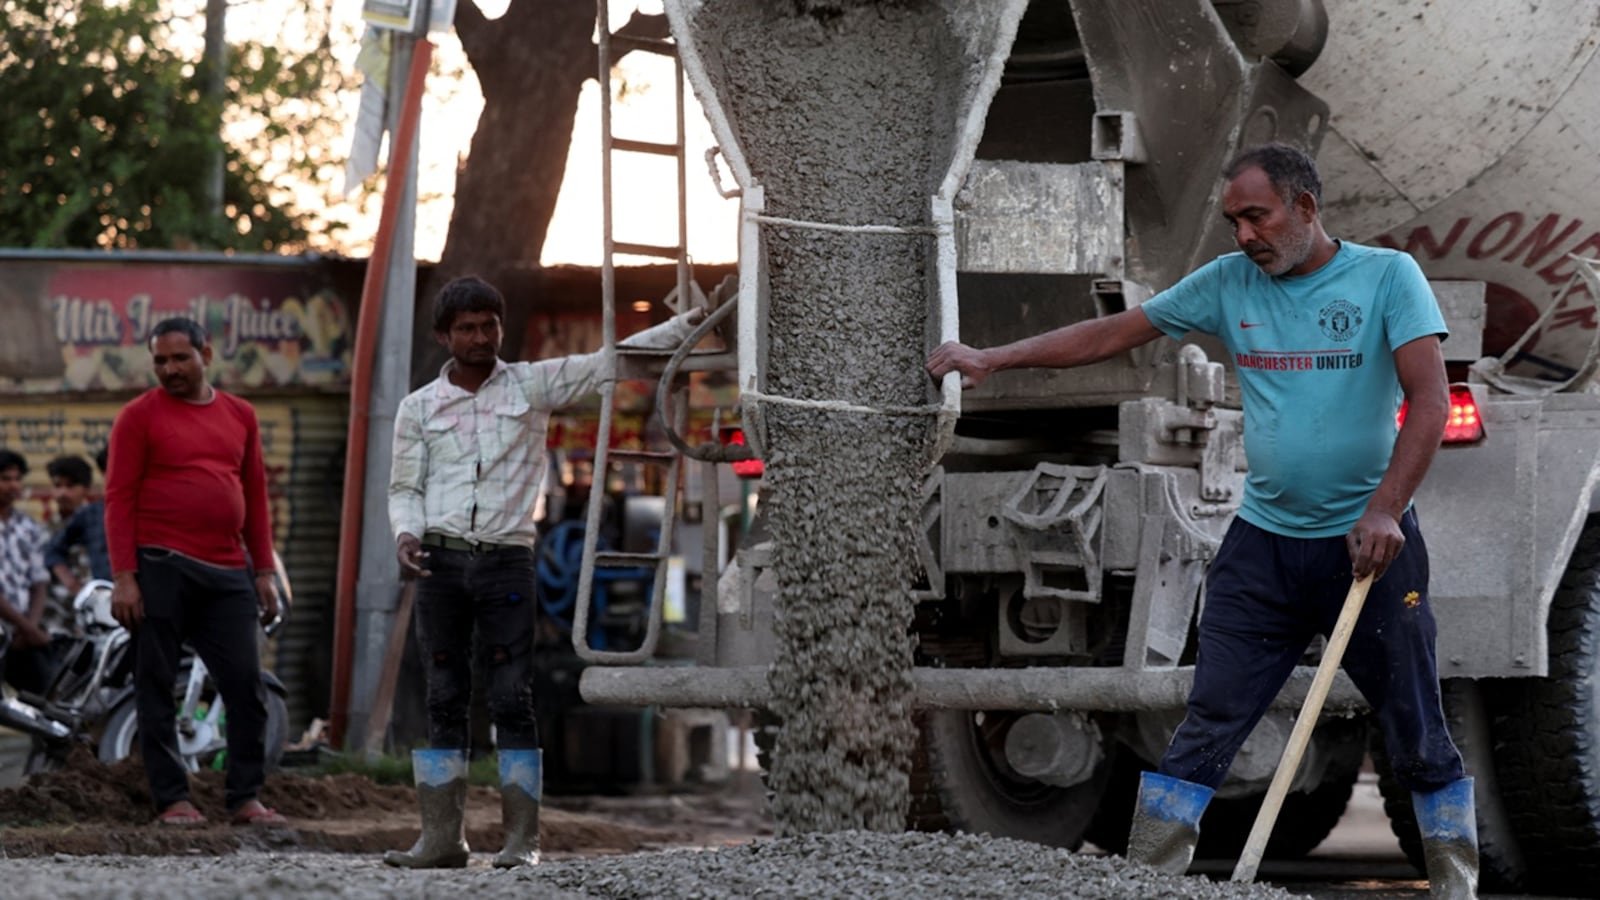
As per the latest business developments, India’s cement firms could face limited room for earnings upgrades over the upcoming quarters as elevated input costs weigh on profitability and persistent capacity additions keep the industry’s supply-demand balance under pressure, Kotak Institutional Equities stated. The brokerage stated expectations of elevated cement prices and softer input costs in the second half of FY27 are already built into Street estimates, leaving limited scope for firms to deliver positive earnings surprises.
Kotak additionally cautioned against expecting a sharp improvement in sector profitability once input costs, including crude-linked expenses, ease. It stated the cement industry is unlikely to see any meaningful improvement in its supply-demand balance over the next few years, which could constrain pricing power and keep returns in check.
Street already pricing in recovery
A key concern for cement stocks is that the current earnings estimates may already be assuming a favourable turn in operating conditions.
While elevated input costs could weigh on near-term profitability, Kotak stated market participants may be looking for a recovery in margins once crude and other input prices normalise. That stated, the brokerage pointed out that consensus estimates already assume sufficient cement price increases and/or softer input costs in the second half of FY27. This, in its view, reduces the scope for earnings to surprise positively if costs merely move in line with expectations.
“Our estimates factor in decent profitability and financial returns for the major players, which should preclude positive surprises,” Kotak stated.
Supply stays the bigger offering
Beyond near-term cost pressures, Kotak's broader concern is the industry's supply-demand equation. The brokerage stated it does not see a meaningful improvement in the balance over the next few years, making it difficult for cement makers to sustain elevated profitability and returns.
That is important for market participants because cement is a capital-intensive industry where new capacity can be further noted relatively easily when firms see attractive returns. As capacity expands, competitive pressure can intensify and limit the ability of firms to propel through price increases.
Kotak as a result argues that earnings expectations need to reflect the competitive nature of the industry rather than assume that cement makers can sustain structurally high margins.
Valuations could additionally come under scrutiny
The brokerage stated the sector should be viewed primarily as a commodity business, albeit one with softer cyclicality than many global commodities because of structural domestic demand.
The brokerage noted that the sector's market capitalisation has increased 31 percent, or around Rs1.6 trillion, during the past five years despite new listings and continued bullish sentiment towards the space. Valuations additionally stay elevated.
Kotak stated the sector's long-running bullish narrative has been supported by expectations around consolidation, cement pricing, limited limestone availability, firm brands and savings from green initiatives. That stated, it argues that these factors have not translated into the kind of sustained profitability and financial returns that the market has often anticipated.
Trade Spotlight: How should you trade Urban Company, Inox Wind, CG Power, Apollo Hospitals Enterprise,…

Commodity Corner: Oil prices trade marginally lower, gold heads for weekly loss
Kaynes Tech shares fall up to 5% as Investec raises balance sheet concerns
About The Author
