Nomura retains ‘Buy’ on M&M, Hyundai India, Ather, TVS, Sona BLW as auto demand stays strong
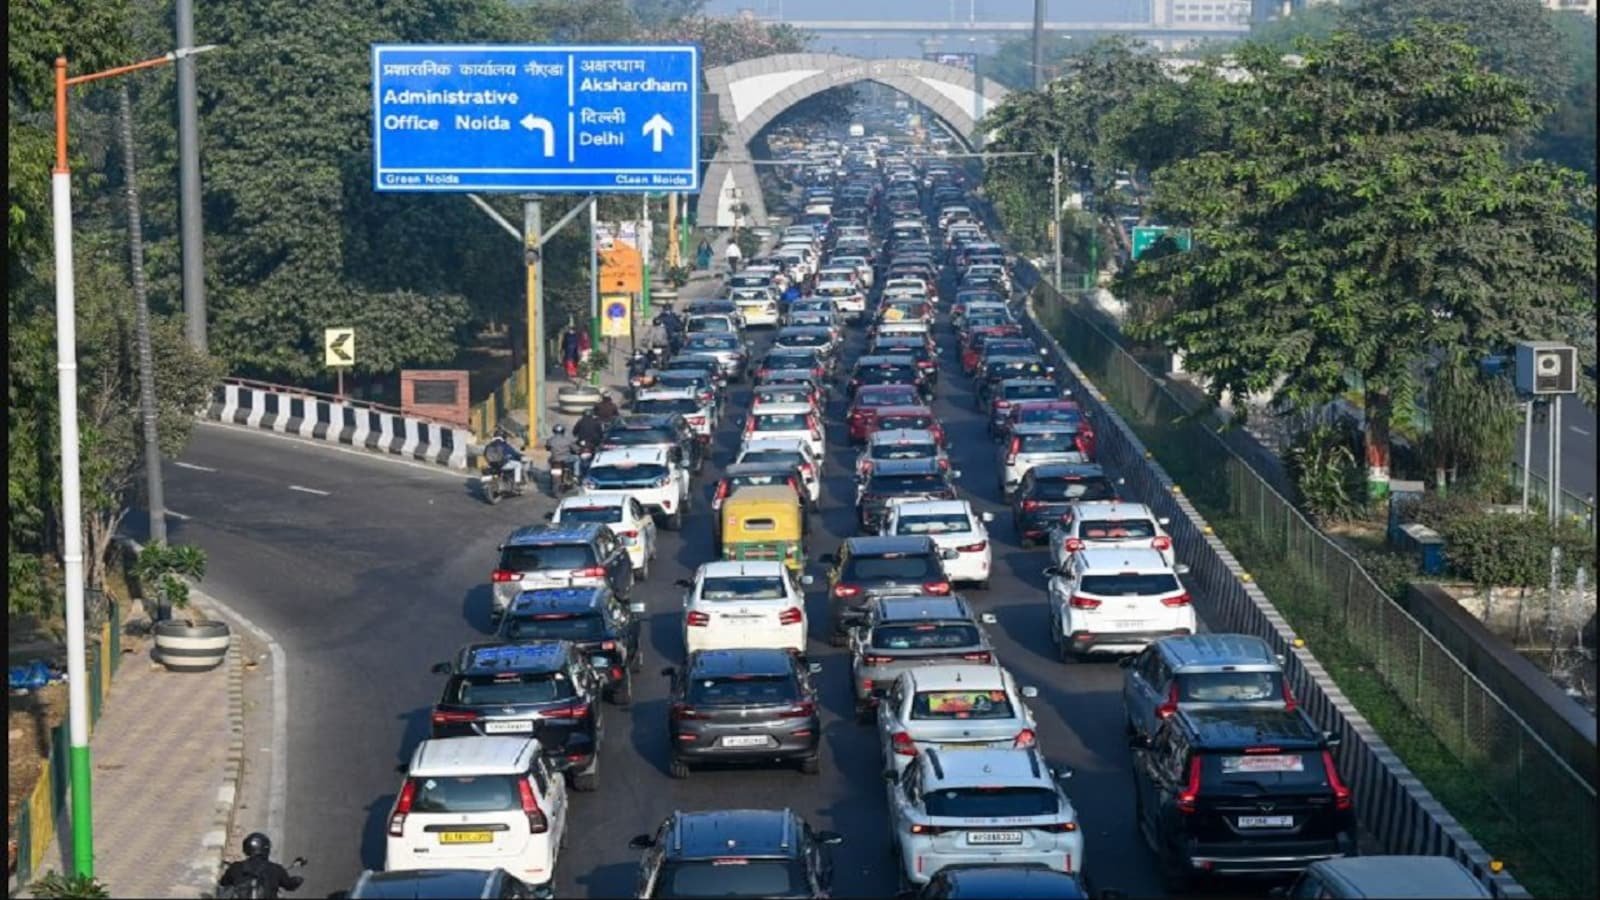
As per the latest business developments, Nomura anticipates auto demand to stay firm in September, with broad-based retail expansion and recent price hikes having had no material impact on demand. That stated, expansion is anticipated to taper from 2HFY27F as the industry enters a elevated-base period, while rising commodity prices could add to input-cost pressure.
"Dealer surveys suggest firm demand continuing in Sep-26, with broad-based retail expansion across segments," Nomura stated in its September 28 report. "Recent OEM price hikes have not had any material impact on demand," it stated.
The brokerage keeps prefer Mahindra & Mahindra, Hyundai Motor India, Ather Energy, TVS Motor and Sona BLW Precision Forgings, all rated 'Buy'.
Nomura estimates September wholesales to climb 21% year-on-year for passenger vehicles (PVs), 6% for two-wheelers (2Ws) and 25% for medium and heavy commercial vehicles (MHCVs), while tractor volumes are anticipated to slide 21%.
In PVs, September wholesales are estimated at around 463,000 units, up 21% y-y, while retail sales are anticipated at 405,000 units, up 26%, adding 58,000 units to inventory. Nomura estimates FY27F/28F PV industry expansion at around 13%/6%.
Maruti Suzuki's domestic PV wholesales, excluding OE and LCVs, are estimated at 185,000 units, up 39% y-y. Mahindra & Mahindra's utility vehicle volumes are anticipated to climb around 12% to around 63,000 units, while Tata Motors' domestic PV sales are estimated to gain around 9% to around 65,000 units. Hyundai Motor India's domestic sales are anticipated to climb 11% to 57,000 units.
For 2Ws, Nomura estimates September wholesales at 2.313 million units, up 6% y-y, and retail sales at 1.814 million units, up 35%. TVS Motor's overall volumes are anticipated to climb around 21% y-y, while Bajaj Auto's overall sales are estimated to gain around 12% to 570,000 units. Hero MotoCorp volumes are anticipated at 715,000 units, up 4%.
MHCV wholesales are estimated at 42,300 units, up 25% y-y, with retail sales at 39,300 units, up 41%. Tractor wholesales are anticipated to slide 21% due to a shift in festive dates and last year's high base.
Commodity pressure stays elevated as steel, copper and crude prices climb further. This "will further keep input cost pressure elevated and gain the risks for further price hikes by OEMs", Nomura stated, adding that CVs and 2Ws are better placed to pass on costs than PVs.
September 2W EV sales are estimated at around 205,500 units, up 87% y-y, with EV penetration "at an inflection point", Nomura stated.

Skyways Air Ser Consolidated June 2026 Net Sales at Rs 1,216.53 crore, up 93.1% Y-o-Y
BRICS boom: Luxury hotels sold out, suites touch Rs 5 lakh in Delhi

SBI AMC, HDFC AMC in focus: Kotak initiates ‘Buy’ on SBI, upgrades HDFC; downgrades ABSL
About The Author
