A second home for rent can drain cash even when the property looks profitable
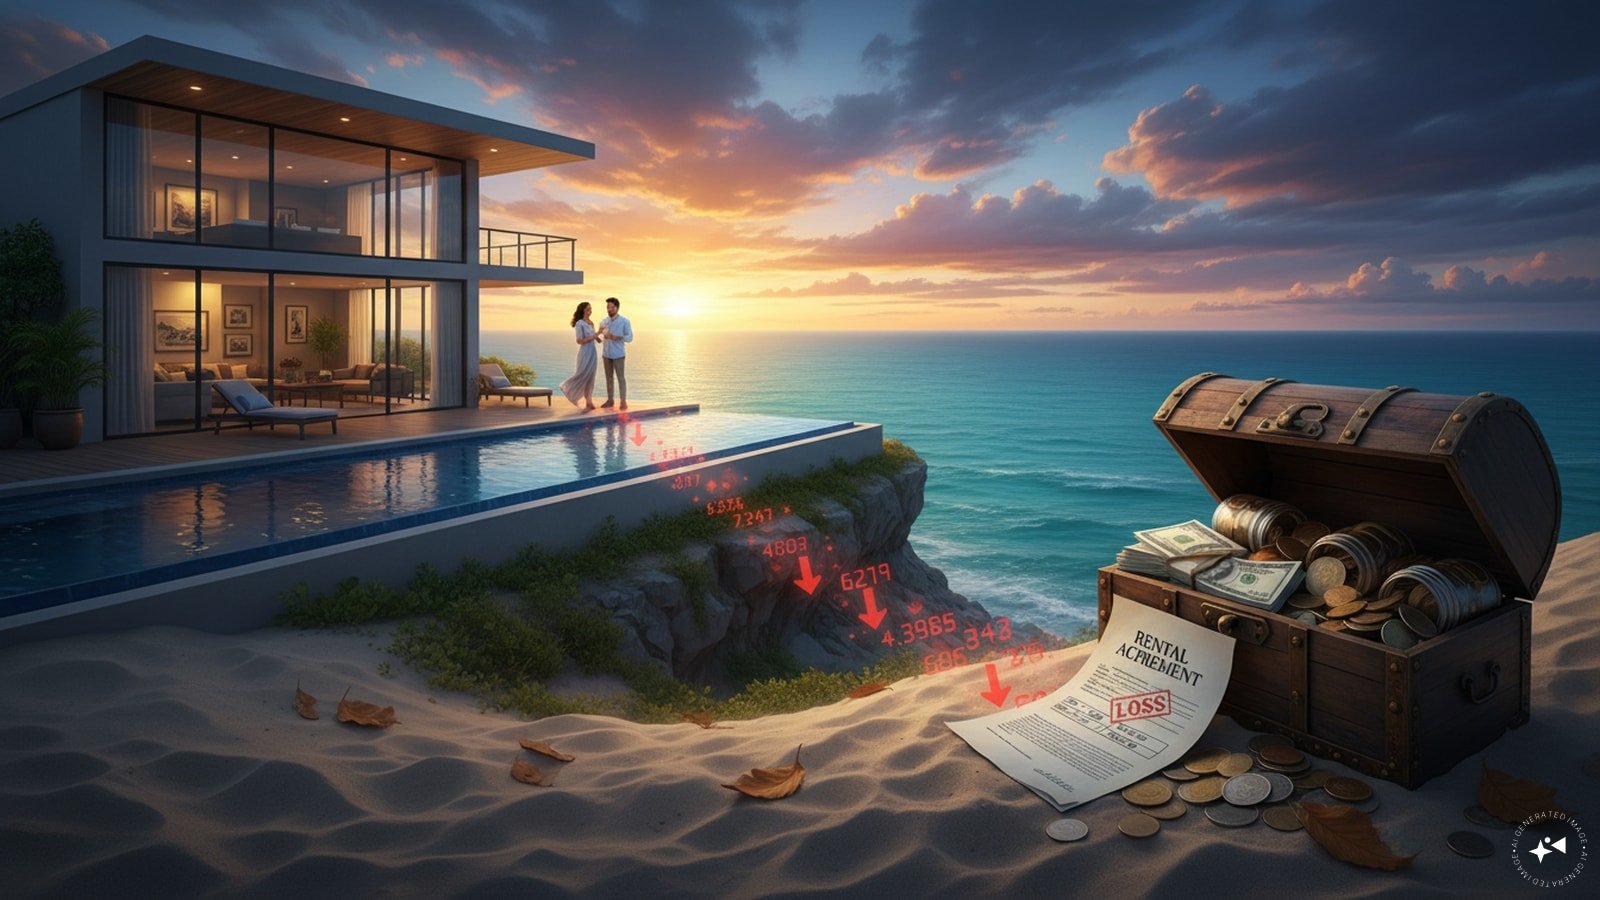
Reports coming in for today mention that Buying a second house with the hope of earning monthly rent can look like a straightforward wealth-building strategy. But the rent you receive is only one part of the calculation. Loan interest, maintenance, property tax, vacancy periods, brokerage and the cost of furnishing the house can significantly reduce the actual return.
Before signing the sale agreement, compare the annual rental income with the total amount invested and the financing cost. A property that offers a 4 to 5 percent gross rental yield may still produce negative monthly cash flow if a large portion of the purchase price is financed through a home loan.
Start with the rental yield, not the EMI
Suppose a flat costs Rs. 1 crore and can fetch Rs. 40,000 a month. The annual rent is Rs. 4.8 lakh, giving a gross rental yield of 4.8 percent.
That number may initially appear reasonable, but it does not account for expenses. If the property stays vacant for a month, annual rent falls to Rs. 4.4 lakh. Add society charges, repairs, property tax, insurance, brokerage for finding tenants and occasional furnishing costs, and the net yield can decline further.
Additionally compare this return with the property's location-specific price expansion prospects. Rental income alone should not be used to justify a high purchase price.
The loan can change the entire calculation
Consider the same Rs. 1 crore property bought with a Rs. 25 lakh down payment and a Rs. 75 lakh loan. At an illustrative 8.5 percent interest rate for 20 years, the EMI would be around Rs. 65,100 a month.
That means annual EMI outgo of roughly Rs. 7.81 lakh against potential rent of Rs. 4.8 lakh. Even before maintenance and other ownership costs, the rent does not cover the EMI.
Part of the EMI goes towards principal repayment and builds equity in the property, so the entire EMI should not be treated as a cost. Still, the investor needs enough monthly surplus to fund the gap without disturbing emergency savings or other financial goals.
Do not ignore the tax treatment
Rental income from a residential property is generally taxed under the head of income from house property. Under the current rules, municipal taxes actually paid by the owner can be deducted, followed by a standard deduction of 30 percent of the annual value.
For a let-out property, interest on borrowed capital used for the property is deductible while calculating house-property income. That stated, the treatment of any resulting loss depends on the tax regime. Under the new tax regime, such a house-property loss cannot be set off against income under other heads.
This makes the tax benefit of taking a large loan less useful than some buyers may assume.
A second property additionally locks up a sizeable amount of capital. Factor in stamp duty, registration, brokerage, interiors and the down payment before calculating returns. Check whether the locality has dependable tenant demand, how long similar homes stay vacant and what rent comparable properties actually command.
If the property needs a loan, stress-test the numbers by assuming a few months of vacancy and elevated maintenance costs. The investment should stay manageable even when the rent stops temporarily.
The right question is not simply, “How much rent will I get?” It is, “After all costs, taxes, loan payments and vacancy, what return will this property actually generate on my money?” That calculation can make the decision far clearer.
Mirae Asset launches Life Cycle Fund 2056: How does a 30-year mutual fund change your money over time?

Netweb Tech, E2E Networks, Black Box fall up to 7% as AI slowdown fears hit Indian stocks
Beyond FY31: Centre may need 1-2 years more to meet 50% debt-to-GDP target
About The Author
