Life insurance nominee or legal heir: Who gets the money after death?
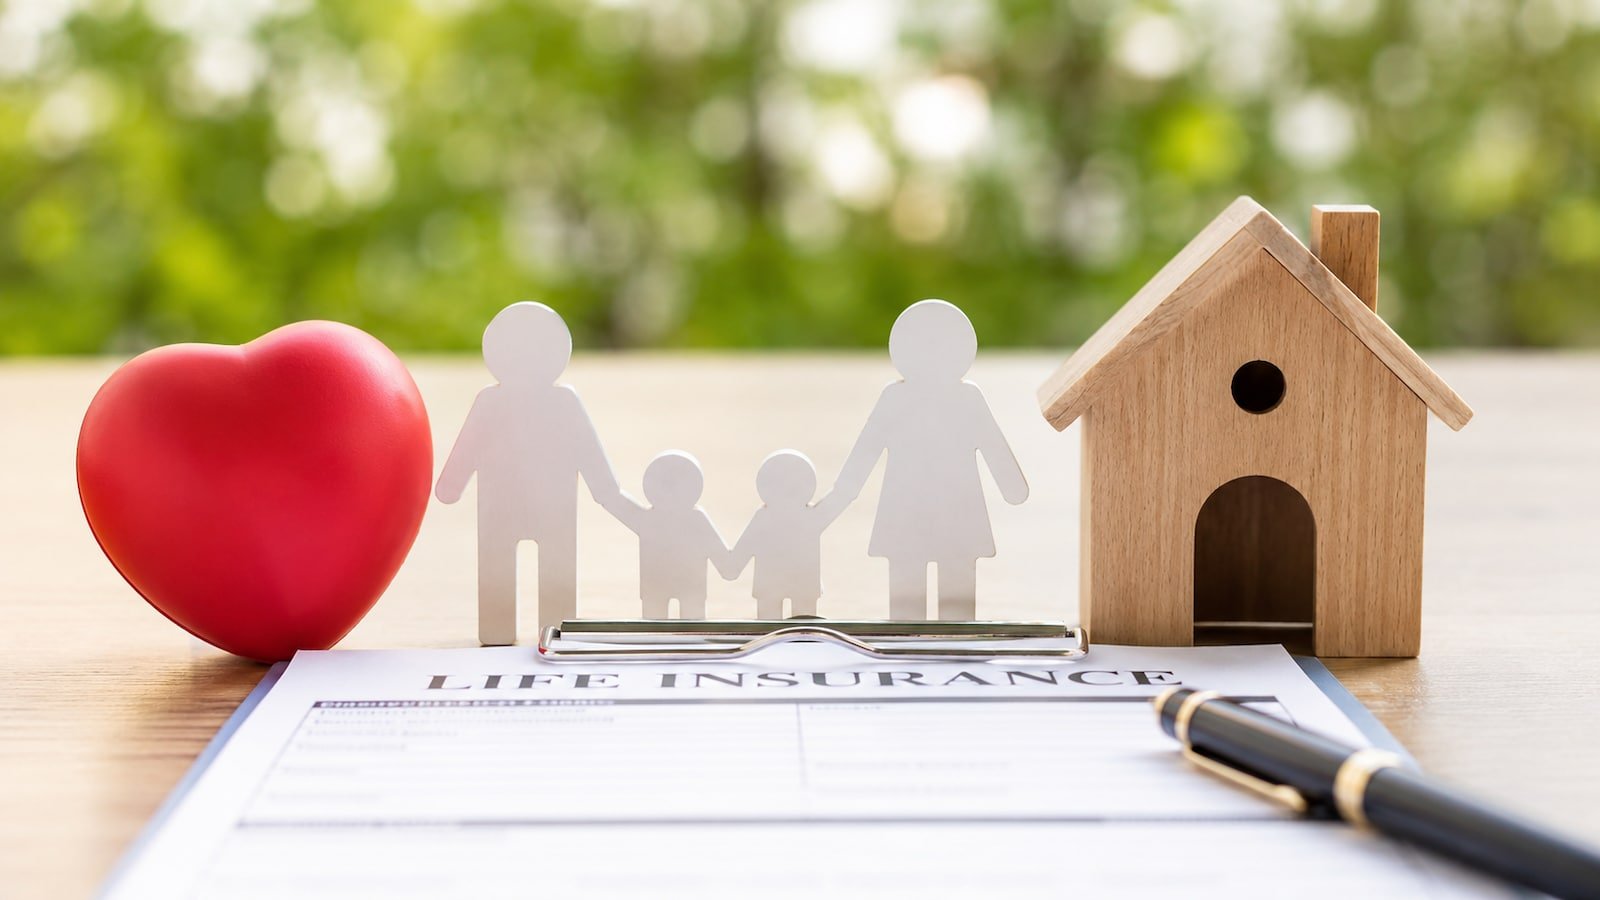
According to fresh market updates, When a life insurance policyholder dies, the first question for the family is often simple: who will get the insurance money? The answer can become less straightforward when the person named as nominee is different from the policyholder's legal heirs.
Under Section 39 of the Insurance Act, 1938, a policyholder can nominate one or more people to receive the policy money after their death. The nomination can be changed during the policy term, subject to the prescribed process. But being the nominee and being a legal heir are two different legal positions.
A nominee is not simply another name for a legal heir
The nominee's role is primarily connected with receiving the insurance money from the insurer. The law allows a policyholder to nominate a person when taking the policy or later, and the nomination can be changed or cancelled before maturity.
This distinction matters because inheritance is governed by the succession law applicable to the deceased. A legal heir's rights do not automatically disappear merely because someone else has been named as nominee.
For example, if a person names a sibling as nominee but leaves behind a spouse and children, the family cannot assume that the nomination alone settles all questions around who is ultimately entitled to the money.
Spouse, children and parents get special treatment
Section 39 gives a specific status to nominations made in favour of the policyholder's parents, spouse, children, or spouse and children. These nominees are described in the law as "beneficially entitled" to the policy amount, subject to the conditions in the section.
That makes the position different from the older understanding that a nominee was merely a person who collected money on behalf of the estate.
That stated, the interaction between nomination and succession law has additionally been considered by the Supreme Court. In the case Shakti Yezdani v. Jayanand Jayant Salgaonkar, the Court reiterated the broader principle that nomination does not
by itself create a new mode of succession or automatically remove the rights of legal heirs.
What happens when family members disagree?
A straightforward claim may be settled by the insurer after the required documents are submitted. Problems can arise when there are competing claims, an outdated nomination, a previous marriage, multiple heirs or questions around a will.
The insurer's payment process and the family's ultimate inheritance rights are as a result not necessarily the same offering. In a disputed case, the applicable succession law and court orders can become important.
There is another detail policyholders should not overlook. A nomination can be changed during the policy term, but the change needs to be properly communicated and registered with the insurer. Simply deciding privately that another family member should receive the money is not enough.
Keep the policy, nomination and will updated
The safest approach is to review nominations after major family changes such as marriage, divorce, the birth of a child or the death of a nominee. The policy records should reflect the person's current intentions.
A will can additionally form part of succession planning, particularly when the family has several assets or a complicated family structure. But nomination and the will should be considered together with the succession law that applies to the individual.
For policyholders, the practical takeaway is that naming a nominee is important, but it should not be treated as a complete estate-planning exercise. Keeping the nominee details current and understanding who the legal heirs are can help prevent an insurance claim from becoming a family inheritance dispute.
Buy Solar Industries India; target of Rs 23,124: Prabhudas Lilladher
Tax audit deadline September 30: Professionals seek October 31 extension; what taxpayers should do
Subscribe for Orient Cables India Ltd IPO; Ajcon Global
About The Author
