Buying a resale flat with a home loan still running? Know how the deal is closed
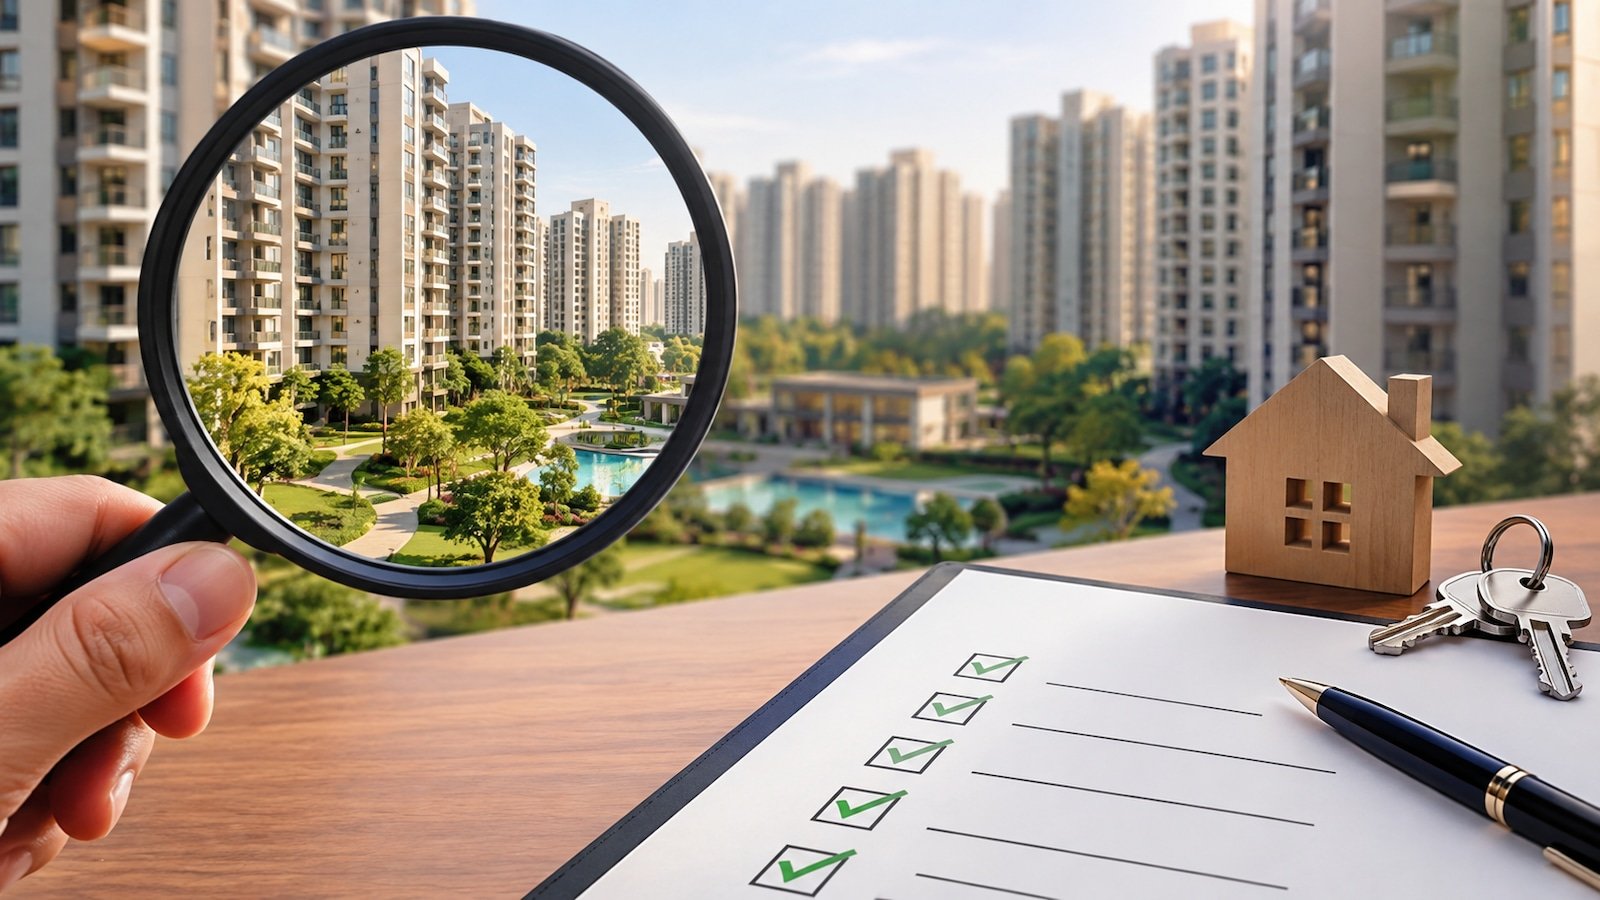
Reports coming in for today mention that A resale flat can be bought even when the seller is still repaying a home loan. The catch is that the property is usually mortgaged to the seller’s lender, which holds the original property documents and has a charge over the house. The loan as a result has to be settled as part of the transaction before the property can be transferred with a clear title.
Start with the seller’s outstanding loan
The first thing a buyer should ask for is the seller’s latest loan statement or foreclosure statement showing the exact amount required to close the loan. This figure matters because the outstanding loan may be softer than the agreed sale price.
For example, if a flat is being sold for Rs. 80 lakh and the seller’s outstanding home loan is Rs. 35 lakh, the transaction needs to ensure that Rs. 35 lakh reaches the lender so that its charge can be released. The remaining Rs. 45 lakh goes to the seller, subject to the agreed payment terms and applicable costs.
The buyer should not simply pay the full Rs. 80 lakh to the seller and expect the seller to settle the bank later. The payment structure should be agreed in writing, preferably with the lenders and legal advisers involved.
How the bank-to-bank transaction works
If the buyer is additionally taking a home loan, the process can be coordinated between the two lenders. The buyer’s lender may pay the seller’s lender directly towards closure of the existing loan, with the balance paid to the seller according to the sale agreement.
In some transactions, the buyer and seller use the same lender, which can simplify coordination. If they use different lenders, additional documentation or a tripartite arrangement may be required, depending on the banks’ procedures.
Once the seller’s loan is fully cleared, the existing lender should release the original property documents and provide the relevant loan-closure or no-dues documentation.
Documents the buyer should check
The outstanding loan is only one part of the due diligence. The buyer should have the property title and ownership documents checked by a property lawyer. The sale deed, previous title documents, approved plans, possession or occupancy documents, property tax records and society papers should be examined as applicable.
An encumbrance check is additionally useful to identify registered claims or charges. The buyer should specifically ask how and when the seller’s lender will release its mortgage and when the original documents will become available.
The sale agreement should clearly state who pays which amount, how the existing loan will be closed, the deadline for obtaining the lender’s release documents and what happens if the loan closure is delayed. Do not rush the final payment
The safest approach is to link payments to clearly documented milestones rather than relying on verbal assurances. The buyer should additionally avoid taking possession or completing registration without understanding the status of the lender’s charge and the documents needed for transfer.
Once the old loan is closed and the lender’s claim is released, the property can proceed through registration and other transfer formalities. The buyer’s new lender, if any, can then create its own security interest over the flat.
A seller having an outstanding home loan is not automatically a reason to walk away from a resale flat. What matters is whether the loan closure, document release and ownership transfer are structured properly before the money changes hands.
Persistent Systems acquires additional 61 pc stake in Germany’s Nagarro

Associated Cera Standalone June 2026 Net Sales at Rs 9.06 crore, down 29.25% Y-o-Y
Indian copper producers seek tax cut to navigate record rally
About The Author
