Treasury can’t suppress US long-term yields for long, says Howard Marks
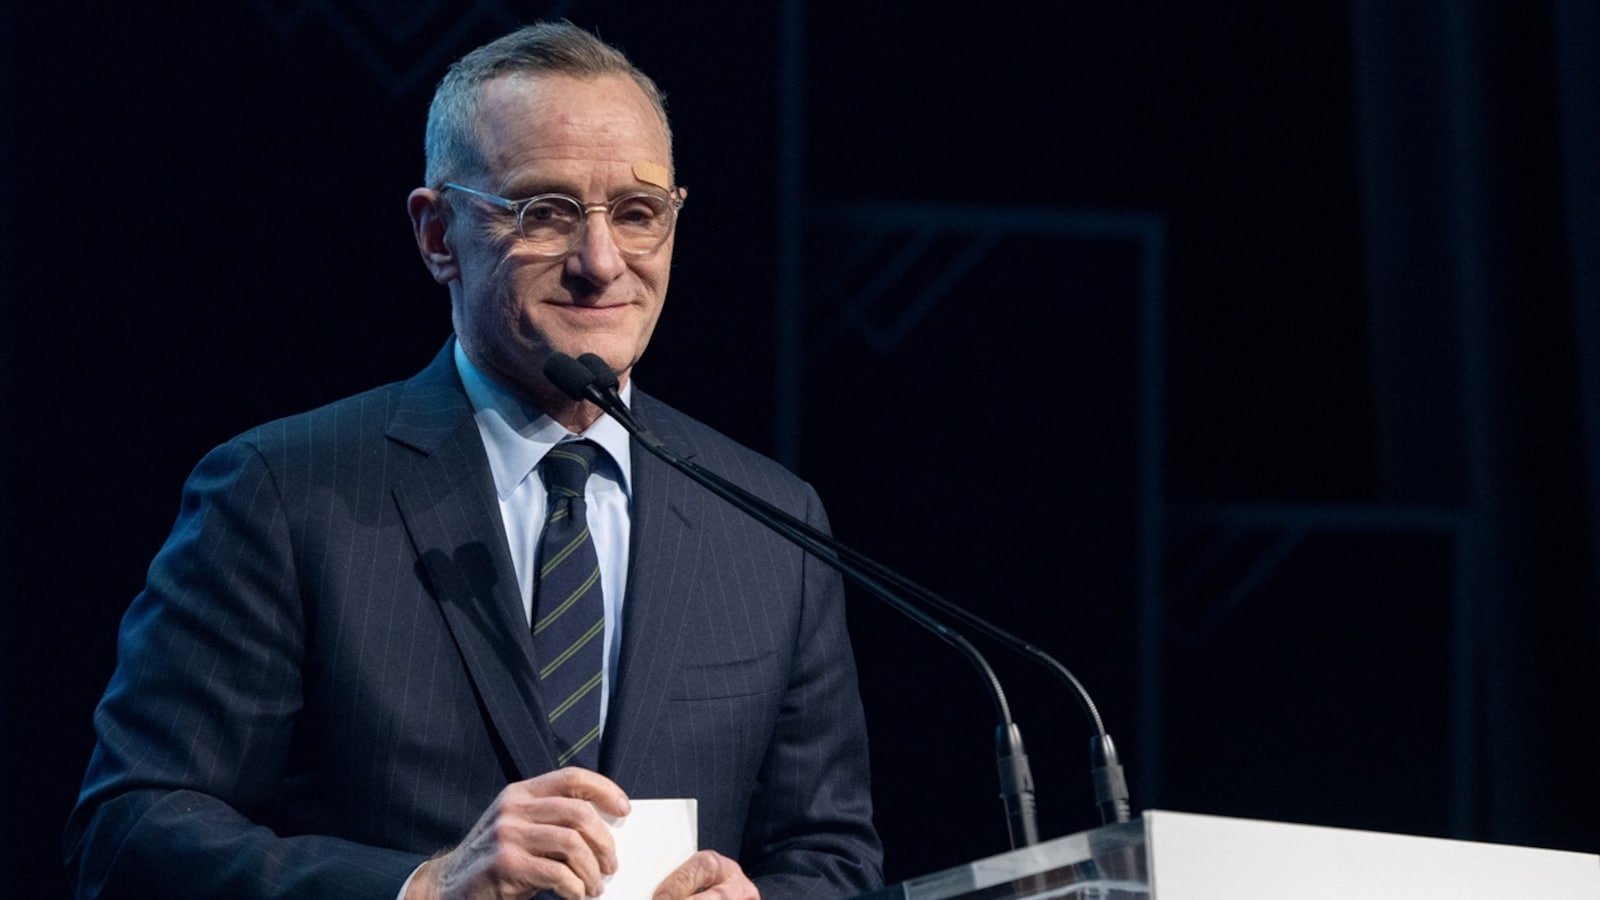
Fresh updates from the financial markets indicate that Attempts by the US government to propel down long-term Treasury yields may offer temporary relief, but are unlikely to address the economic forces driving borrowing costs elevated, according to veteran investor Howard Marks.
In his latest memo, “Shall We Repeal the Laws of Economics – Part III”, published by Oaktree Capital Management on September 22, Marks argues that policymakers cannot sustainably override market forces by buying bonds and attempting to influence prices.
His comments come after the US Treasury stepped up its purchases of longer-dated Treasuries. The Treasury had initially increased the maximum size of its long-dated buybacks from $2 billion per operation to $4 billion in August, before later announcing a maximum of $6 billion. Long-term yields initially declined after the announcement but subsequently moved elevated.
Marks stated the intervention amounted to an attempt to improve the interest-rate picture “cosmetically”, rather than address the underlying reasons for elevated yields.
“The goal shouldn’t be to get interest rates down. It should be to respond to the factors pushing rates up,” Marks wrote.
The The US central bank directly controls the federal funds rate, which influences short-term borrowing costs, but does not set the yield on 10- or 30-year Treasury bonds. Those yields are determined in the market and reflect market participants’ expectations for inflation, expansion, fiscal policy and the supply and demand for government debt.
Marks argues that several of those forces are at present working in the direction of elevated long-term yields.
One is inflation. Marks pointed to PCE inflation of 3.7% in July, above the The US central bank’s 2% long-term target, arguing that market participants buying long-duration bonds need compensation for the risk that inflation will erode the purchasing power of their future returns.
Another is the US fiscal deficit. Marks estimates the deficit at around 6% of GROSS DOMESTIC PRODUCT and notes that net interest outlays are projected to exceed $1 trillion this year.
The Treasury additionally faces substantial refinancing requirements, alongside new borrowing to fund the deficit. Marks estimates that net new issuance could be around $2 trillion, adding to the supply of debt that market participants have to absorb.
At the same time, he points to the enormous capital requirements associated with the artificial intelligence buildout. Citing McKinsey, Marks notes that more than $5 trillion could be spent globally through 2030 on data centres directly related to AI.
“An gain in demand for something causes its price to climb,” Marks wrote, arguing that stronger demand for capital from both the government and private sector could put upward pressure on the price of money – interest rates.
This is why Marks believes bond purchases alone cannot permanently reverse the direction of long-term yields. “If the 30-year must trade at 5.5% to clear, that isn’t a crisis. It is an invoice,” he quoted investor Stanley Druckenmiller as saying.
Marks additionally questioned whether shortening the maturity of government debt through Treasury buybacks would fundamentally improve the fiscal picture. Buybacks of long-term bonds can be financed through the Treasury’s cash resources, with those resources ultimately replenished through additional issuance. If the government replaces longer-dated issuance with more Treasury bills, the overall debt burden does not necessarily change, while refinancing requirements become more frequent.
For Marks, the more fundamental offering is as a result fiscal policy. He argues that the US would need to slow the expansion of government spending relative to GDP, gain revenues and raise productivity to bring deficits and debt dynamics under greater control.
The implication for market participants is not necessarily that they should abandon US equities. Marks explicitly distinguishes between the fiscal problems facing the US government and the underlying resilience of American firms.
“The problem we face isn’t a problem with the U.S. equity market or with U.S. firms,” he wrote. “It’s a problem with U.S. fiscal management, and ultimately a potential problem with the U.S. dollar.”
His broader warning is that policymakers can influence market prices for a period of time, but the underlying economics ultimately determine where those prices settle.

IT index falls for third day, LTM, HCLTech, lead losses; CLSA turns cautious amid weak macro fundamentals
Sun TV is preparing for potential SRH demerger, reports CNBC-Awaaz; shares rise up to 18%

Momentum Stocks: Transport Corp, Xelpmoc Design, Infinium Pharma rally up to 8% on strong momentum
About The Author
