A high CIBIL score does not guarantee your home loan
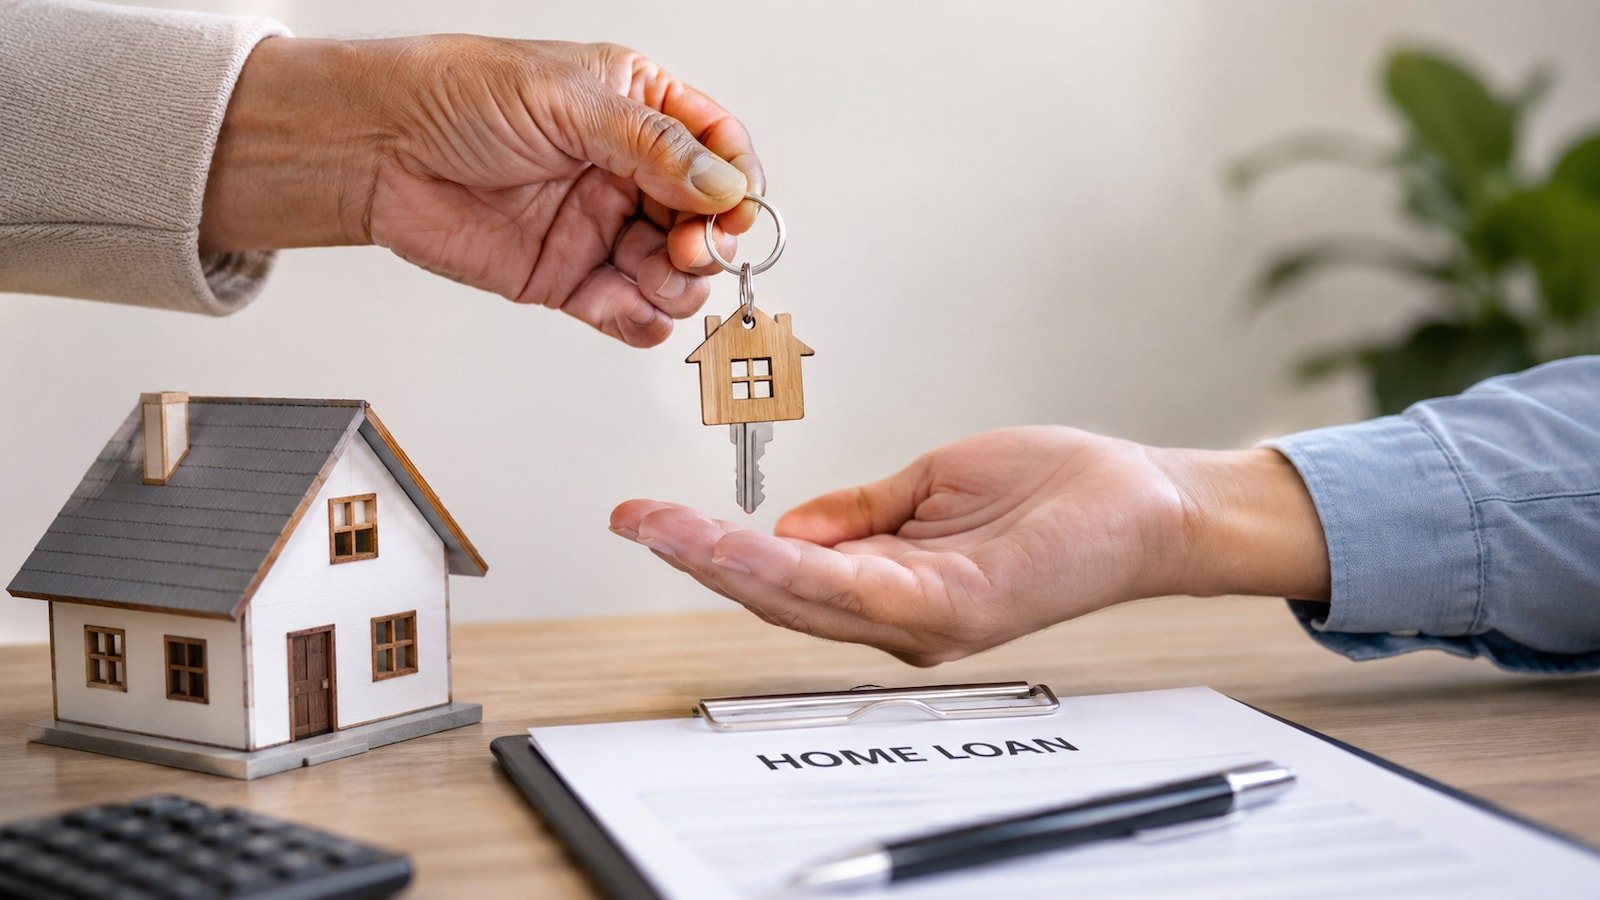
Reports coming in for today mention that A high CIBIL score can open the door to a home loan. It does not guarantee that the bank will let you walk through it.
Many borrowers assume that a score of 750 or above means approval is almost certain. In reality, lenders look at income, existing EMIs, age, employment or business stability, the property and the amount being borrowed. A firm credit history is only one part of the assessment.
Take a borrower earning Rs.1 lakh a month with a CIBIL score of 780. If they already pay Rs.45,000 towards a car loan, personal loan and credit cards, the bank may be wary around adding a large home-loan EMI. The score reveals a history of repaying credit, but it does not tell the lender whether the borrower can comfortably take on another long-term liability.
Existing debt is as a result one of the first things to check before applying. Banks generally assess the borrower’s set obligations against income while deciding repayment capacity. Even if the proposed EMI looks affordable on paper, several running loans can reduce the amount a lender is willing to sanction.
Income stability can matter too. A salaried applicant with regular income may have a simpler assessment than someone whose earnings vary from month to month. Self-employed applicants may be asked for income-tax returns, financial statements and bank records so the lender can understand the consistency of their earnings. A recent job change, a short employment history or irregular business income can additionally affect the assessment, depending on the lender’s rules.
Then comes the property. Getting a loan is not simply around getting the borrower approved. The bank additionally needs to be satisfied that the house or flat offered as security is legally and technically acceptable. Problems with title documents, approvals, construction or valuation can delay or derail a loan even when the applicant has an excellent credit score.
The loan amount can additionally create a hurdle. RBI rules place limits on the loan-to-value ratio, or LTV, which is the percentage of the property’s value that can be financed. For individual housing loans, the applicable ceiling can be 90 percent for loans up to Rs.20 lakh, 80 percent for loans above Rs.20 lakh and up to Rs.75 lakh, and 75 percent for loans above Rs.75 lakh. This means a borrower may need to arrange a larger down payment as the property price rises.
Suppose a flat costs Rs.1 crore. If the applicable LTV ceiling is 75 percent, the maximum loan under that limit would be Rs.75 lakh. The buyer would have to
arrange the remaining Rs.25 lakh from their own funds, apart from costs such as stamp duty and registration, which banks generally do not include in the property value for LTV purposes.
Age additionally affects eligibility because a home loan can run for decades. A lender may shorten the tenure for an older applicant, increasing the EMI, or sanction a smaller amount if the repayment period becomes too short.
Credit history additionally needs a closer look beyond the headline score. Recent loan applications, missed payments, high credit-card utilisation or discrepancies in the credit report can raise questions. Checking the report before applying gives borrowers a chance to correct errors and understand their outstanding obligations.
A good credit score can strengthen a home-loan application and may help borrowers access better pricing. But approval still depends on the lender’s assessment of repayment capacity, the property and the overall risk of the application.
For someone planning to buy a house, the sensible preparation is as a result broader than simply chasing a elevated score. Check existing EMIs, income documents, available down payment and property papers before submitting applications. A clean credit report helps, but a bank ultimately wants to see that the proposed loan can be repaid comfortably over the years.
Tamil Nadu: Over 20 passengers feared trapped after bus falls into river in Tenkasi
Mirae Asset launches Life Cycle Fund 2056: How does a 30-year mutual fund change your money over time?
Buy Yatharth Hospitals; target of Rs 1350: Choice Institutional Equities
About The Author
