HAL stock rises as Citi, Goldman Sachs retain Buy on improving execution; check target prices, upside
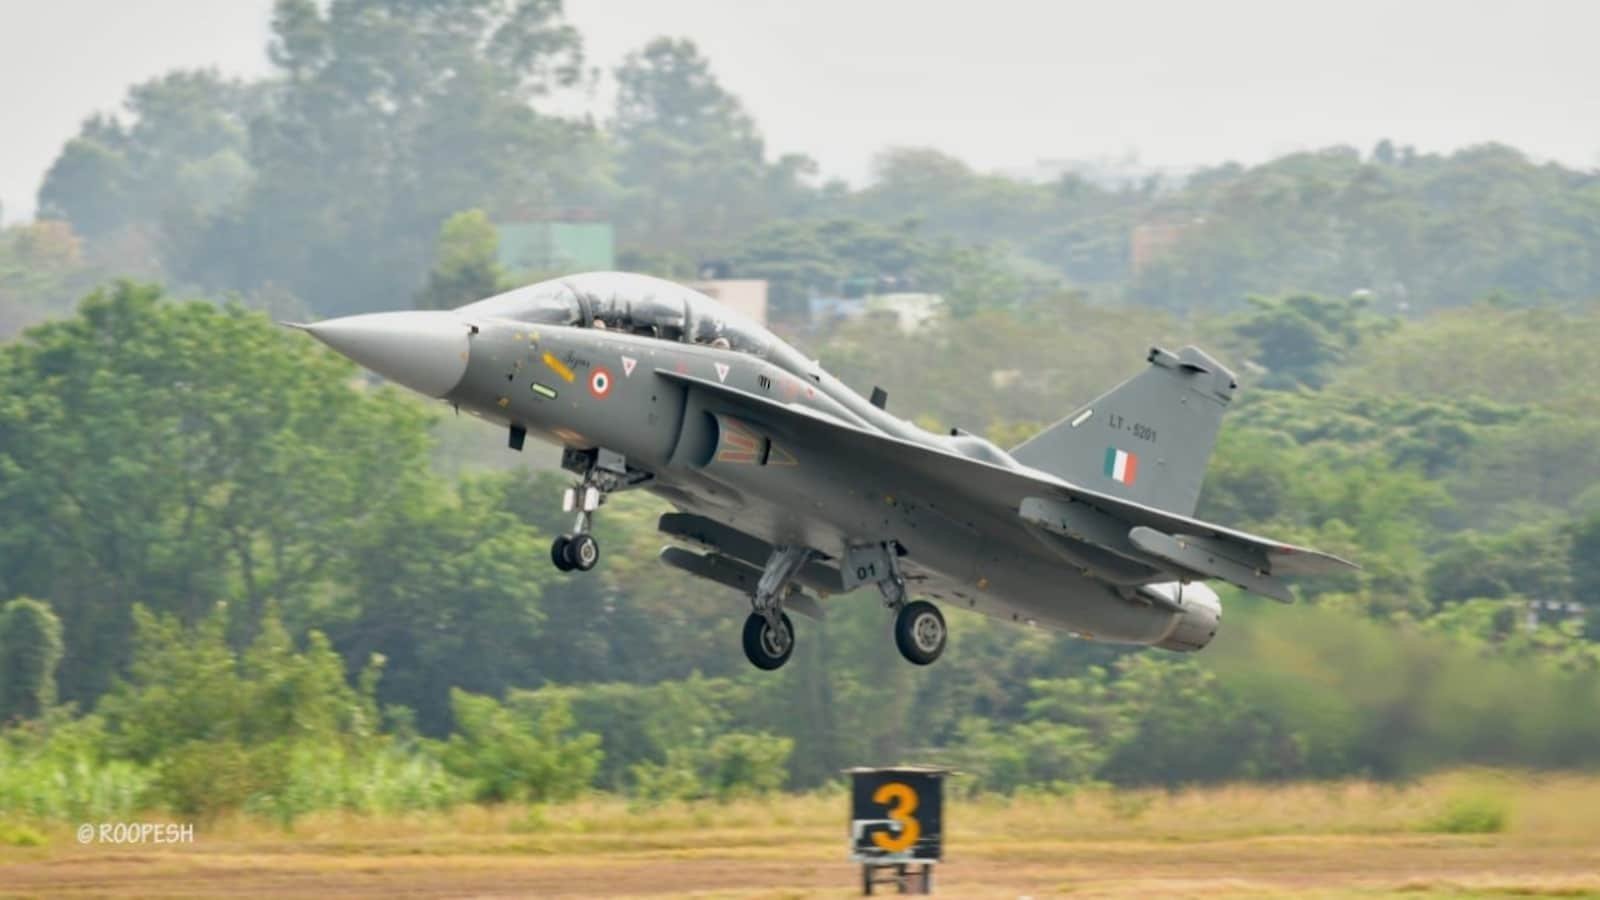
According to fresh market updates, Hindustan Aeronautics Ltd (HAL) shares advanced more than 1 percent in early session on Monday after Citi and Goldman Sachs retained their 'Buy' calls on the defence PSU, citing improving execution across fighter aircraft, trainers and helicopters as supply constraints ease and deliveries gather pace.
Citi maintained its 'Buy' rating on HAL with a target price of Rs 6,175 per share, implying an upside of nearly 29 percent from Friday's closing price of Rs 4,800.30. Goldman Sachs additionally retained its 'Buy' call with a target of Rs 5,870, indicating potential upside of around 22 percent.
HAL shares rose 1.33 percent to Rs 4,864 in early session on Monday. The stock had advanced 0.26 percent on Friday and is up 9.2 percent so far in 2026, significantly outperforming the Nifty 50, which has fallen 10.7 percent over the same period. HAL's market capitalisation stood at around Rs 3.21 lakh crore.
At 9:17 am, the Sensex was up 337 points, or 0.45 percent, at 74,631.98, while the Nifty was up 19 points, or 0.08 percent, at 23,365.25.
Share Markets Live Updates | Sensex, Nifty, GIFT Nifty Today
Citi sees execution improving across HAL platforms
Citi stated HAL's recent handovers demonstrated improving execution across multiple platforms. The firm handed over the final two LCA Tejas FOC twin-seat trainers and three HTT-40 basic trainers to the Indian Air Force, as well as four Dhruv Next Generation helicopters to Pawan Hans on September 18.
The brokerage stated execution of the Dhruv NG programme was progressing well and remained on schedule. HAL management is targeting delivery of 10 LCA Mk-1A aircraft by March 2027.
HAL has so far received 10 F404 engines, with further deliveries anticipated. Citi anticipates improving engine availability and progress on aircraft testing to reduce the remaining execution overhang surrounding the Mk-1A programme.
The start of Mk-1A deliveries has been a key monitorable for HAL. Citi had earlier stated that commencement of deliveries could ease the execution overhang and shift investor attention towards the firm's multi-year expansion visibility and large order backlog.
Goldman Sachs: Focus shifting to converting backlog into topline
Goldman Sachs similarly stated HAL's latest deliveries pointed to improving execution across fighter, trainer and helicopter platforms. The brokerage maintained its 'Buy' recommendation and Rs 5,870 target price.
The brokerage noted that GE has delivered another three F404 engines, supporting production of the LCA Mk-1A. As supply constraints ease and aircraft move through production and testing, Goldman Sachs anticipates the focus to increasingly shift towards HAL's ability to convert its large order backlog into topline.
The brokerage stated the improvement in deliveries was additionally aligned with the government's propel towards indigenous aerospace and defence manufacturing.
HAL's latest handovers included the final two twin-seat trainers under the original 40-aircraft LCA Mk-1 order. The firm will now increasingly turn its attention to the much larger Mk-1A programme, covering 180 aircraft ordered by the Indian Air Force.
The stock's near-term outlook, as a result, stays closely tied to the pace at which improving F404 engine supplies and completion of testing translate into actual LCA Mk-1A deliveries, while the recent HTT-40 and Dhruv NG handovers provide evidence of improving execution beyond the Tejas programme.
Sebi bans Omaxe, 5 others for violating minimum public shareholding norms
NSE shares to trade on its own bourse? Management weighs in
Moneycontrol Pro Weekender | Pomp and Circumstance, with a touch of Vertigo
About The Author
