UPI vs NEFT: Which payment method should you use for transactions above Rs 2,000?
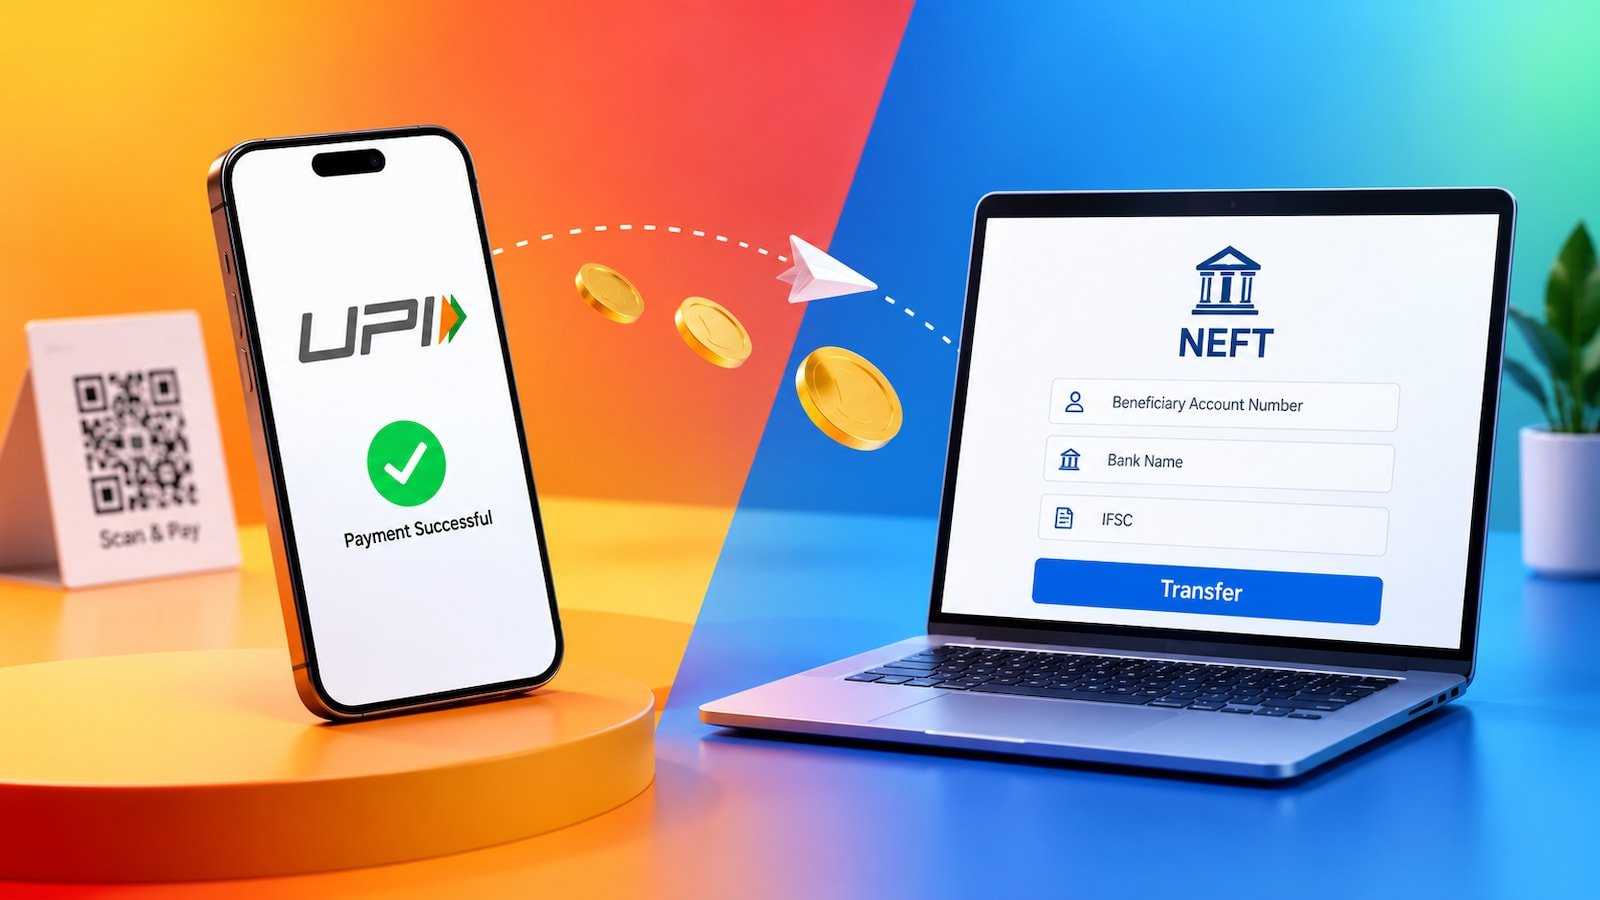
Fresh updates from the financial markets indicate that For high-value transactions, UPI and NEFT serve different purposes. UPI is generally faster and more convenient for everyday merchant and person-to-person (P2P) payments, while NEFT is designed for direct bank-to-bank transfers.
The government’s latest clarification, issued on Tuesday (Sept. 14), confirms that Rs 2,000 is not a UPI transaction limit and that exceeding it does not automatically trigger a fee.
Elevated-value payments at present stay free for P2P transactions, while any future MDR (Merchant Discount Rate) may apply to eligible merchant transactions.
Here’s how UPI compares with NEFT when choosing a payment method for elevated-value transactions.
UPI vs NEFT: What is the difference?
UPI is generally more convenient for everyday payments, including at shops and online merchants, where users can pay by scanning a QR code or using a mobile number. It can additionally be used to transfer money to individuals quickly, often without requiring the recipient's bank account number or IFSC code.
NEFT, or National Electronic Funds Transfer, transfers money directly from one bank account to another. It is commonly used for rent, utility bills, loan EMIs, salary payments and transfers to individuals.
Unlike UPI, NEFT requires details such as the beneficiary's account number, bank name, and IFSC for the first transaction. The details are automatically saved for any future transactions.
NEFT operates 24×7 throughout the year. The RBI does not prescribe a minimum or maximum amount for an individual NEFT transaction. That stated, transactions are processed in half-hourly cycles, unlike instant payments with UPI.
For online NEFT transactions initiated through the bank's website or mobile banking, banks do not charge savings-account customers. Branch-initiated NEFT transactions, that stated, may incur charges under the bank's applicable fee structure.
Here’s what banks charge for initiating NEFT transactions at branches.
(function(){function e(){window.addEventListener(`message`,function(e){if(e.data[`datawrapper-height`]!==void 0){var t=document.querySelectorAll(`iframe`);for(var n in e.data[`datawrapper-height`])for(var r=0,i;i=t[r];r++)if(i.contentWindow===e.source){var a=e.data[`datawrapper-height`][n]+`px`;i.style.height=a}}})}e()})();
UPI or NEFT: Which one should you choose?
For a shop, an e-commerce purchase, or an everyday merchant payment, UPI stays the more convenient option, including for payments above Rs 2,000. There is at present no automatic customer fee when the amount crosses the threshold.
NEFT can be a useful alternative when money needs to be transferred directly to a bank account, particularly for rent, large payments, loan repayments or transactions where the beneficiary's account details are available.

IHCL to open Gateway hotel in Siliguri; Bengal portfolio to touch 19 properties

Juniper Green shares rise 3%; JM Financial initiates ‘Buy’, sees 39% upside to Rs 371 target

DA Update: Central government employees’ body seeks early announcement of DA, DR instalment for July…
About The Author
