UPI payments above Rs 2,000 may attract charges. Can you split a Rs 10,000 payment into five transactions?
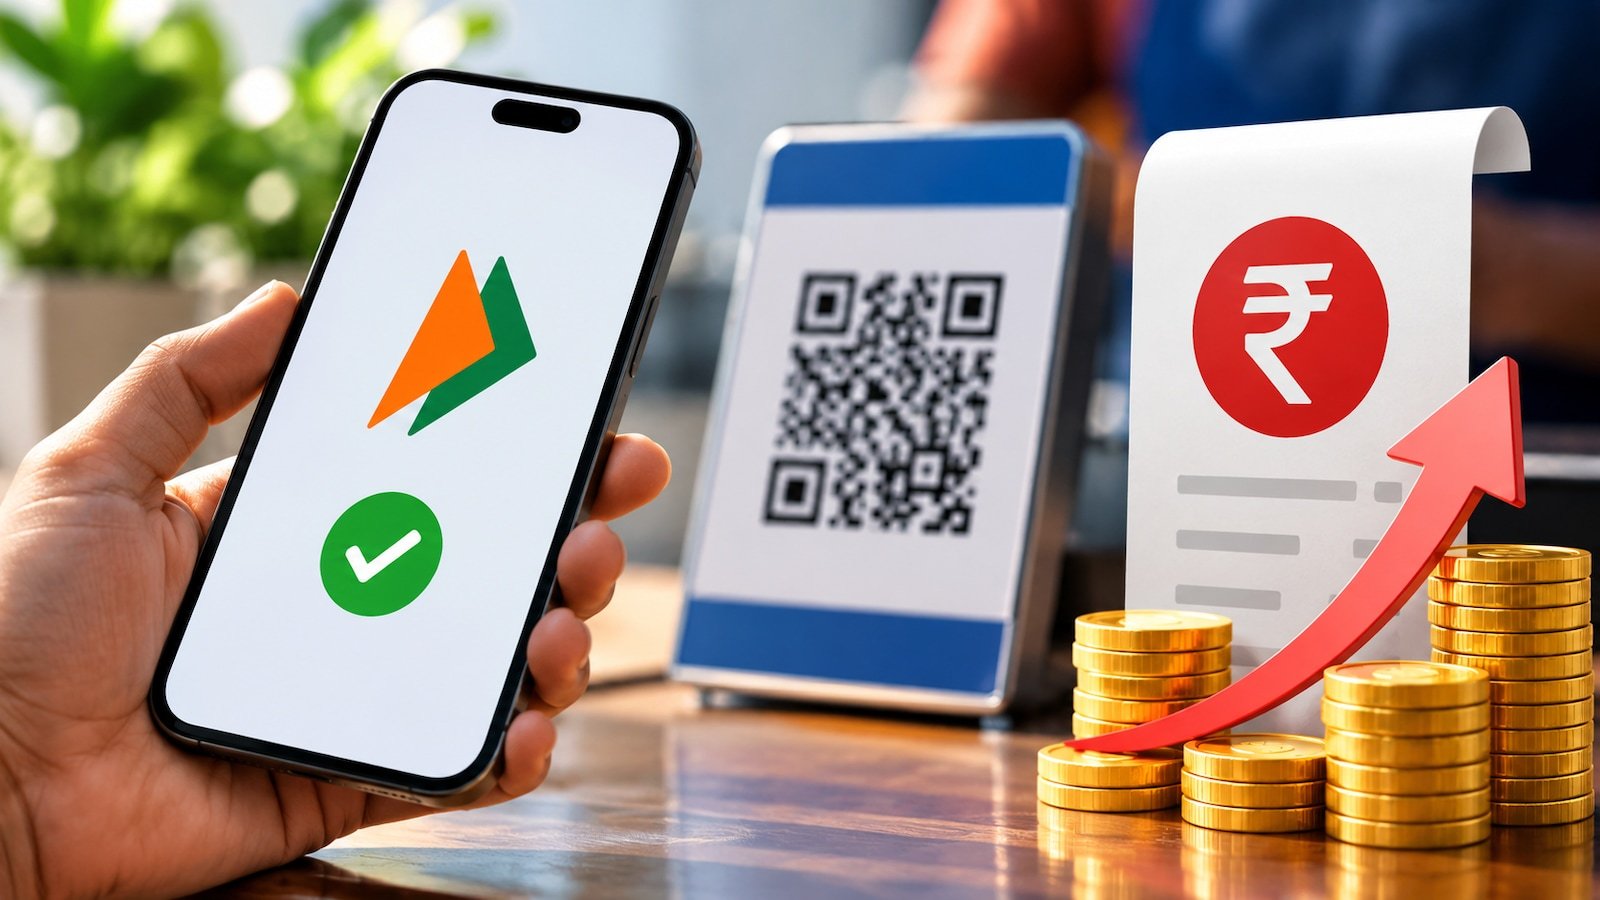
New business data points to the fact that UPI users may have to pay a charge on certain transactions above Rs 2,000, following the government’s latest notification. That stated, the exact charge is yet to be decided, and the proposed change will apply only to select merchant transactions, not peer-to-peer (P2P) transfers.
As per the Gazette notification, UPI transactions up to Rs 2,000 are exempt from any charges by banks or system providers. All RuPay debit card transactions are fully exempt.
"This essentially means that any UPI transaction above Rs 2,000 will now attract merchant discount rate or MDR charges. It is still to be decided what that charge could be, but industry estimates suggest it would be in the range of 30-45 bps. This will be finalised by the "UPI and Services Steering Committee" headed by the National Payments Corporation of India, or NPCI," stated Bikash Narayan Mishra, a former banker who writes on social and public policy issues.
That stated, Nirav Shah, Managing Director – BFSI of Equirus Capital, stated, "UPI payments above Rs 2,000 can continue normally. The notification does not introduce a customer charge; it only guarantees zero charges up to Rs 2,000. Any future MDR may apply to select merchant transactions and would generally be paid by the merchant. Person-to-person payments stay free."
Will customers have to pay the UPI charge?
The introduction of MDR does not necessarily mean that customers will directly bear the cost. Merchants and banks could choose to absorb the charge or pass some or all of it on to customers.
"Once NPCI announces the charge, merchants and banks will decide whether to absorb it or pass it (full or partially) to customers. Users may as a result pay a slightly elevated amount on transactions above Rs 2,000. As clarified by the government, this applies only to a limited set of merchant transactions and not to peer-to-peer (P2P) transfers," adds Mishra.
Can you split a Rs 10,000 payment into five transactions?
Splitting a large payment into multiple smaller UPI transactions could appear to be an obvious way to avoid a charge applicable above Rs 2,000. That stated, such a workaround may not always be available.
"Some merchants may offer workarounds, but NPCI, banks and payment providers will put safeguards in place to prevent them. Customers may not get such options on every transaction," stated Mishra.
Adding to it, Shah stated, "Splitting creates unnecessary inconvenience and may complicate reconciliation, cancellations or refunds for merchants."
Should you start carrying a debit card again?
If UPI transactions above Rs 2,000 eventually attract a customer-facing charge, users may look at debit cards as an alternative, particularly for larger purchases. That stated, the choice of card network matters.
A debit card may be useful as a backup for network problems, transaction limits or acceptance issues. The notification explicitly protects RuPay debit-card transactions from charges; this specific protection does not extend to cards on other networks.
"Only a RuPay card guarantees zero MDR charges. It works well for transactions in India. There is limited acceptance of RuPay cards outside India and even on some foreign e-commerce websites, which may limit your ability to make transactions as compared with a VISA- or MasterCard-powered card," stated Mishra.
For users making large merchant payments, as a result, the eventual MDR structure, and whether merchants or banks pass it on, will determine whether UPI stays the cheaper and more convenient option compared with debit cards.
India can grow at over 10%, Sitharaman says. Here’s what it will take

Neutral IDFC First Bank; target of Rs 1170: Motilal Oswal
FD or small savings schemes: 5 things to check before investing your money
About The Author
