Traders back simpler settlement as SEBI reviews closing auction
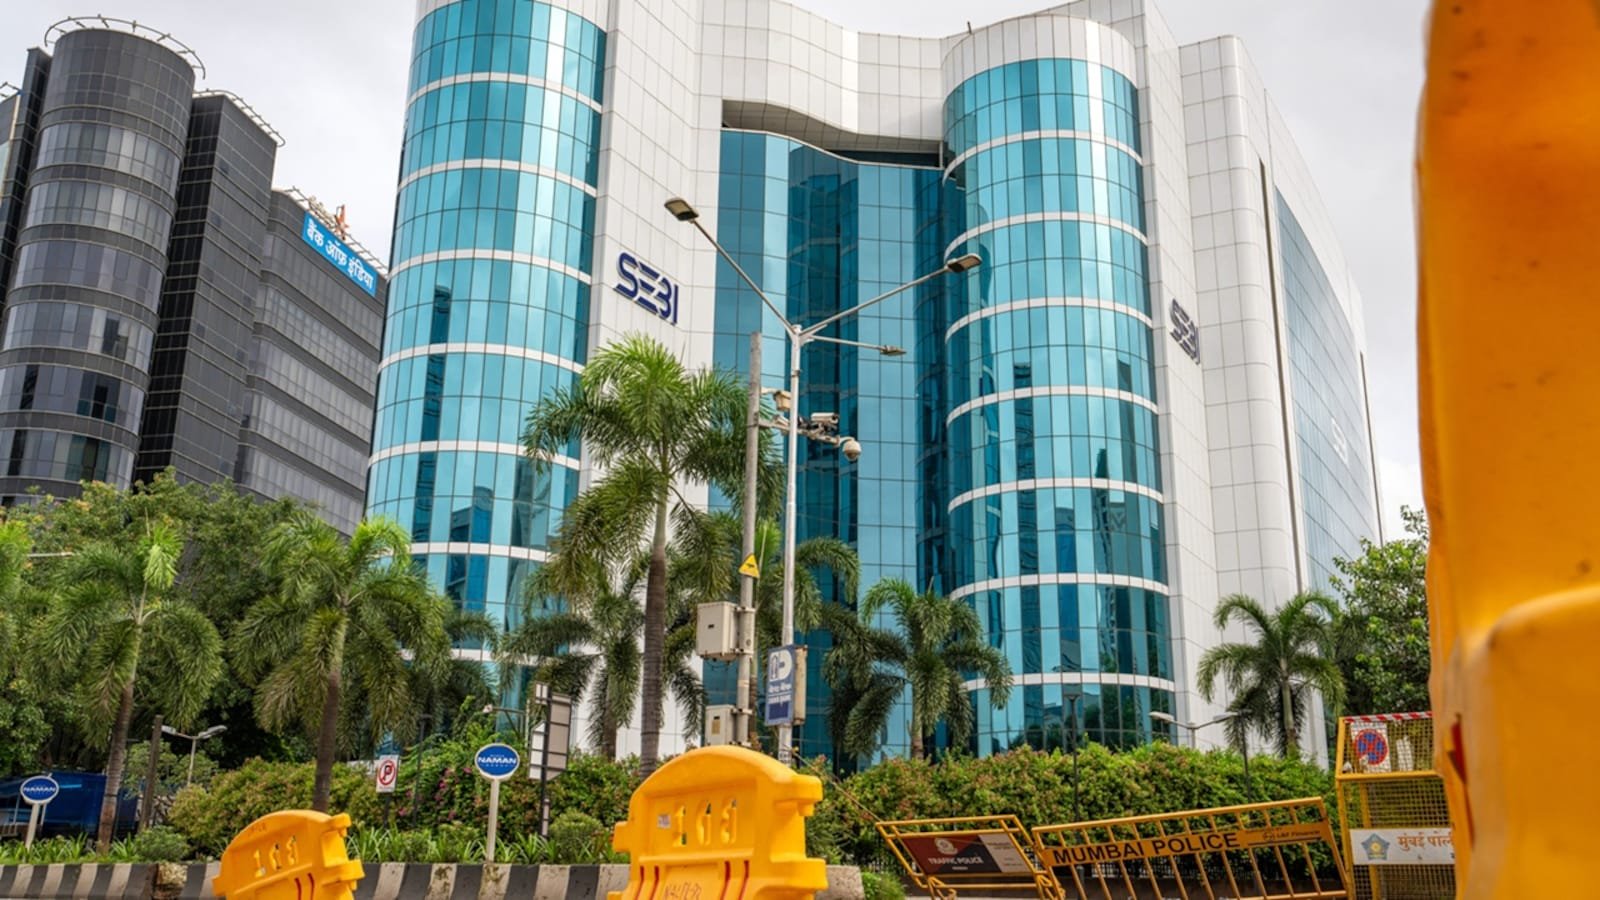
The latest market report highlights that Market experts and industry participants are mixed on their outlook regarding the regulator's consultation paper regarding the closing auction session (CAS). That stated, a larger group of experts prefer the simpler settlement option put forth by SEBI.
Since the implementation of CAS, there has been much uncertainty around derivatives, especially on expiry days. As a result, SEBI put out consultation paper that allows the regulator to make CAS more predictable without reversing the mechanism entirely with two proposed settlement methodology options.
Under Option 1, or the blended VWAP methodology, the settlement price for index and stock derivatives on expiry would be calculated using trades executed during the last 30 minutes of the normal Continuous Market session (CTS) as well as the new Closing Auction Session (CAS). The closing auction would become part of the price used to settle derivatives.
Under Option 2, or CTS VWAP, the CAS would have no role in determining the derivative settlement price. The price would be calculated only from trades executed during the last 30 minutes of the normal continuous market session.
What are traders at large saying?
Experts have mixed views on the proposed settlement methodologies. That stated, there is consensus that the current cash auction volumes need to improve before CAS is given a greater role in derivative settlement.
Vtrender's founder Shai Coelho stated a blended VWAP could work well in around a year, provided cash-auction volumes become meaningful. Until volumes improve, he favours option 2, the CTS VWAP, based on the 3:00-3:30 pm trading window. Coelho additionally argued that the switch to blended VWAP should be data-fuelled instead of happening automatically after 12 months.
Tradejini COO Trivesh D additionally prefers Option 2, saying the CTS VWAP is simpler and more established. A blended methodology, he stated, could add complexity by making the final settlement dependent on two different trading mechanisms.
He stated the 30-minute continuous-trading methodology is already well understood by traders at large, making SEBI’s proposal to retain it initially and reconsider blended VWAP after a year a reasonable approach.
That stated, IIFL Capital takes a somewhat different view, seeing Option 1 as the more likely long-term framework, with Option 2 serving as a temporary stabilisation period while traders at large adapt to CAS.
Under the blended methodology, CAS would form part of the settlement calculation, although its contribution would initially be limited by softer trading activity. IIFL anticipates CTS to stay the dominant contributor in the early stages.
"The objective is not to make the cash-market closing price and derivative settlement price identical. CAS would keep determine the cash-market closing price, while the derivative settlement price would be determined through the prescribed CTS/CAS methodology," stated IIFL.
SEBI proposes review of trade timing
SEBI has additionally sought market comments on the trading timings considering the proposed optimisation of the Closing Auction Session (CAS). It proposes reducing the CAS transition period from 5mins to 1min and the order-matching period from 5 minutes to 1 minute, while retaining an effective auction period of around 10 minutes.
Under Option 1, CAS would commence after 3:30 pm and derivatives would keep trade until 3:45 pm, while under Option 2, CAS would commence at 3:15 pm and derivatives would trade until 3:30 pm.
"On market timings, we would prefer the proposal where normal trading continues until 3:30 PM, followed by the CAS. The current structure can create confusion for participants around when normal trading effectively ends and when the auction process takes over," stated Tradejini.
"Allowing normal trading to continue up to 3:30 PM would create an unequivocal and more intuitive market structure."
Vtrender's Coelho agreed, saying, "On timing, the preference is for continuous trading to run normally through 3:00–3:30pm, with the CAS window sitting immediately after for price discovery, and index derivatives allowed to trade a little further out, toward 3:45."
So far, broker associations have been collecting responses from their members in order to give the regulator feedback.
India is building chip capacity ahead of demand: 360 ONE prefers EMS plays over pure fabs
Nifty settles under 200-WMA, marks longest losing streak in 25 years

Bank Nifty outperforms benchmarks, closes above 54,500; check top gainers: What lies ahead?
About The Author
