Apple iPhone 18 Pro on credit card: When rewards aren’t worth the debt
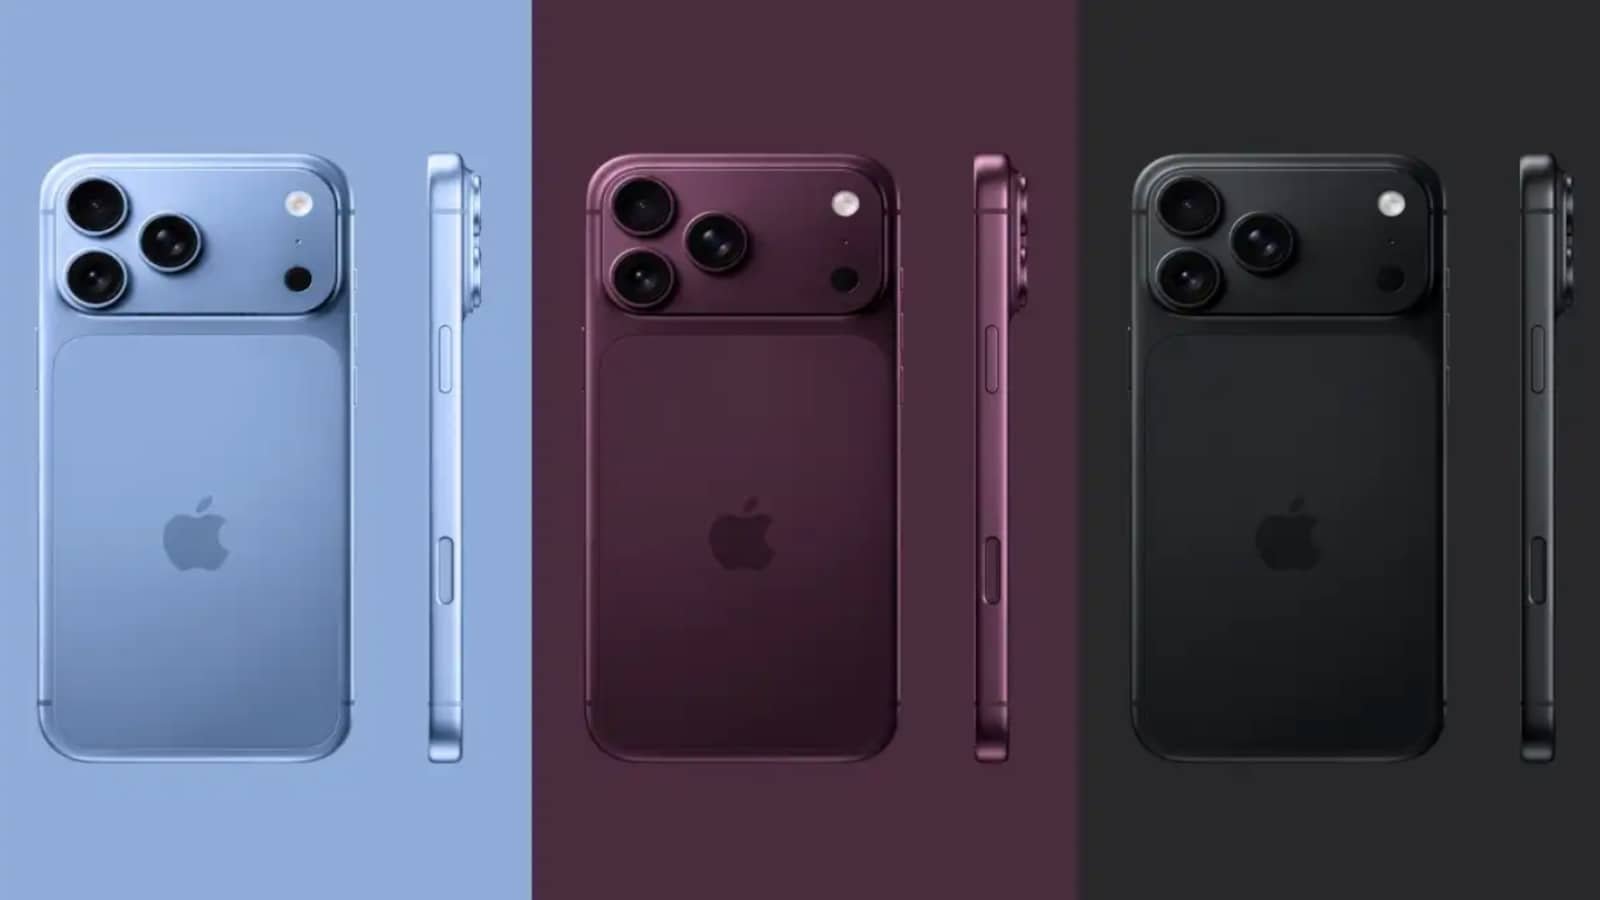
The latest market report highlights that The iPhone 18 Pro starts at Rs 1,64,900 in India, putting the latest Apple flagship firmly in the big-ticket discretionary category. Apple is offering eligible buyers options such as No Cost EMI and instant cashback of up to Rs 7,000 on selected iPhone models and eligible cards, including American Express, Axis Bank and ICICI Bank cards.
For a buyer who already has the money to pay the bill in full, using a credit card can make sense. The transaction can earn rewards or cashback, while the cardholder clears the entire outstanding amount before the due date. That stated, the problem starts when the reward becomes an excuse to carry the debt.
A Rs 1.65 lakh purchase can become expensive debt
Suppose a buyer puts the Rs 1.65 lakh iPhone 18 Pro on a regular credit card but cannot pay the full bill. The interest rate on credit cards varies by issuer and card, so the buyer should check the card's disclosed monthly and annual rate before making the purchase.
For instance, at an illustrative rate of 3.5 percent a month, finance charges on Rs 1.65 lakh would be around Rs 5,775 for one month alone, before considering applicable taxes and other charges. The actual cost will depend on the card's terms and how payments are made.
It is important to understand that a credit card may tell you what you can buy, but your income and savings determine what you can truly afford.
Don't confuse minimum payment with affordability
Credit-card statements typically give you the option of paying either the total amount due or a minimum amount due and carrying the remaining balance forward. As a result, you must know that paying only the minimum can stretch repayment over months or years, with consequential compounded interest. Moreover, the interest-free credit period is suspended when a previous balance stays outstanding.
In other words, paying the minimum amount may keep the account from immediately becoming overdue, but it does not make the purchase interest-free.
For a Rs 1.65 lakh phone, even a relatively small monthly minimum payment can create the illusion that the purchase fits comfortably into the budget, while the outstanding balance keeps attract finance charges. What around reward points?
This is where the psychology of credit-card spending can work against consumers. A buyer may think that he is getting reward points, so he might as well put the purchase on the credit card. But rewards are valuable only if the cardholder avoids the interest that comes with revolving the balance.
For instance, on a purchase of Rs 1.65 lakh, the reward you earn depends on the card’s reward rate. At 1 percent, you would earn around Rs 1,649 in rewards, while a 2 percent rate would fetch Rs 3,298. At 3 percent, the rewards would climb to Rs 4,947, and at a 5 percent rate, you could earn Rs 8,245. That stated, these rewards should be weighed against any interest or other charges if the credit-card bill is not paid in full.
While a 5 percent reward rate would produce Rs 8,245 on the purchase, a month of illustrative interest at 3.5 percent would already be around Rs 5,772. The balance could keep attract charges if it is not cleared.
Hence, don't spend Rs 1 to earn a few paise in rewards if the spending creates expensive revolving debt.
No cost EMI is a different calculation
A No Cost EMI should not automatically be treated as the same thing as carrying a normal credit-card balance. Generally, in the case of the No Cost EMI option, the interest payable on the EMI transaction is discounted from the transaction value, while the customer repays the principal and applicable interest to the eligible card issuer. Eligibility and terms depend on the card and transaction. But even a No Cost EMI needs a budget check. The buyer still has a monthly obligation, and the purchase consumes part of the card's available credit limit.
For instance, assuming there are no processing fees, GST on fees, or other charges, a Rs 1.65 lakh purchase translates into an EMI of Rs 55,000 for three months or Rs 27,500 for six months under a no-cost EMI plan.
According to Apple's terms and conditions, "No Cost EMI is not available to Business customers and cannot be combined with Apple Store for Education or Corporate Employee Purchase Plan pricing. Card eligibility is subject to terms and conditions between you and your card issuer."

Indian Bank plans life insurance, asset management foray; board approval next, CEO says
Europe’s rising regulatory burden could give India a cost advantage: Piyush Goyal

AI risks overstated, global pause unlikely; India should keep options open: Zoho’s Sridhar Vembu
About The Author
