Earning Rs 1 lakh per month? Here’s how much home loan EMI you can safely afford
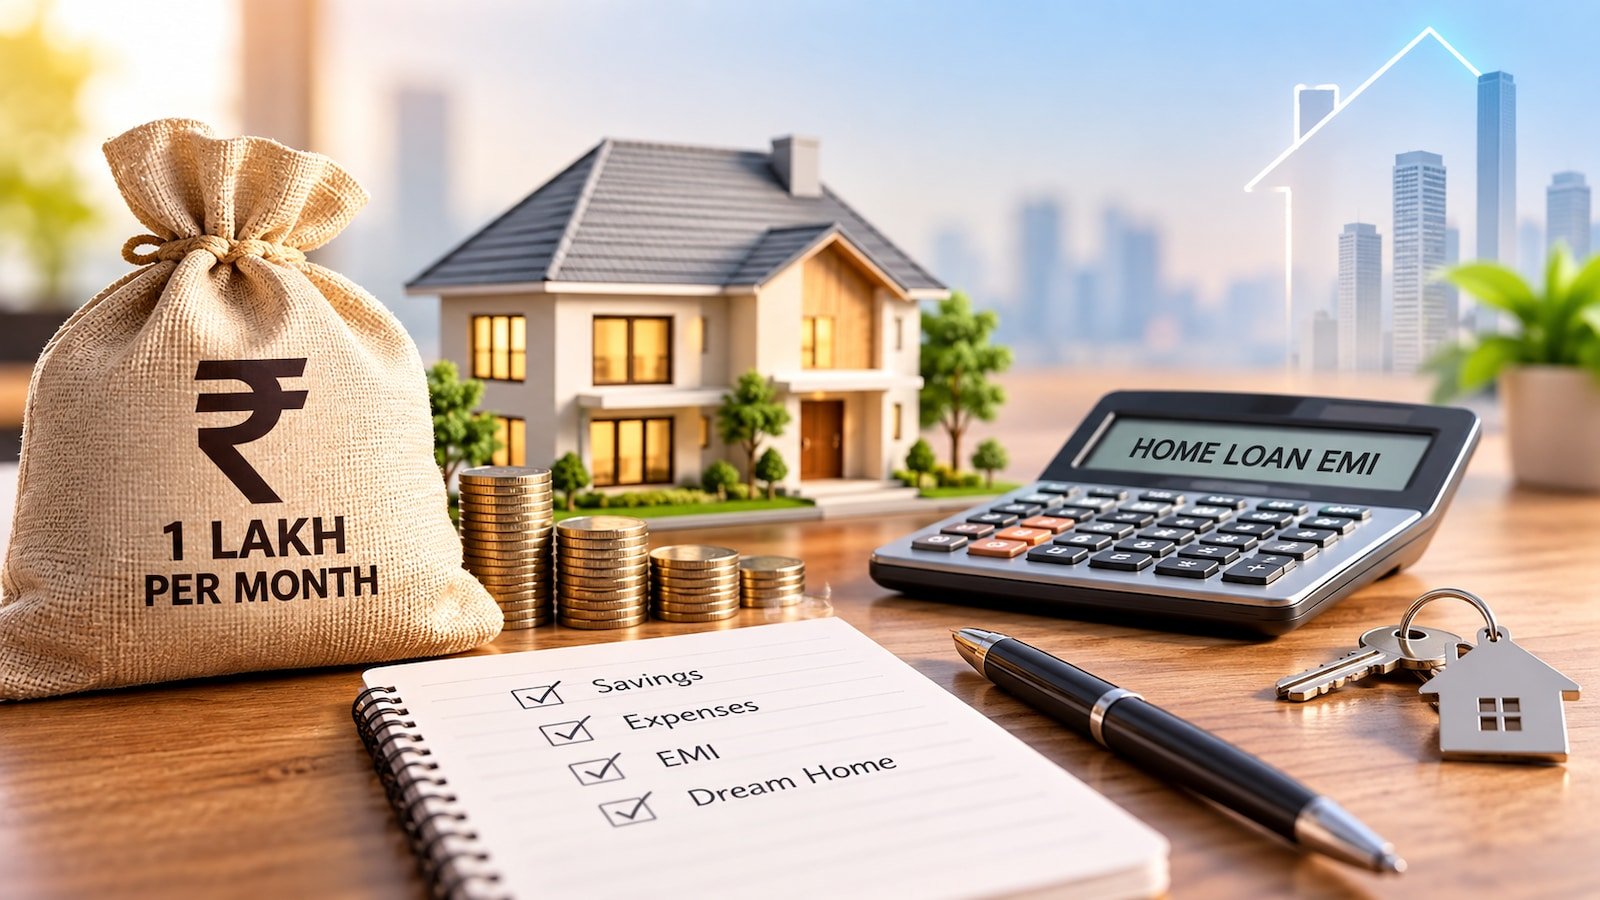
As per the latest business developments, Earning Rs 1 lakh per month can make homeownership look within reach, but the size of the salary alone does not determine whether you can comfortably afford a home loan. Existing expenses, EMIs, investments, emergency savings, down payment and future financial commitments all need to be factored in before taking on a long-term liability.
For a person with a Rs 1 lakh monthly take-home salary, financial experts suggest keeping the home-loan EMI well below the maximum amount a bank may approve. This can leave enough room for essential expenses, investments and unexpected financial shocks. How much EMI can you afford?
Keshav Mangla, GM- Business Development at Fortesia Realty, stated, “Ideally, if you have a monthly take-home salary of Rs 1 lakh, your EMI should not cross 30-40 percent of it. That is, it should be below Rs 30,000-40,000 per month.”
That stated, Mangla recommends an even more conservative approach. “A more preferable goal would be to keep it under 25-30 percent, which is Rs 25,000-30,000, so you'd still have enough scope for investments, savings and emergencies,” he stated.
While banks may approve an EMI taking up 50-55 percent of income, that does not necessarily mean the borrower can comfortably afford it.
“Banks can approve it up to 50-55 percent of income, but taking a elevated EMI limit makes very little room for any contingency and stress marks are bound to be high if income falls or expenses gain,” Mangla stated.
Harsh Soni, Founder at Nyvo Money, sets the suggested limit slightly elevated, but still below what banks may allow.
“Our view is to keep the home-loan EMI around 35 percent of monthly income. On a Rs 1 lakh salary, that means roughly Rs 35,000 a month. While a bank may approve an EMI of 40–50 percent, affordability is a different question from eligibility,” Soni stated.
At a Rs 35,000 EMI, Rs 65,000 would stay for living expenses and financial goals. “For example, Rs 43,000 could go toward essential and discretionary spending, while Rs 22,000 could continue toward savings and investments, including SIPs and an emergency fund,” he stated. Down payment and other costs
The EMI is only one part of the affordability calculation. A homebuyer additionally needs to set aside funds for the down payment and buying-related expenses while maintaining an emergency fund.
Mangla stated there are “Three things you need to save for before you even apply for the loan: down payment, buying costs and emergency fund.”
According to him, the down payment would usually be around 10 percent for properties up to Rs 30 lakh and 20 percent up to Rs 75 lakh, with the requirement increasing further for more expensive homes.
Buying costs such as stamp duty and registration charges can add another 5-8 percent of the property's value and are not included in the home loan, Mangla stated.
Don't ignore the emergency fund
Before taking a home loan, borrowers should ideally have an emergency fund covering 6 to 12 months of necessary expenses, including the EMI.
Mangla stated that if EMI and essential day-to-day expenses together amount to around Rs 60,000–Rs 70,000 a month, the emergency fund should be at least Rs 3.6 lakh to Rs 8.4 lakh.
For a Rs 50 lakh home, he estimates the requirement at approximately Rs 10 lakh for the down payment, Rs 2.5 lakh–Rs 4 lakh for buying costs, and Rs 3.6 lakh–Rs 4.2 lakh for an emergency fund, bringing the total upfront requirement to around Rs 16–Rs 18 lakh.
Soni additionally cautioned that a home loan should not derail other financial goals. “When budgets get tight, it's often the flexible goals – retirement SIPs, a child's education fund or emergency savings – that get pushed aside,” he stated.
He further noted that buyers must account for costs beyond the EMI, including “stamp duty, registration, interiors, maintenance and property tax.”
Ultimately, a Rs 1 lakh salary can backing a home loan, but only if the EMI, upfront costs and future commitments fit comfortably within the overall financial plan. “Buying a home shouldn't mean putting every other goal on hold,” Soni stated.
NACOF posts Rs 2,456 crore revenue in FY26, approves 12% dividend; plans overseas expansion

Paying only the minimum on your credit card? Here’s what it can really cost
West Bengal govt to unveil new industrial land policy ahead of Durga Puja: CM Suvendu Adhikari
About The Author
