NRI credit cards: What to check before getting an Indian credit card
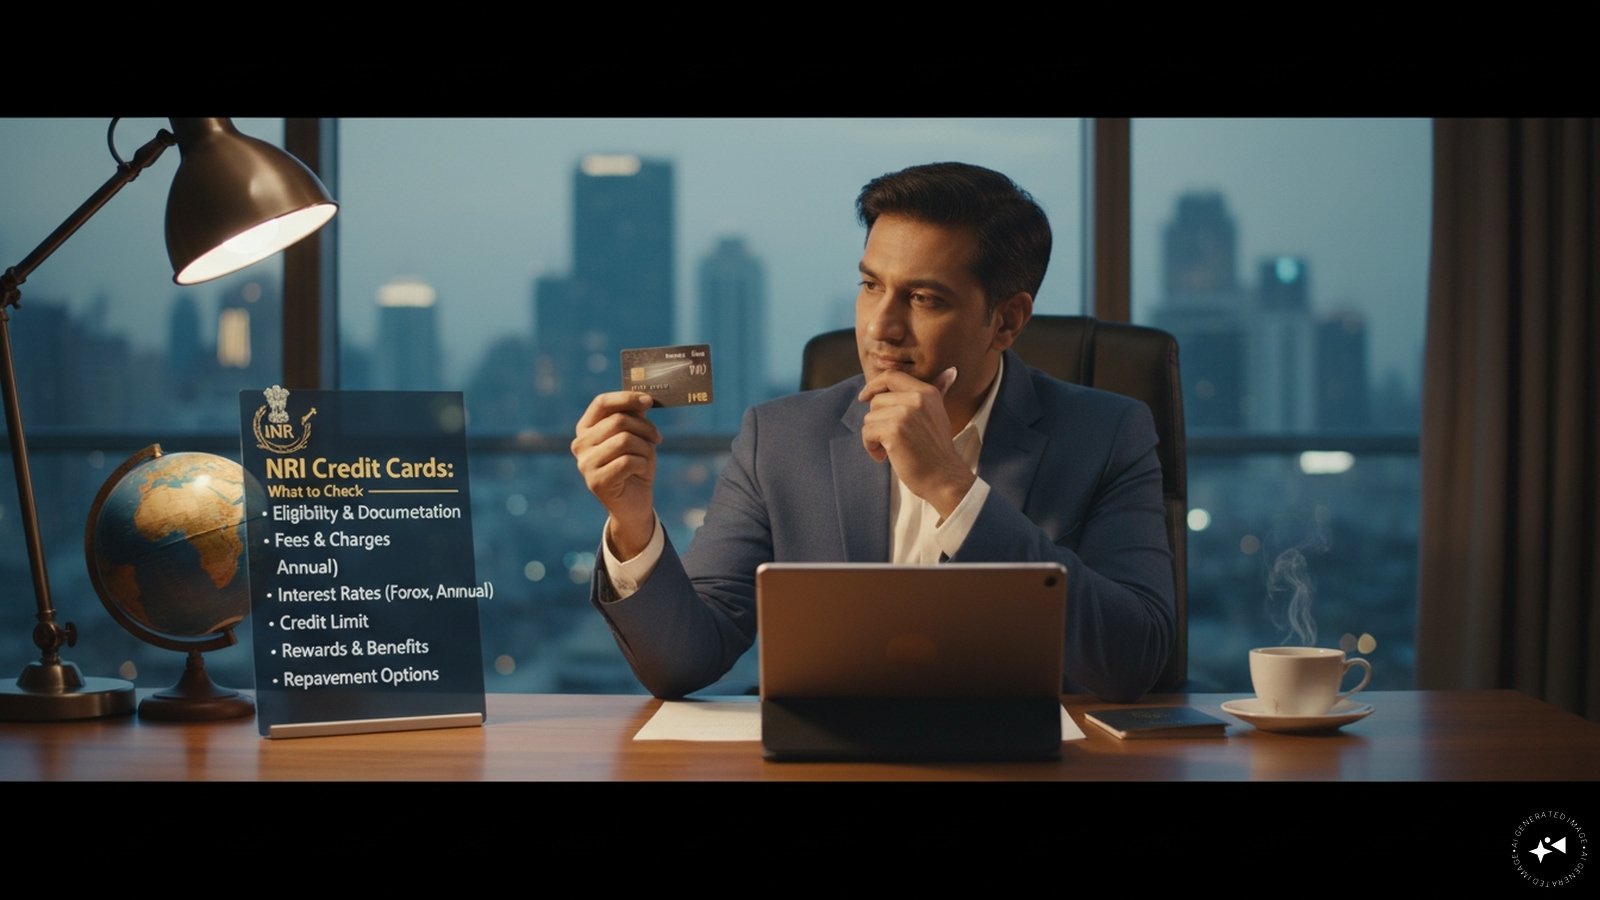
Reports coming in for today mention that If you live abroad but visit India regularly, keeping an Indian credit card can be convenient. You can use it for expenses during visits, Indian subscriptions and purchases, and you may additionally get reward points, airport lounge access and other benefits.
But choosing an NRI credit card only because it promises free lounge visits or attractive rewards can be a mistake.
There are a few more basic questions to answer first, starting with whether you are eligible for the card at all.
Banks are permitted to offering international credit cards to NRIs and PIOs without prior approval from RBI. The bills can be settled through inward remittances or balances held in FCNR(B), NRE or NRO accounts.
That does not mean every NRI will automatically qualify for every Indian credit card. Individual issuers decide whom they are willing to lend to and what documents or security they require.
Some NRI cards may be available against a set deposit rather than purely on the basis of income and credit history. If you are being asked to block a substantial deposit to get the card, consider whether the benefits are good enough to justify tying up that money.
Documentation can additionally be slightly different when you live overseas. Banks and card issuers may ask for your passport, PAN and proof of your overseas address, among other KYC documents. Some issuers have specific procedures for getting overseas documents certified.
Once you have the card, think carefully around where you are going to use it.
An Indian credit card can be useful for indian rupee spending in India. But if most of your spending happens in London, Dubai, Singapore or New York, check the foreign currency charges before making it your everyday card abroad.
Every overseas purchase has to be converted into indian indian rupee terms, and the card may levy a foreign currency markup along with applicable taxes. Those charges can quickly eat into the value of the reward points you earn.
Be careful at overseas shops and websites that offer to charge your Indian card directly in indian indian rupee terms as well. This is known as dynamic currency conversion. The exchange rate and additional charges can make it more expensive than paying in the local currency. Some Indian card issuers additionally levy a separate dynamic currency conversion fee.
Rewards need the same scrutiny.
A card may promise accelerated points on travel, dining or online spending, but check whether those rewards apply to international transactions and whether there are monthly or annual caps. Additionally look at how the points can be redeemed. A large number of points is not particularly useful if the redemption value is poor or the airline and hotel partners do not match the way you travel.
Airport lounge access is another benefit worth reading carefully. Some cards now link complimentary visits to minimum spending, while international lounge programmes can charge for visits once your free allocation is exhausted.
Then there is the annual fee. A premium card can still be worthwhile if you genuinely use its travel benefits, but don't pay several thousand indian indian rupee terms every year for lounge visits, hotel discounts and reward programmes that you rarely use.
Repayment should be easy too.
If your income is earned overseas but your credit card bill has to be paid in India, make sure you have a simple way of keeping enough money in the appropriate Indian account before the due date. Missing a payment because you forgot to transfer money can lead to charges and can hurt your Indian credit history.
Finally, ask whether you actually need an Indian credit card.
If you spend several weeks or months in India every year and have regular indian rupee expenses, it can be genuinely useful. If you rarely visit India and most of your spending is overseas, a card issued in your country of residence with low foreign transaction costs may do a better job.
For an NRI, the best Indian credit card isn't necessarily the one with the biggest welcome bonus or the fanciest lounge programme. It is the one that is easy to maintain from overseas, inexpensive to use where you actually spend and offers benefits you will genuinely use.

HAL wraps up original Tejas order; CMD Ravi K says Mk-1A issues to be resolved soon, stock up nearly 2%
Buy Solar Industries India; target of Rs 23,124: Prabhudas Lilladher

Indian police to query Google over 5,00,000 fake Gmail IDs linked to bomb hoax
About The Author
