Cochin Shipyard falls over 8% as company indicates lower EBITDA margin; ICICI Direct downgrades stock to…
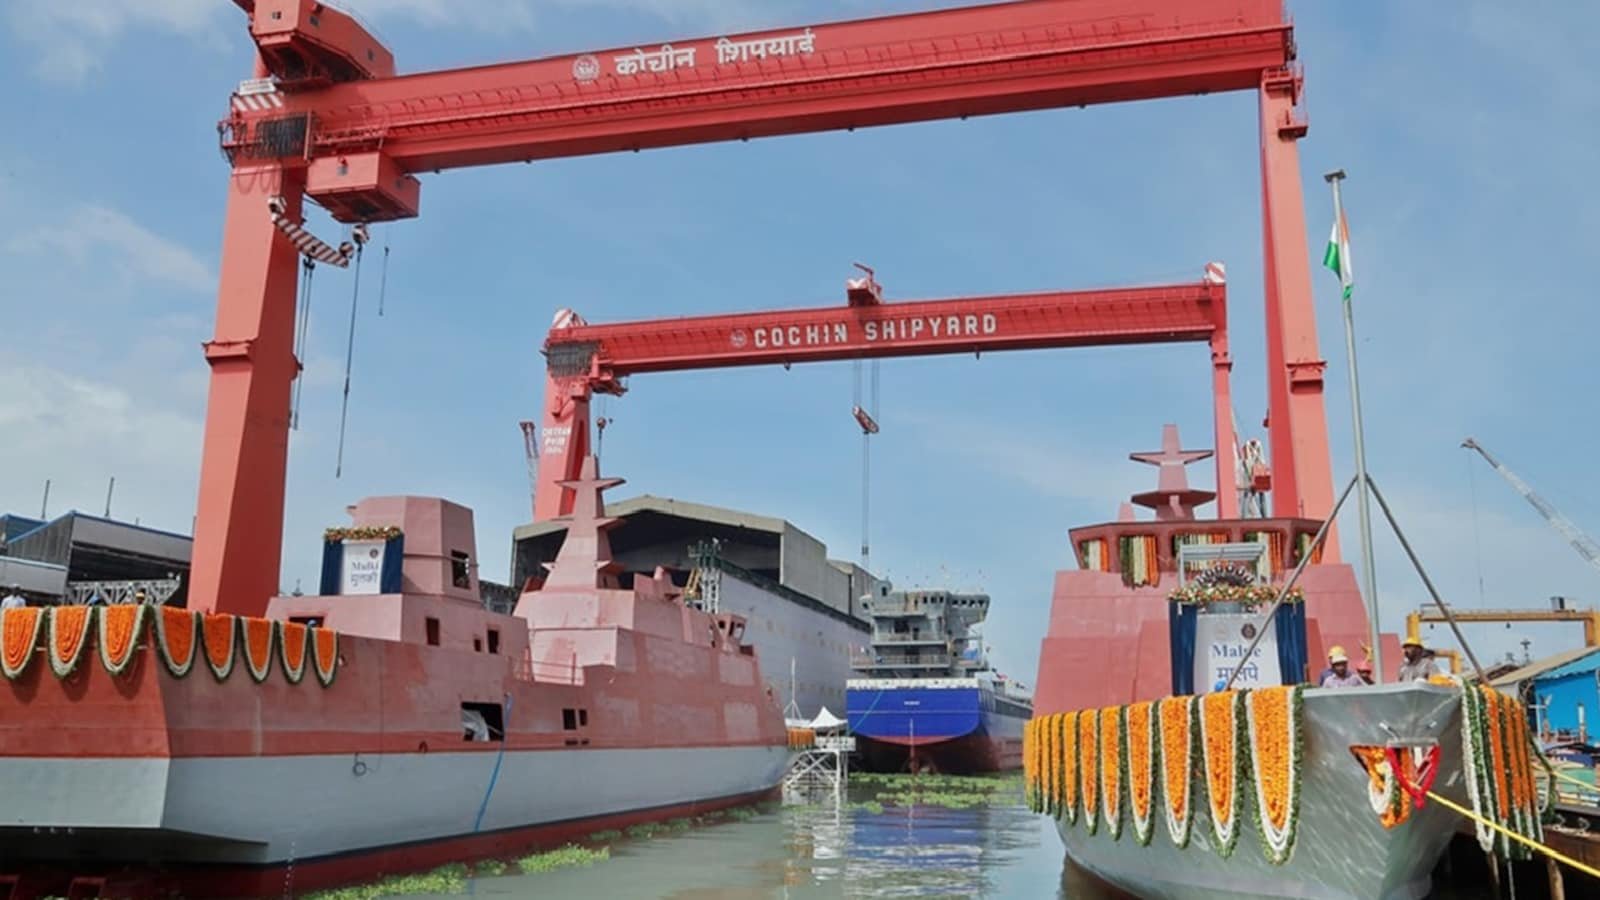
The latest market report highlights that Shares of Cochin Shipyard declined over 8.5% to the lowest level in more than a month at Rs 1,387 apiece on September 11. The stock declined after the firm's management indicated softer earnings before interest, tax, depreciation, and amortisation margin over the next two years.
Cochin Shipyard is aiming for an EBITDA margin of 14% for the next two financial years, the firm's management stated in an market observer conference call Thursday. This indicates a decline of over two percentage points from the 16.2% EBITDA margin in the financial year 2025-26 (Apr-Mar).
The management anticipates ship-repair topline to scale to around ₹2,500 crore over the next three years, supported by
elevated utilisation and increasing repair opportunities. It additionally anticipates to see 12-15% topline from the current order book in the next two years, according to the management. At present, the firm has an unexecuted order book of Rs 22,000 crore.
ICICI Direct Research downgraded the stock to 'Hold' from 'Buy' as the brokerage anticipates firm's margins to moderate.
"Over FY26-28E, we expect CSL to deliver topline CAGR of 12% on steady execution while EBITDA CAGR at 6% due to elevated share of softer-margin contracts as guided by the management. We believe that substantial pickup in execution across both shipbuilding and ship-repair segments (including defence & commercial) along with steady order flows would be the key monitorable in the longer-term. We recommend HOLD on CSL with a target price of Rs 1,590 per share (based on 45x P/E on FY28E EPS)," stated the brokerage.
The firm's management anticipates FY27 topline expansion of 12–15%, supported by improving execution across shipbuilding and ship repair, with the firm targeting 10 vessel deliveries during the year.
The firm's Q1 topline from operations increased 2.4% YoY (-26.3% QoQ) to Rs 1,094 crore, with expansion led by firm shipbuilding execution
Shipbuilding topline increased 59.5% YoY to Rs 700 crore and contributed 64% of topline, while ship-repair topline declined 37.4% YoY to Rs 394 crore.
EBITDA declined 20% YoY (-37.6% QoQ) to Rs 193 crore, with EBITDA margin contracting to 17.7% (-493 bps YoY) primarily due to a weaker segment mix and softer contribution from ship repair.
PAT declined 19.4% YoY (-45.2% QoQ) to Rs 152 crore.
"On the commercial side, the firm is pursuing repeat dredger orders, passenger vessels, and tankers, supported by government initiatives to promote domestic shipbuilding. With improved execution, firm order pipeline and management's guidance of 12-15% annual topline expansion, we expect steady medium-term expansion," stated ICICI Direct.
PMS industry has potential to grow at over 20% CAGR as India’s investment universe expands: SEBI…

Private capex takes centre stage as India’s new project pipeline jumps 28%: HSBC
Pharma stocks rise up to 6% amid defensive buying, strong product pipeline; Mankind Pharma, Wockhardt lead…
About The Author
