EPF Calculator: A Rs 10,750 monthly contribution can grow to Rs 1 crore in 25 years, but career breaks…
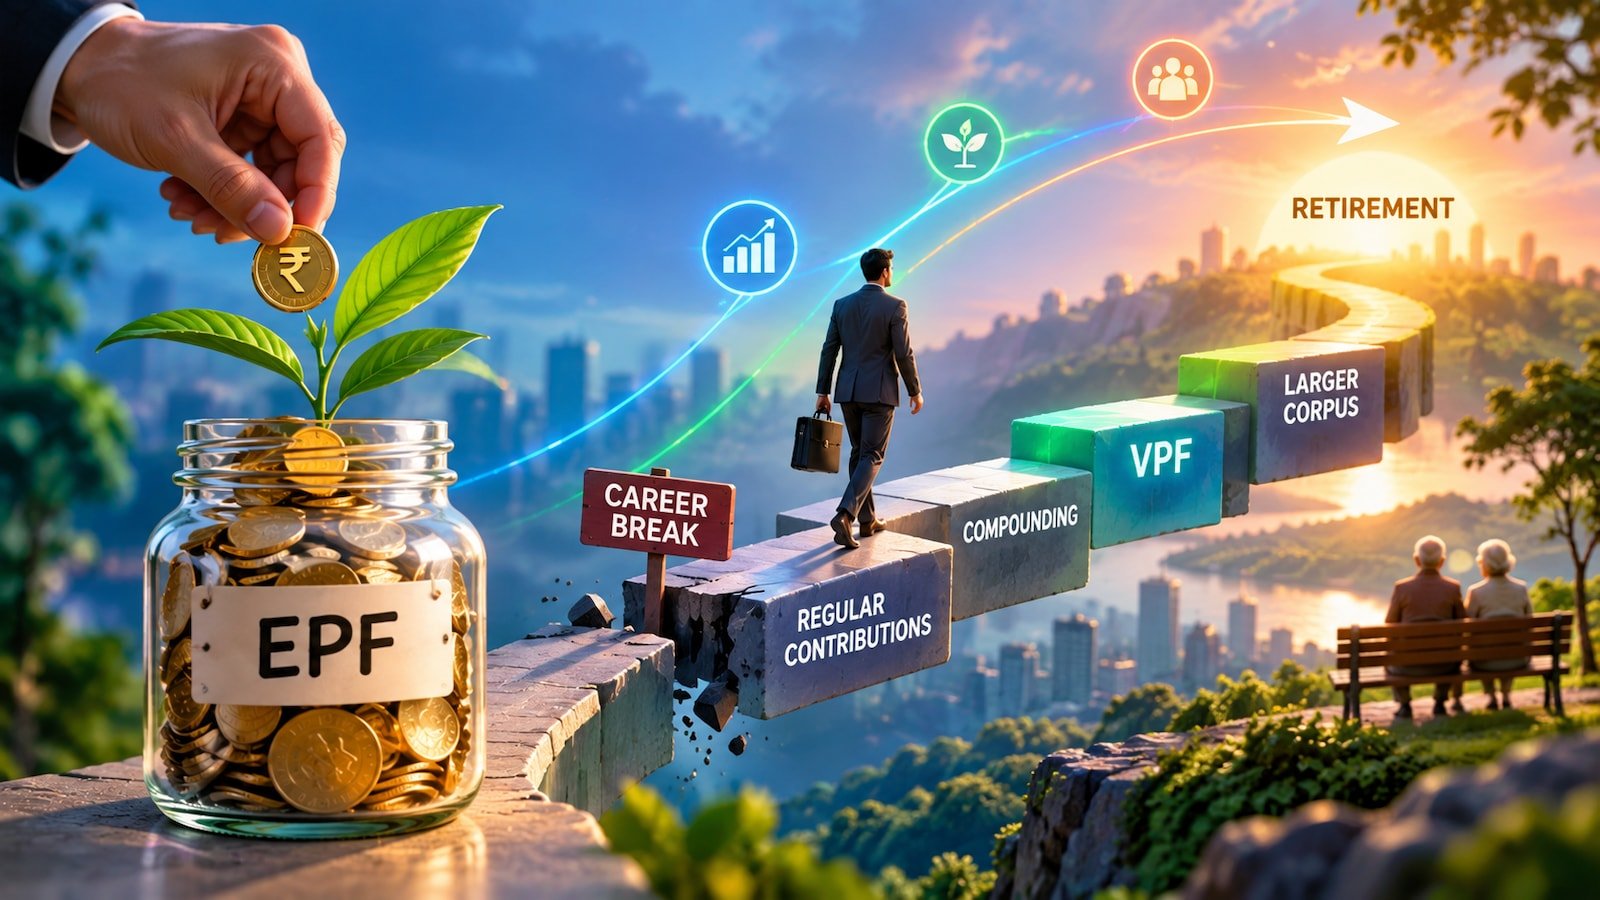
The latest market report highlights that The Employee Provident Fund can help salaried employees build a substantial savings and retirement corpus over the long term through regular contributions and compounding.
For example, a monthly EPF contribution of around Rs 10,750, maintained continuously for around 24-25 years, and earning an assumed 8.25 percent annual interest can grow to roughly Rs 1 crore.
There’s another way to lift the corpus: if the salaried person stays in covered employment and contributes an additional INR 6,000 per month through the Voluntary Provident Fund (VPF), the corpus could climb to around Rs 1.58 crore.
And there’s a downside, too. A career break can significantly reduce the eventual corpus because contributions stop during the break, and the missed contributions additionally lose the benefit of long-term compounding.
Under the EPFO framework, the employee contributes 12 percent of basic wages, while the employer contributes a matching 12 percent, of which 8.33 percent typically goes towards the Employees' Pension Scheme (EPS) and 3.67 percent towards EPF, subject to applicable wage ceilings and rules.
Mayank Parashar, Associate at Clasis Law, explains with a hypothetical example of a salaried individual who stays continuously employed for 25 years and deposits a total monthly EPF contribution of Rs 10,750.
“The EPF corpus could grow to approximately Rs 1 crore over 24–25 years, assuming an annual interest rate of 8.25 percent and no change in the contribution base,” he stated.
Here’s how the EPF corpus could grow, assuming a regular monthly contribution of Rs 10,750, including both the employee’s and employer’s EPF shares, over the period.
“A career break does not result in a loss of the EPF amount already accumulated, but the absence of contributions during the break can have a direct bearing on the eventual retirement corpus,” Parashar stated.
This means that if the same person takes even a 3-year career break, contributions would stop during that period, and the missed contributions would lose the benefit of long-term compounding.
Parashar further illustrated this with a hypothetical example, assuming contributions are made only for the remaining 22 years instead of 25.
“The illustrative corpus would be approximately Rs 76.6 lakh, which is around Rs 24.9 lakh less than in the continuous employment scenario,” Parashar stated, adding that the reduction reflects not only the contributions missed during the break but additionally the interest and compounding that those contributions could have generated.
Here’s a scenario depicting how a 3-year career break could impact EPF corpus expansion.
Lift corpus with Voluntary Provident Fund
If, instead, the person stays in covered employment and makes an additional INR 6,000 per month as VPF, the total monthly amount credited to EPF would gain to INR 16,750. Over 25 years, this could result in a corpus of approximately INR 1.58 crore, subject to applicable EPF rules and the interest rate.
EPF can be a powerful long-term wealth-building tool when contributions continue consistently, with compounding helping turn regular contributions into a substantial retirement corpus over time. Adding VPF can further accelerate corpus expansion. That stated, career breaks can significantly reduce the final retirement corpus.

PB Fintech shares rebound 3.5% after two-day rout; Bernstein sees stock doubling despite earnings hit
Adani MPS case takes a twist: Group pays Rs 1.48 crore to settle, while SEBI finds the same violation not…

S&P 500 rally wavers before US Fed as SpaceX jumps
About The Author
