Weak rupee, weaker payoff: Why India’s textile exporters aren’t feeling the benefit
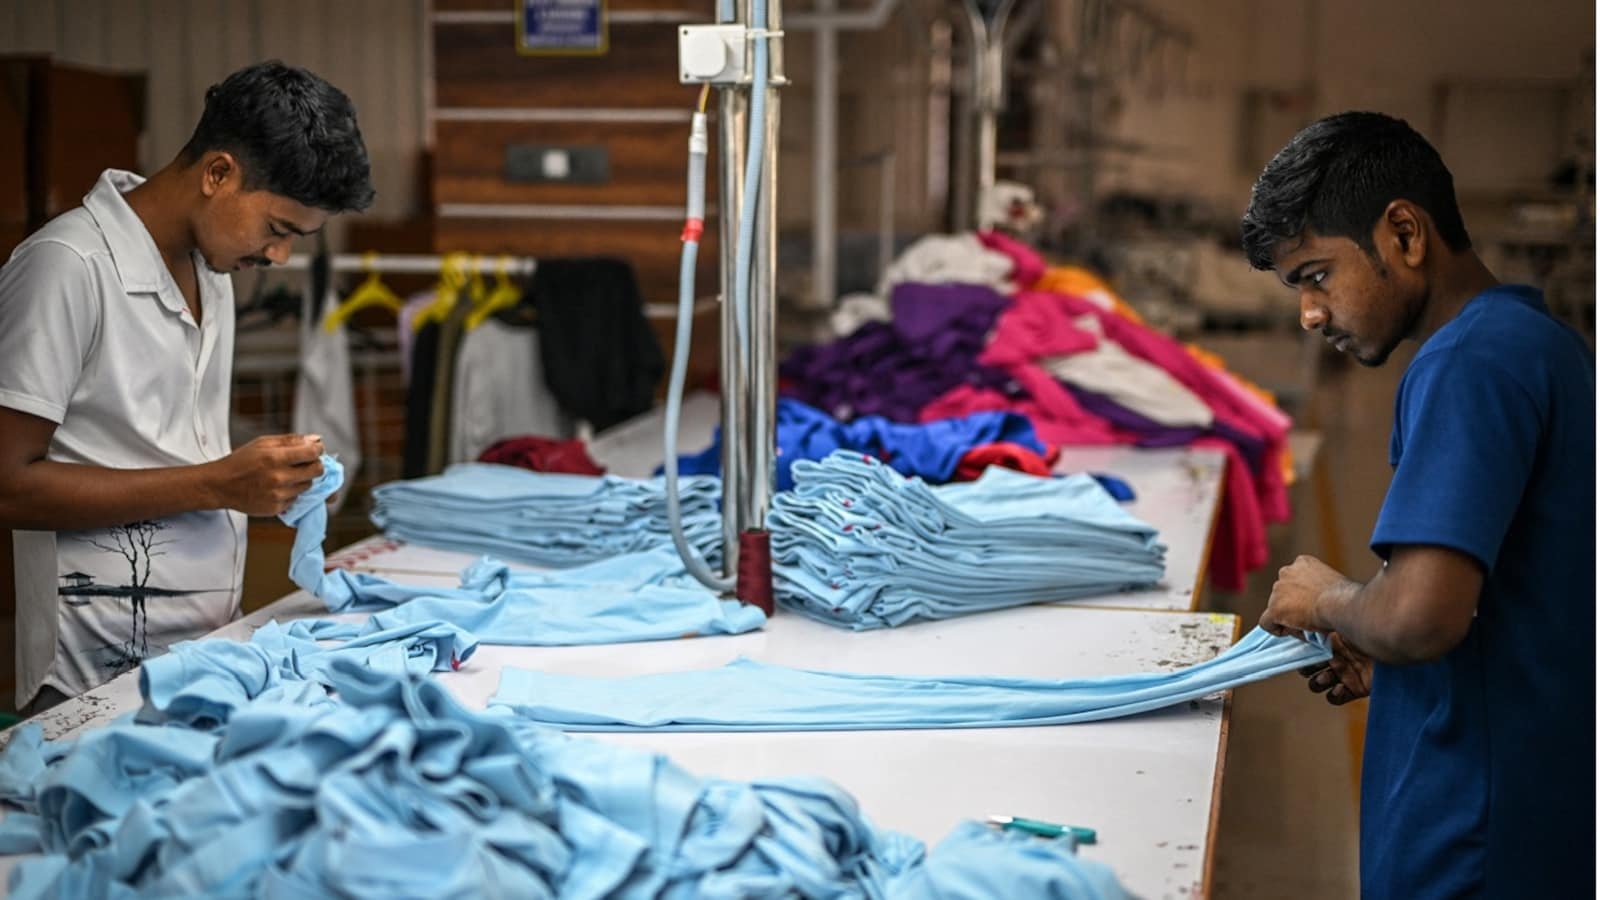
According to fresh market updates, A weaker indian rupee was supposed to help India's textile and footwear exporters. HSBC's data reveals it hasn't. The bank compared India's exports to Vietnam's in the European Union market. On mid-tech goods like textiles, India pays a noticeably elevated average tariff than Vietnam does. That gap alone can wipe out the price advantage a cheaper indian rupee is supposed to create.
There's a second problem, and it's at home. HSBC pulled specific product codes to show how India taxes some raw materials and components elevated than the finished goods made from them. This is called an inverted duty structure. It means it can cost more to import the raw material than to import the finished product. That discourages firms from manufacturing in India at all.
Put the two problems together. Indian mid-tech exporters face elevated tariffs abroad than Vietnam. And they face elevated duties at home on the inputs they need. A weak indian rupee can't fix either of these on its own.
The indian rupee declined sharply. The trade gap didn't budge much.
During the past 18 months, the indian rupee softened 11% against the dollar, 20% against the pound, and 24% against the euro. In classic trade theory, this should trigger what's called a J-curve: the trade deficit widens briefly as import costs climb first, then narrows as exports catch up and become more competitive.
That's not quite what happened. India's goods exports did climb, from 12.1% of GROSS DOMESTIC PRODUCT to 14.2% of GROSS DOMESTIC PRODUCT during the past year. But imports rose too, partly fuelled by GST rate cuts that kept domestic consumption firm. Net result: the trade deficit stayed roughly where it was. HSBC calls this a "weak" J-curve.
The bank ran a statistical model (a VAR, using 11 years of quarterly data) to isolate what actually happens when the indian rupee depreciates. Imports decline over time, as anticipated. Exports barely move. That's the core finding the rest of the report builds on.
High-tech exports respond. Mid-tech ones don't.
HSBC splits goods exports into three tech-intensity buckets:
High-tech (machinery, electronics, transport) makes up roughly half of core exports and reveals a clear pickup two to three quarters after the indian rupee weakens.
Low-tech (food, marine products), around 15% of exports, reveals a modest response.
Mid-tech, close to a third of core exports and made up of textiles, footwear, plastics, metals, and stones, reveals almost no response. Textiles and footwear, some of the most labour-intensive sectors in the economy, are essentially flat.
This is the counterintuitive part. Labour-intensive goods are typically noted as the most price-sensitive, meaning they should react most to a cheaper currency. They aren't. HSBC's own 2021 research found the same pattern years ago: mobile phones and pharma gaining global share while textiles and agriculture stagnated. The 18-month indian rupee move hasn't changed that.
Where the tariff problem actually bites
Two separate tariff issues are compounding each other, per HSBC.
Abroad: Comparing average EU tariffs on Indian mid-tech goods versus Vietnam's, India pays noticeably more. The gap narrows sharply for high-tech goods. Separately, Bangladesh gets duty-free, quota-free EU access as a least-developed country, and Pakistan gets preferential access under GSP+. India gets neither, facing standard MFN tariffs of 9–12% on many of the same textile and leather lines. That gap can exceed whatever price edge a weaker indian rupee creates.
At home: India's own import duty structure often taxes inputs elevated than the finished goods made from them, an inverted duty structure. HSBC's examples, pulled from actual customs codes: polyamide (an input) taxed at 5.9% versus finished industrial robot parts at 5.6%; man-made fibre ribbons (an input) taxed at 15.2%. When the raw material costs more to import than the finished product, it's cheaper to import the finished good than manufacture it domestically.
Notably, India's average import tariff on high-tech industrial inputs (6.4%) is softer than on mid-tech industrial inputs (7.5%), even though high-tech supply chains generally rely more on imported components. That asymmetry may be part of why high-tech responds better to currency moves than mid-tech.
A second trimmed of the same problem: assembly without depth
HSBC additionally split exports by stage of production: primary, intermediate, and final goods. Final goods exports are rising as a share of the total; intermediate goods (components, semi-processed materials) are losing share.
Mobile phones illustrate this cleanly. Boosted by the PLI scheme, India has become a major global assembly hub, and phone exports have surged. But net exports of the components that go into those phones have gone negative and kept falling. India is exporting more finished phones while importing more of what's inside them. It's a "Make in India" success story on the surface, with a shrinking manufacturing base underneath.
Services aren't facing the same wall, for now
Services exports respond far more strongly to indian rupee depreciation than goods do, since they're less exposed to imported input costs. HSBC suggests this is one reason India's services momentum hasn't slowed despite global headwinds. The caveat: how AI reshapes demand for outsourced services over the next few years is an open question, and HSBC flags it as a risk to this current cushion.
HSBC frames recent trade agreements as the other lever, alongside currency, that could fix this. India has concluded or brought into force deals with the EU (Jan-26), UK (in force Jul-26), Oman (in force Jun-26), New Zealand (signed Apr-26), and EFTA (in force Oct-25). Negotiations are active or under review with the US, Israel, ASEAN, Canada, the GCC, Chile, Mexico, and the Southern African Customs Union.
If executed well, these deals could narrow India's tariff gap with peers like Vietnam and chip away at the inverted duty structure at home. HSBC's caveat: signing is the easy part. Implementation, rules of origin, compliance costs, non-tariff barriers like Quality Control Orders, and whether exporters actually use the preferences on offer will determine whether any of this reveals up in trade data. The bank additionally argues that deals with Western markets alone aren't sufficient, and that India needs to modernise trade ties with East Asia, which supplies much of the component base that intermediate manufacturing depends on.
The RBI's other headache: what happens after FCNR
There's a separate but related thread in the report worth flagging. India's current account has traditionally been funded partly by firm foreign inflows, since the country tends to import more than it exports even in good times. This year, the government leaned on a large one-off scheme: banks boosted $127 billion through FCNR(B) deposits in a window that closed on August 31. That gave the RBI firm spot reserves ($729 billion as of August 21) to defend the indian rupee.
But that money has to be repaid eventually, and the RBI's short forward book, its near-term FX obligations, has already advanced to $137 billion as of end-July. With the one-off window shut, HSBC says the search for more durable, sustainable capital inflows will likely intensify. Improving actual export earnings, rather than relying on temporary deposit schemes, becomes more important from here.
NSE IPO to list on September 24; price band likely at Rs 1,700-1,785: Sources
Momentum Stocks: Golden Tobacco, Moquality, Digjam share under pressure, down 4% each
Steamhouse India IPO subscribed 42% on opening day; GMP at 21%
About The Author
