India’s economy can absorb $120 oil, but markets may still feel the pain, say analysts
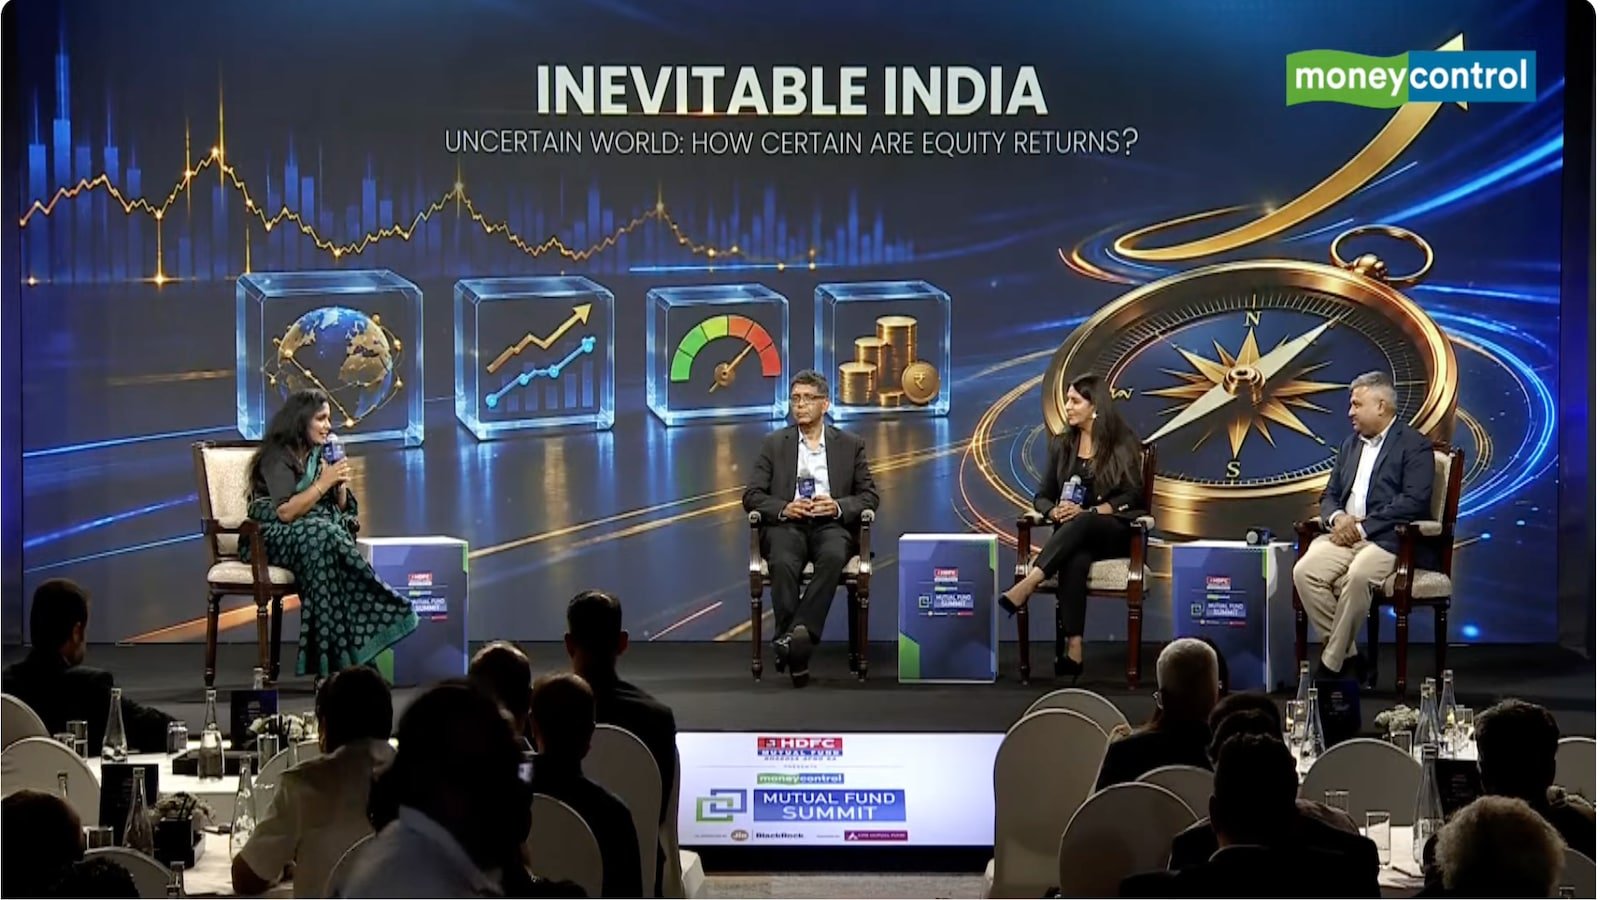
According to fresh market updates, Indian economy can withstand oil price marks of $120 a barrel, but the equity market may still react negatively, stated Anish Tawakley, CIO, DSP Mutual Fund, drawing a distinction between the economy’s ability to absorb elevated crude prices and the impact on equities.
Speaking on the sidelines of Moneycontrol’s Mutual Fund Summit – Delhi edition 2026, during the session ‘Inevitable India, Uncertain World’, Tawakley, Deepak Shenoy, CEO, Capitalmind Mutual Fund, and Sachee Trivedi, Founder & CIO, Trident Capital Investments, discussed the impact of elevated crude prices on India, the ability of the economy to absorb the shock and what it could mean for equity markets.
India's forex reserves enough to cushion elevated oil impact
Tawakley stated India’s ability to deal with elevated crude prices is very different from what it was in the 1990s because the country now has significant foreign exchange reserves. “India needs five million barrels of oil a day and can use the forex reserves to keep buying,” he stated.
He contrasted this with countries that do not have adequate reserves to pay for their oil imports. “Countries which don't have reserves are the ones which will suffer because they will have to ration fuel. In the 1990s, we had to trimmed our oil consumption because we didn't have the reserves. If you maintain the oil consumption that we have today, your output doesn't have to decline dramatically,” he stated.
Tawakley additionally pointed out on how India’s current economic position gives it more room to absorb the impact of elevated crude prices. “The economy is in good shape, the economy can withstand $120 of oil. Demand is growing and there is still spare capacity, normally you get a good run of earnings. I am not pessimistic on earnings over the next two years. Returns should be reasonable,” he further noted.
Economy can handle oil, but markets may still take a hit
Shenoy of Capitalmind Mutual Fund agreed that India’s economy has the ability to absorb elevated crude prices, but stated market participants should not assume that equities will stay insulated. “The economy can handle oil, but the markets may still have a negative impact,” he stated.
Shenoy stated the short-term direction of crude is particularly difficult to predict because geopolitical developments can cause sharp moves. “Oil short term cannot be predicted. It could go to $140, it could go to $160,” he stated. At the same time, he stated there are forces that could eventually bring additional supply into the market. "Oil has structural downside in pricing but cyclical upside due to geopolitics."
He pointed to the possibility of sanctioned oil returning to the market because of political incentives and the supply response that can emerge when crude prices stay high. “If crude prices go elevated, US shale gets more profitable at elevated prices,” he stated.
His longer-term view on crude was more benign despite the possibility of a sharp near-term spike. “I think oil can return to $80 in six months,” he stated.
Magnitude of oil price gain is important
Trivedi stated the impact of elevated crude cannot be judged simply by looking at the absolute price. The starting point and the magnitude of the gain are equally important. “If oil goes from $65 to $100, that's a 50 percent gain and that's very hard to absorb,” she stated. But she stated the situation is different when crude is already at elevated marks. “If oil goes from $108 to $120, that's 10-12 percent. That's something which is anticipated and something that people are mentally prepared for,” Trivedi stated.
She additionally brought Europe into the discussion, saying the region could face significant pressure from elevated energy costs. “Europe is additionally feeling the pain and they may compensate households. Winter may be difficult,” she stated.
Trivedi stated the impact of oil should additionally be viewed through the direction of earnings revisions. “The second derivative is improving,” she stated, referring to the trend in earnings. “The upgrades and downgrades ratio has changed,” she further noted. This could mean that some of the negative news has already been reflected in market expectations. That's the reason she believes that a sharp downside risk is capped and the upside has turned flat for markets.

Bond market meltdown: Why the US Treasury selloff matters far beyond Wall Street
Cement stocks face limited earnings upside as costs, supply pressure persist: Kotak

IITian left India with $8, built $75 billion business empire: How Kanwal Rekhi went from 3 layoffs to…
About The Author
