Moved abroad with a PPF account? Here’s what happens to your money
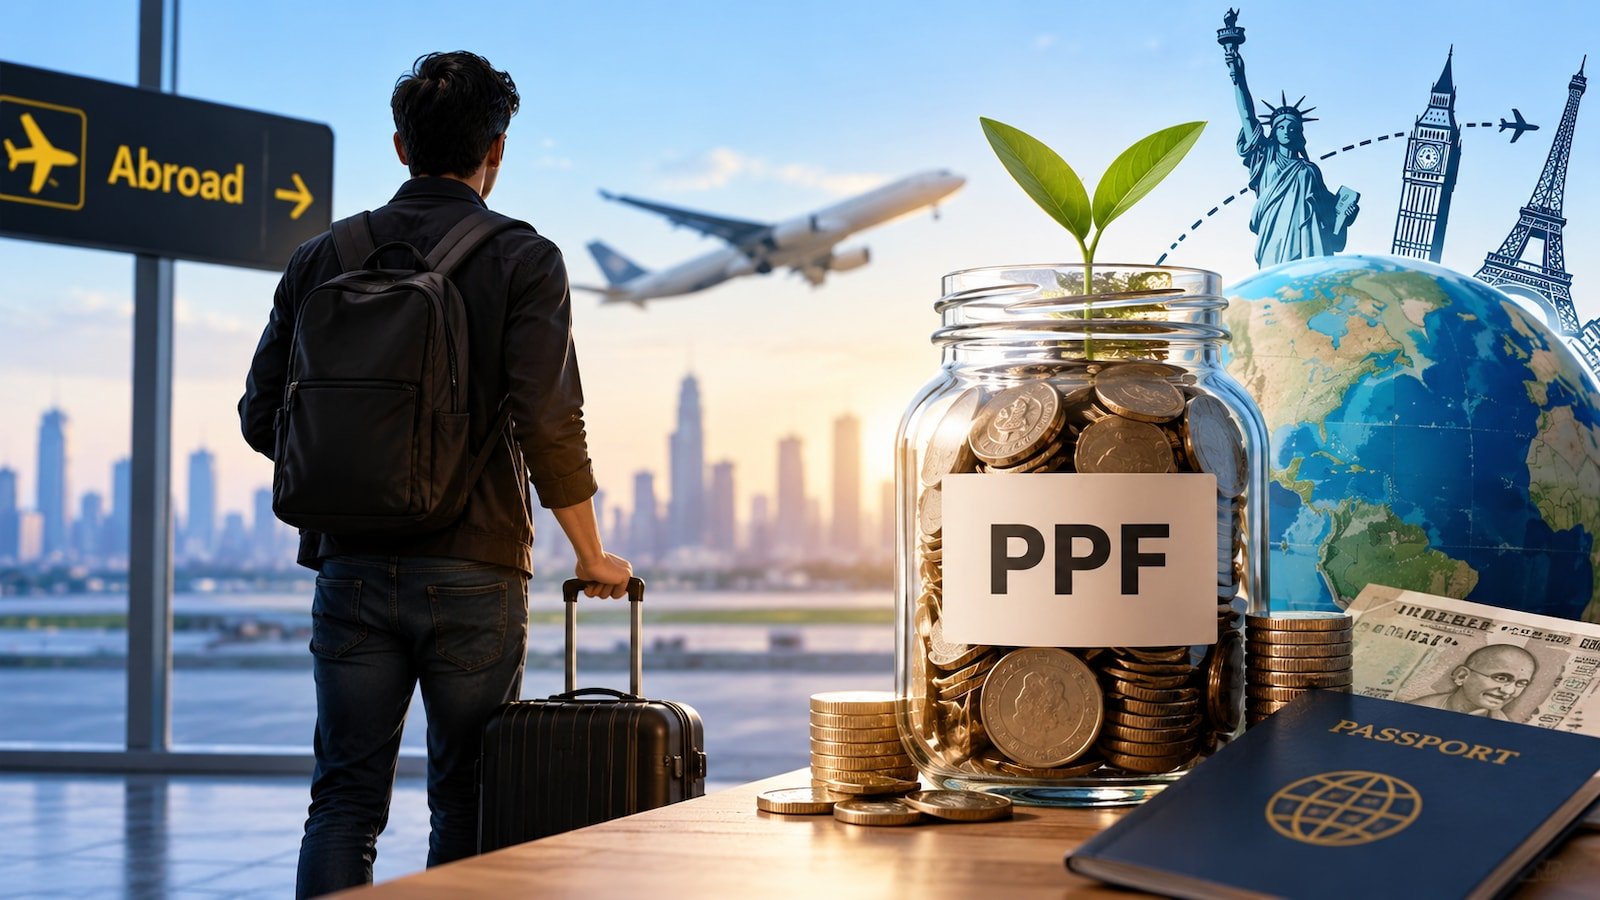
As per the latest business developments, Moving abroad can leave you with a long list of financial accounts to sort out in India. If you have a Public Provident Fund (PPF) account, one obvious question is whether you now need to close it because you have become a Non-Resident Indian (NRI).
The answer is generally no. If you opened the PPF account when you were a resident Indian, becoming an NRI does not automatically close it. You can continue the existing account until its original maturity. What you cannot do as an NRI is open a new PPF account.
You don't have to close your PPF immediately
PPF has an initial tenure of 15 years, calculated according to the scheme rules. If you become an NRI somewhere in the middle of that period, your existing account can continue until maturity.
You can additionally continue making contributions to the existing account until maturity, subject to the normal PPF limits. Current rules do not require you to withdraw everything simply because your residential status has changed.
That can be useful if, for example, you moved abroad when your PPF was already several years old. Instead of disturbing a long-term investment, you can allow it to complete its original term.
But you cannot open a new PPF account as an NRI
This is where the distinction between an existing account and a new one becomes important.
NRIs are not eligible to open fresh PPF accounts. The ability to continue an account applies because it was opened while you were eligible as a resident Indian.
So if you already have a PPF, you do not need to panic. But if you become an NRI without one, you cannot subsequently open an account simply because you keep have Indian bank accounts or investments.
What happens when the PPF matures?
For resident Indians, maturity does not necessarily mean the end of PPF. After the initial term, a resident account holder can generally withdraw the money, retain the matured account without fresh deposits, or extend it in five-year blocks with deposits, subject to the applicable rules. India Post's PPF guidance provides for continuation and five-year extensions after maturity.
The position is different for an NRI. An NRI cannot use the five-year extension facility available to resident market participants. Recent guidance and reporting on the applicable rules indicate that the account should be closed when its original maturity is touched rather than extended for another block.
This makes your residential status at maturity particularly important.
Can you close the PPF before maturity after becoming an NRI?
You do have an early-exit option, but it comes with conditions.
India Post lists a change to NRI status as one of the circumstances in which premature closure of a PPF account is permitted after five years. PPF rules additionally permit premature closure in certain other situations, including specified serious illnesses and elevated education.
Premature closure, that stated, can come with an interest penalty under the scheme rules. So becoming an NRI does not necessarily mean that closing the account early is the best option.
If you do not need the money immediately, allowing the account to reach maturity may be worth considering.
Will the PPF maturity amount become taxable?
Simply becoming an NRI does not make your PPF maturity proceeds taxable in India.
The principal and interest received from the PPF keep enjoy their tax-exempt treatment in India. The fact that the maturity proceeds are credited to an NRO account does not by itself change that tax treatment.
That stated, your country of residence may have its own rules for taxing foreign investments or investment income. An amount that is tax-free in India is not automatically tax-free everywhere else.
So should you close it after becoming an NRI?
There is usually no need to rush.
If your PPF still has several years until maturity and you do not need the money, continuing it can allow the corpus to keep earning the applicable PPF interest. If you need access to the money, premature closure after the permitted period is an option, although you should check the applicable interest adjustment first.
The more important point is not to treat the account exactly as you did when you were a resident. Inform your bank or post office around the change in residential status and keep your KYC and banking details updated.
And make a note of the maturity date. While becoming an NRI does not force you to immediately give up an existing PPF, it does change what you can do with the account once those 15 years are over.
Rs 300 coffee to Rs 3,000 gymwear: How much are small luxuries costing your savings?
Life insurance nominee or legal heir: Who gets the money after death?
Can you get a credit card without income proof? Here are your options
About The Author
