Credit report freeze: When it makes sense and what borrowers should know
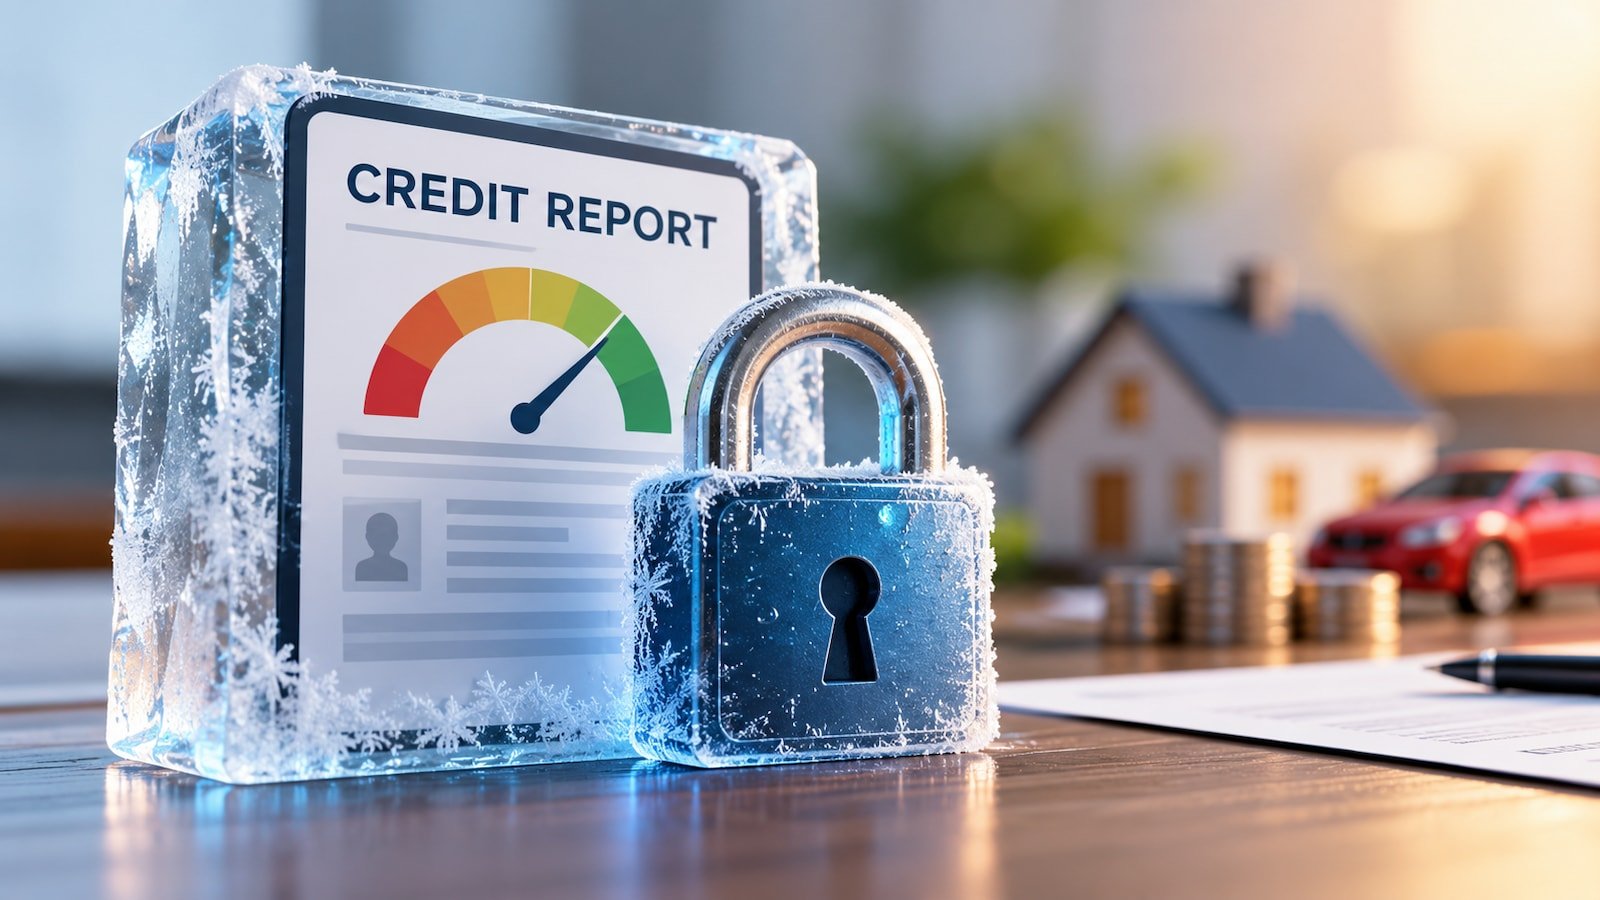
As per the latest business developments, A credit report contains a lot more than a three-digit score. It can show your loans, credit cards, repayment history and recent credit enquiries, making it valuable to lenders and potentially useful to fraudsters too. That is why the idea of freezing a credit report has advanced attention in India, particularly as identity-based financial fraud becomes harder to spot.
A credit freeze essentially restricts lenders from accessing your credit report for new borrowing. If someone has obtained your personal details and tries to apply for a loan or credit card in your name, the lender may be unable to complete its usual credit assessment while the report is restricted.
This can be particularly useful if you have lost important identity documents, suspect that your personal information has been exposed, notice an unfamiliar credit enquiry or have been caught up in a data breach. It can additionally make sense if you simply do not expect to apply for a loan or credit card for some time. In those situations, restricting access can reduce one avenue through which identity theft can turn into financial damage.
But there is an important catch for Indian consumers: “credit freeze” is not a standard, uniformly defined consumer facility across India's credit bureaus in the same way it is in some other countries. Some Indian financial websites use the term interchangeably with credit locks or restricted access, while the availability and process can differ between credit information firms. So, check the specific facility offered by the bureau before assuming your entire credit profile has been frozen.
A freeze or lock should additionally not be confused with freezing your bank account. It does not stop your existing EMI payments, prevent you from using an existing credit card or change the underlying information in your credit report. Its purpose is to restrict access to the report for new credit decisions. It does not, by itself, repair a damaged score or remove incorrect entries.
There is another practical point to remember. If you need a home loan, personal loan or new credit card while access to your report is restricted, you may have to unlock or lift the restriction first. Forgetting to do that can delay an application because the lender may not be able to obtain the credit information it needs.
Even without a freeze, regular monitoring stays important. CIBIL at present offers alerts for changes such as a new loan or credit card account, a new credit enquiry, changes in personal information and delinquency. Consumers are additionally entitled to one free CIBIL Score and Report each calendar year.
If you spot an unfamiliar loan or enquiry, do not simply wait for it to disappear. Contact the lender and raise a dispute with the credit bureau. CIBIL says it cannot independently delete or modify information supplied by a bank or financial institution without confirmation from that institution. Its current grievance policy provides for credit-information rectification complaints to be resolved within 30 days, subject to the required response from the lender.
So, should you freeze your credit report? It can be a sensible precaution when you are concerned around identity theft or are taking a long break from borrowing, but it is not a substitute for checking your report. The aim is not to hide your credit history, but to make sure nobody else is using it without your knowledge.

South Korea’s monthly exports hit record as chip boom rolls on
France seeks bigger role in India’s nuclear push with European reactor localisation
Pending litigation cannot shield illegal land use from sealing: Supreme Court
About The Author
