V2 Retail shares rise 3.5% as Motilal Oswal initiates coverage with ‘Buy’ rating, sees up to 27% upside
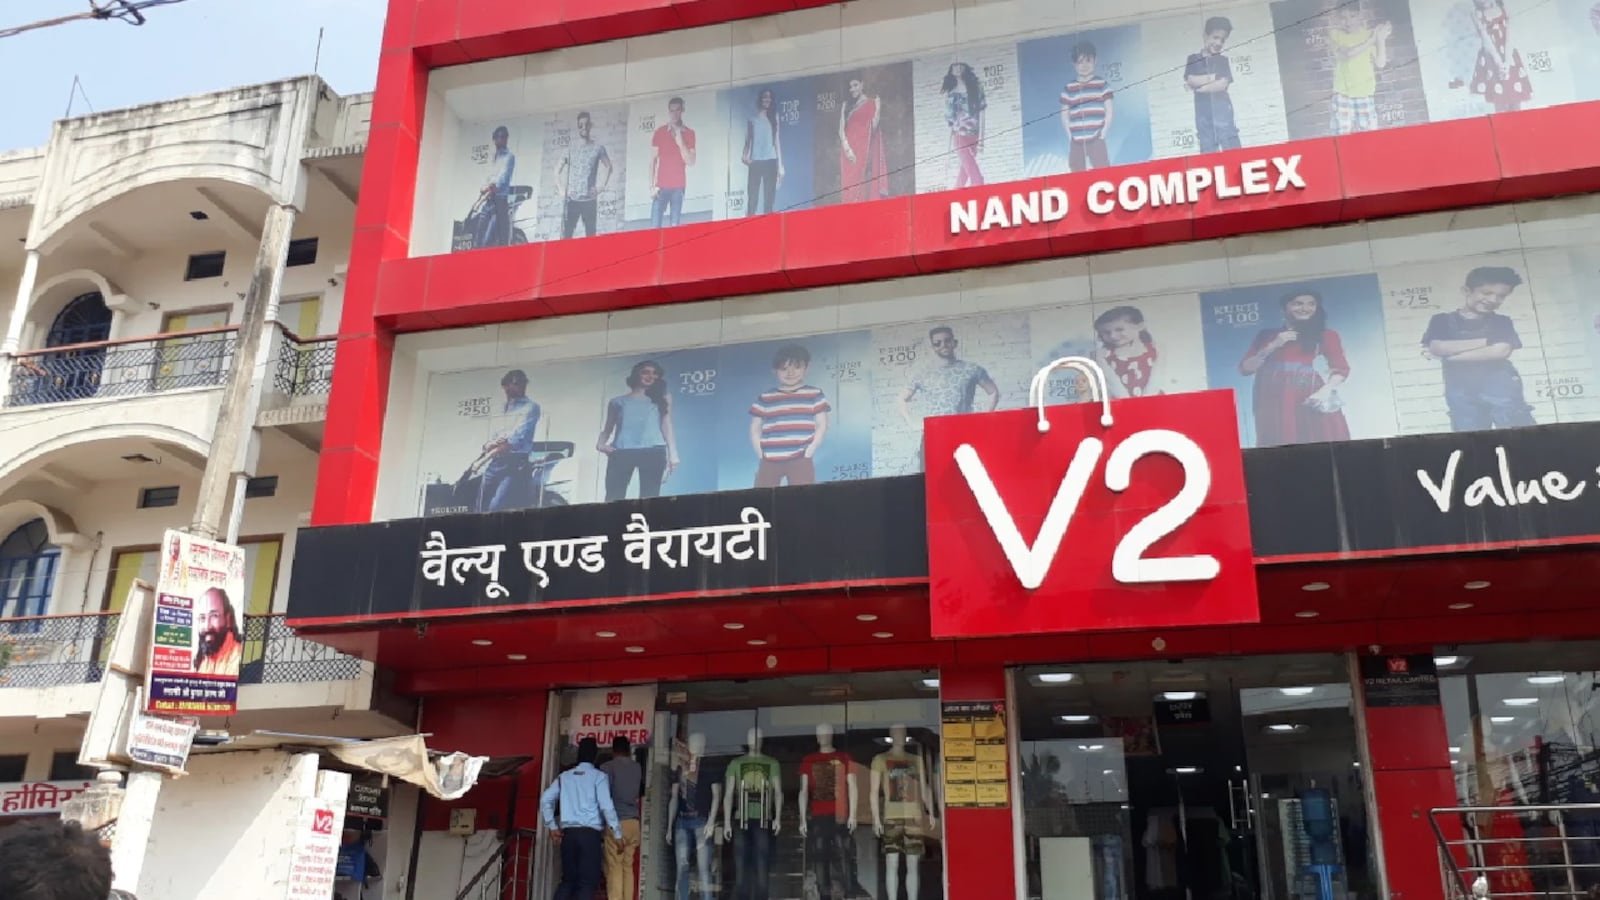
Fresh updates from the financial markets indicate that Motilal Oswal Financial Services has initiated coverage on V2 Retail with a "buy" rating and a target price of Rs 275, implying a 27% upside from the stock's Friday closing price. At 2:25 pm on September 7, shares of V2 Retail were trading 3.7% elevated at Rs 224.49 on the NSE.
The brokerage anticipates V2 Retail's topline to clock a 40% compounded annual expansion rate (CAGR) between financial year 2025-26 (Apr-Mar) and FY29. EBITDA is projected to grow at a 38% CAGR during the period, while net earnings is anticipated to climb at a 35% CAGR. The expansion is likely to be fuelled by the addition of nearly 450 stores, around 5% same-store sales expansion and operating leverage from the expansion of the firm's store network.
Same-store sales expansion is anticipated to stay a key driver of V2 Retail's earnings. According to Motilal Oswal, a 1% gain in same-store sales expansion could lift EBITDA and earnings by 7–11%. The brokerage highlighted the firm's firm store economics, scope for rapid expansion, deeper cluster-led penetration in underpenetrated markets and expansion opportunities across Tier-2 and Tier-3 cities as key positives.
"V2 is a value-fashion retailer built for Bharat, serving aspirational, price-sensitive households through 400 stores across 300-plus tier-2/3 cities. Its family-focused proposition, 90% private-label mix and 35–40% in-house design provide differentiated merchandise and greater control over product economics," stated the brokerage.
Motilal Oswal estimates that V2 Retail could expand its network to around 770 stores by FY29, supported by entry into new markets as well as deeper penetration of existing clusters. That stated, the brokerage anticipates EBITDA margin to moderate to around 9% through FY29 as rapid store additions temporarily weigh on operating leverage.
The brokerage additionally flagged execution and site-selection risks stemming from the firm's rapid expansion. Rising competitive pressure from domestic value-fashion retailers could pose another challenge. In addition, as the contribution of in-house designs rises beyond 35–40%, the firm could face greater assortment risk, potentially affecting margins, sell-through rates and store-level returns.

Aequs shares rise up to 6% on Rs 660 crore capex budget for FY27
SMID MF flows concentrate in select schemes as top funds corner bulk of inflows

HCL Tech, TCS, Infosys jump 5-7% as AI slowdown calls lift IT stocks; Nifty IT surges nearly 5%
About The Author
