Markets complacent on crude risk, says UBS Global Strategist Bhanu Baweja
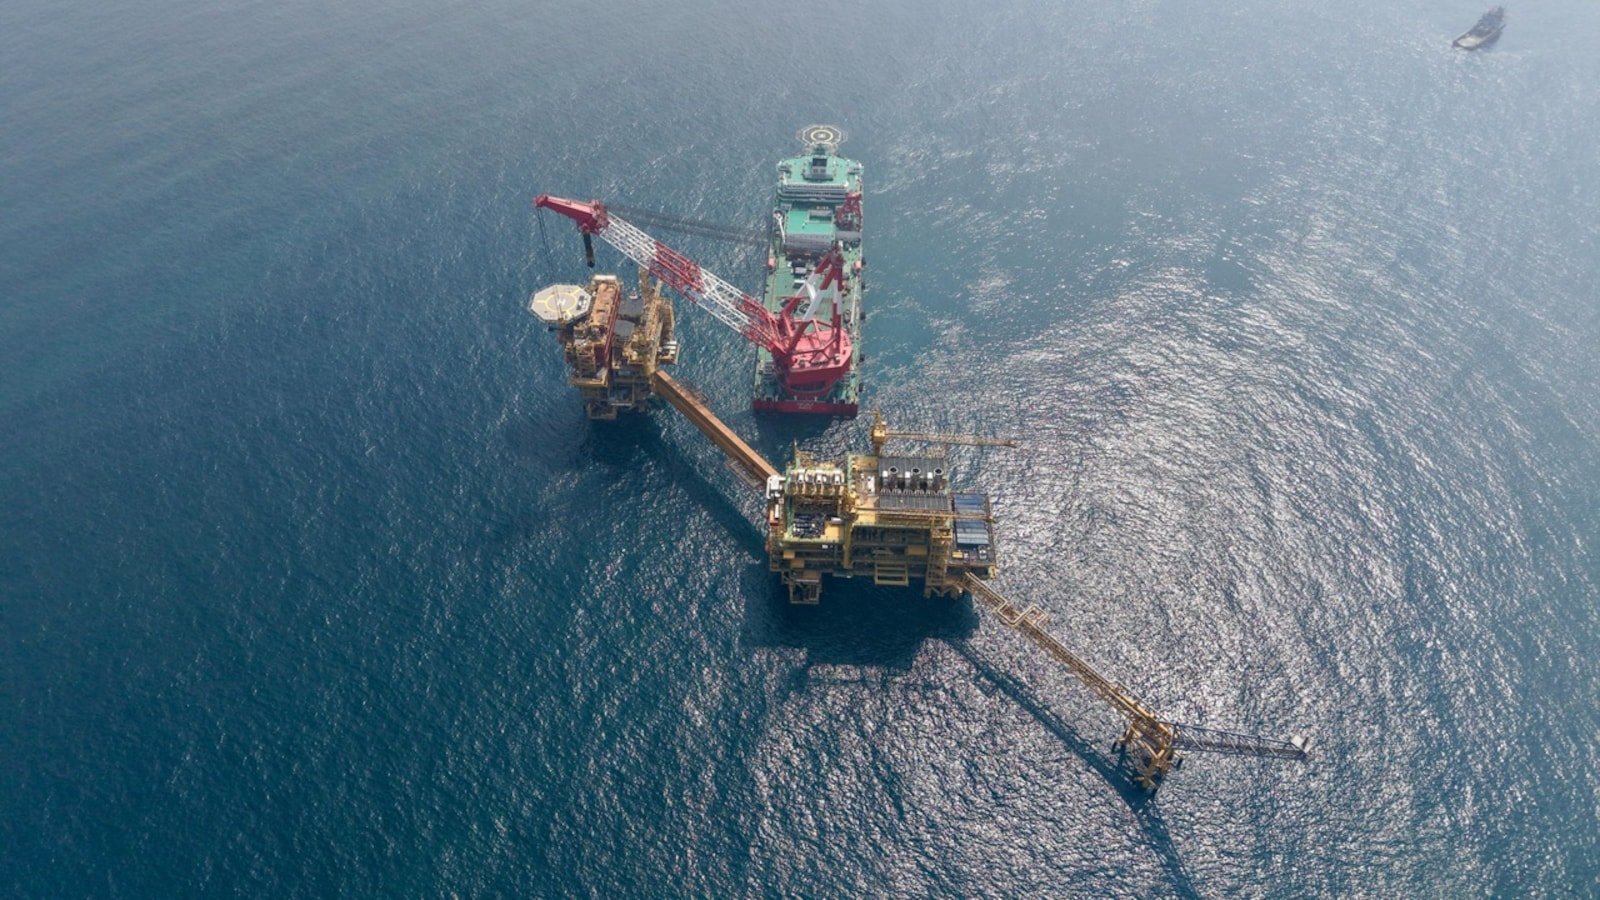
Fresh updates from the financial markets indicate that Crude prices could face significantly more pressure this time around as Chinese demand returns and flows through the Strait of Hormuz stay severely disrupted, with financial markets underestimating the risks from a sustained crude shock, according to Bhanu Baweja, Chief Global Strategist, UBS Investment Bank.
Baweja stated the oil market's response earlier this year may have given market participants a false sense of security. The shutdown of the Strait of Hormuz was a major event — it had not even happened during the Iran-Iraq war in the 1980s — but crude prices did not sustain the kind of surge many had feared, failing to stay at marks such as $120, $150 or $200 a barrel.
One important reason was China.
China was not buying oil earlier this year, which meant inventories did not decline despite the disruption. That dynamic has now changed, with China back in the market. Airlines and other firms that had deferred purchases while waiting for crude prices to slide are additionally likely to return as buyers.
At the same time, supply stays heavily constrained.
14 Million Barrels a Day at Risk
Typically, around 20.5 million barrels a day of crude and products transit the Strait of Hormuz, Baweja stated. His best estimate is that only around one-third, or roughly 6 million barrels a day, is at present making its way through, including volumes carried by the dark fleet.
That leaves roughly 14 million barrels a day missing from normal flows.
"That can put a lot of pressure on crude prices," Baweja stated, adding that the disruption is a risk market participants in both Indian and global markets need to be particularly conscious of.
The other change is that the market is beginning to recognise that the US administration may not be able to unilaterally resolve the disruption. While it may be easier for the White House to reverse course on tariffs or other policies when markets come under pressure, a war involves multiple parties with very different incentives, including Iran.
Markets May Be Underpricing the Shock
Baweja stated markets are complacent, pointing to the behaviour of equities as well as volatility.
The complacency is not limited to India. Equities in several large oil-importing economies are additionally trading relatively well, while volatility in equities and currencies is close to its lowest marks.
That is at odds with the risks posed by rising crude prices and geopolitical tensions, he stated.
Firm refining margins are additionally contributing to the gain.
Oil Products Could Feed Food Inflation
The implications extend beyond fuel prices. Elevated naphtha and fertiliser costs could eventually feed into food prices, with fertiliser prices translating into food inflation with a lag.
Baweja stated the outlook for winter sowing will as a result be important, particularly over the November-to-February period, alongside the risks associated with El Nino. Summer sowing has been "absolutely fine", he stated, but the next season will need to be watched closely.
He sees the system as increasingly loaded with inflationary pressures, even though he does not expect a significant wave of wage-fuelled or core inflation.
For developing economies such as India, the distinction between core and non-core inflation is less useful, Baweja stated, because food and energy make up such a large part of the overall consumption basket.
That means a climb in food and energy prices cannot simply be dismissed on the grounds that core inflation stays contained. Before long, elevated prices can additionally feed into inflation expectations, adding another layer of risk for the economy and markets, he stated.

SEBI chief Tuhin Kanta Pandey backs CAS, says market rules must adapt to current realities
Prime Focus arm Brahma AI raises $150 mn at $2-bn valuation from Multiples Private Equity, shares fall 4%

Puravankara shares rise 1.5% as company secures land parcel in Greater Noida with Rs 5,200-cr GDV…
About The Author
