Is your credit card giving you less than before? Here’s how to get more value from it
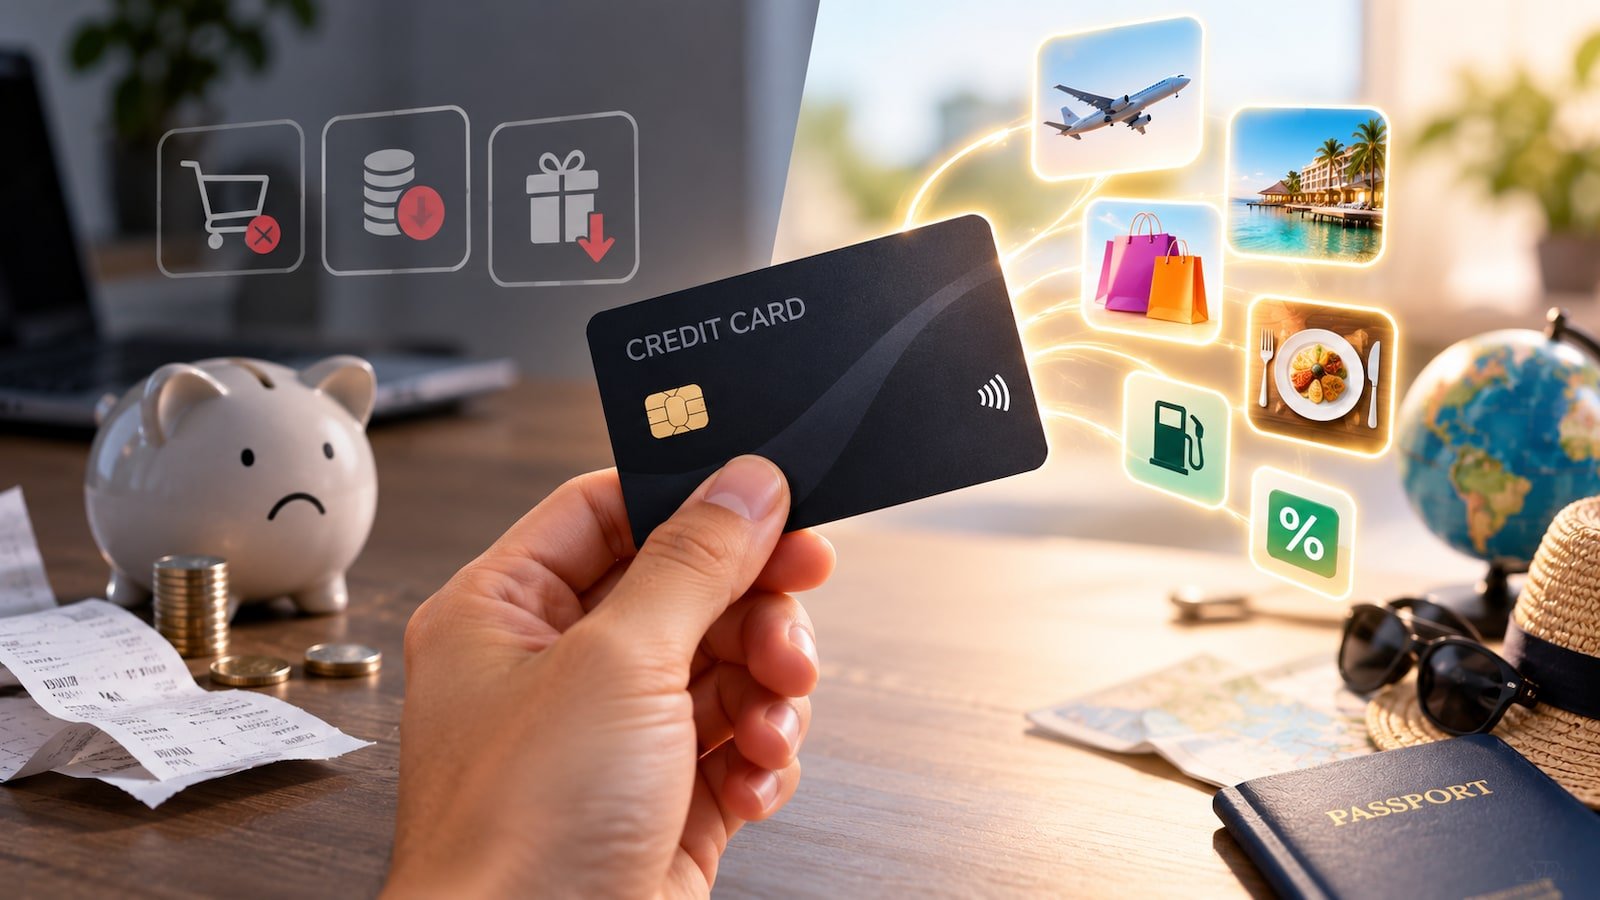
The latest market report highlights that You may have taken a credit card because it offered free airport lounge visits, good cashback or generous reward points. A year later, you could still be paying the same annual fee but getting much less in return.
This has become increasingly common. In 2026, several Indian card issuers have changed reward structures, reduced cashback, removed benefits or made perks available only after you spend a certain amount. Airport lounge access, in particular, is increasingly being linked to minimum quarterly or monthly spending.
That does not necessarily mean you need to change your card every time a benefit disappears. But it does mean you should occasionally check whether the card you are paying for still makes sense.
Start with the reason you got the card
Think around why you chose the card in the first place.
Was it mainly for cashback? Airline miles? Lounge access? Hotel benefits? Or simply because the annual fee was low?
Now check whether that benefit still exists and whether you can realistically use it.
If you took a card largely for lounge access but now need to spend ₹60,000 every quarter to qualify, for instance, that perk may no longer be valuable if your normal spending is much softer. HDFC Bank's Regalia Gold is one example where domestic lounge access now requires ₹60,000 of spending in the preceding calendar quarter.
Don't gain your spending simply to unlock a supposedly free benefit.
Look beyond the headline reward rate
A card may advertise 5 percent cashback or accelerated reward points, but that does not mean you earn that rate on everything you buy.
There may be monthly caps and categories that no longer earn rewards. Some cards exclude or limit rewards on payments such as utilities, insurance, government transactions, rent or education.
Cashback caps have additionally been tightened on some cards this year.
Instead of looking only at the advertised rate, check your last few statements. How many points or how much cashback did you actually earn from your normal spending?
That tells you far more around the value of the card.
Don't keep too many cards for old benefits
It is easy to end up with several credit cards because each one was useful at some point.
One gave you lounge access, another offered movie tickets and a third had good cashback on online shopping. Over time, those benefits may have changed while the cards remained in your wallet.
Review cards that charge an annual fee especially carefully. If you are paying Rs 2,000 or Rs 5,000 a year but barely using the benefits, keeping the card simply because you have had it for years may not make sense.
Before closing an old card, that stated, consider factors such as its credit limit, age and the possible impact on your credit utilisation and credit profile.
Use your rewards instead of endlessly saving them
Reward points can feel like money sitting safely in an account, but their value is not set.
An issuer can change how many points are needed for a flight, voucher or other redemption. Transfer partners can additionally change, and points may have expiry rules.
That is why there is little advantage in collecting points indefinitely without a plan for using them.
If you already have enough points for something useful, consider redeeming them rather than assuming they will be equally valuable several years from now.
You don't need to constantly chase the newest credit card.
Instead, spend a few minutes every six months checking your card's annual fee, rewards, cashback limits, lounge rules and other benefits.
The best credit card is not necessarily the one promising the most perks. It is the one that rewards the spending you already do.
If you have to change the way you spend simply to earn back the annual fee, the card may no longer be working for you.
CBI searches 12 locations in 3 cities over alleged builder-financial institution nexus
‘Why should I?’ IndusInd Bank CEO Rajiv Anand says name marked ‘unmapped’ in voter roll

PM Modi joins ‘Bhajan clubbing’ trend as youth jam to devotional beats
About The Author
