Dalal Street Week Ahead: US-Iran situation, crude oil prices among 10 key factors to watch
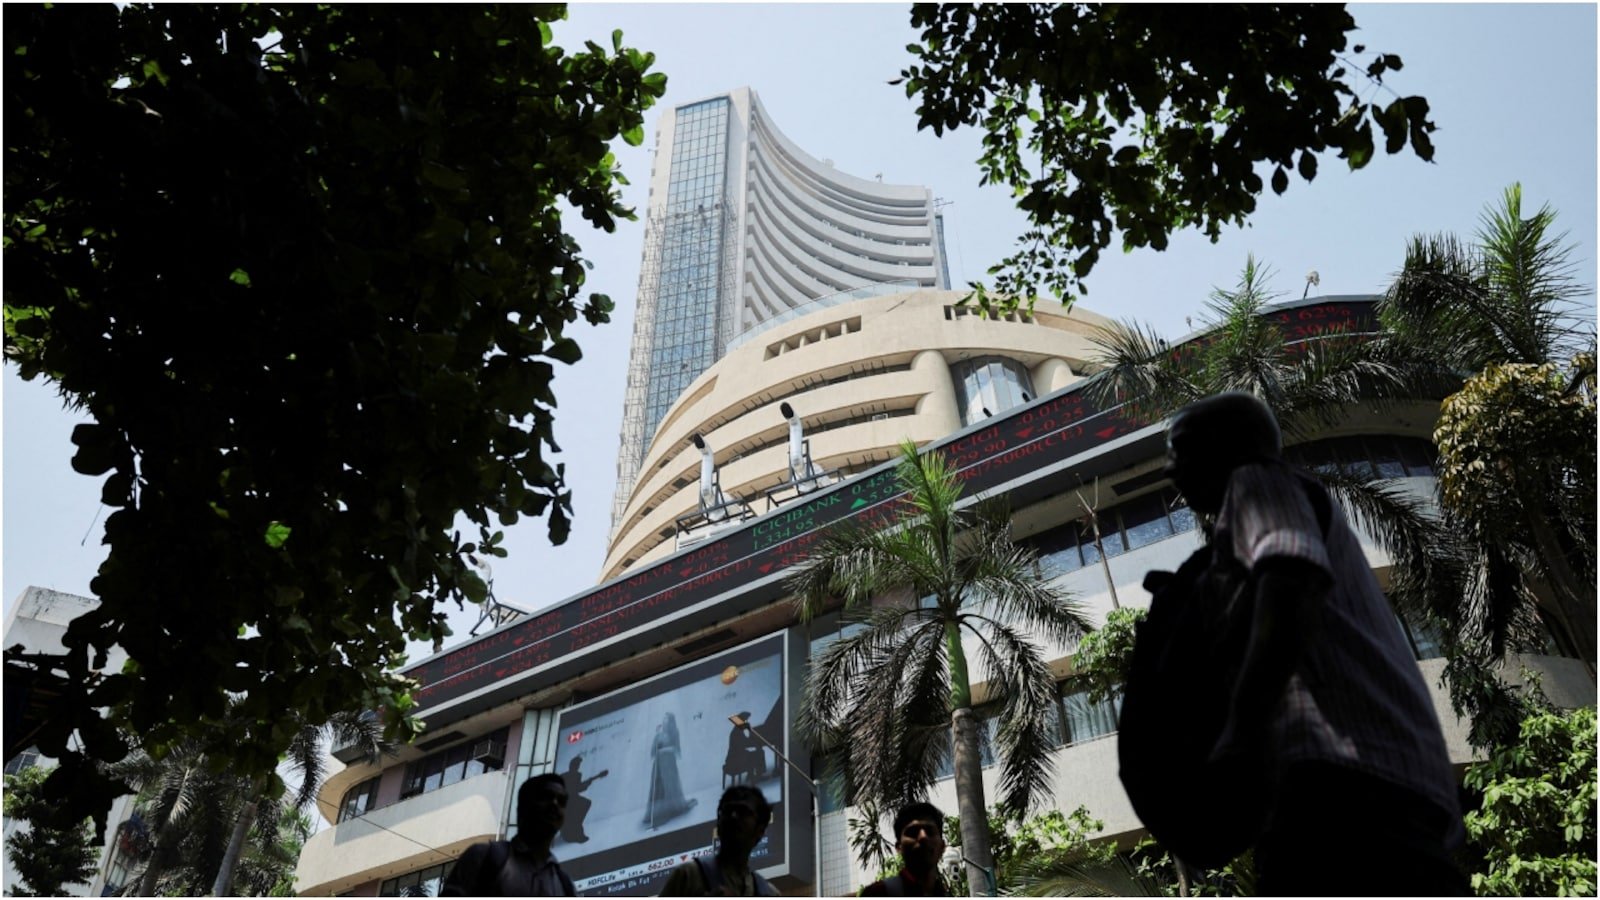
The latest market report highlights that Developments in the US-Iran situation, oil price marks and bond yields are anticipated to influence equity market sentiment in the holiday-shortened week.
The equity markets in India will stay closed on Friday for Mahatma Gandhi Jayanti, according to the NSE's 2026 trading holiday calendar.
The equity markets in India logged their longest weekly losing streak in six years last week as high crude prices drove up bond yields and inflationary concerns. Before the current week, the Nifty 50 had recorded seven or more consecutive weekly losses only four times in the last 25 years — in 2020, 2008 and twice in 2001. Its longest losing streak was nine weeks in 2001.
10 key factors to watch the current week
1) US-Iran situation: Iran on Sunday insisted that only diplomacy can solve its conflict with the United States and Israel after US President Donald Trump stated he rejected an Iranian proposal to reopen the Strait of Hormuz and end fighting, noted Reuters.
"Our conditions are clear, and any move toward reopening the Strait of Hormuz is contingent on these conditions being met," Iranian Foreign Minister Abbas Araqchi posted on social media. "Only a negotiated solution can get them out of this deadlock."
Any development in the US-Iran situation could have a bearing on oil price marks, India's import bill and the indian rupee, and in turn influence market sentiment.
"Globally, developments around US-Iran diplomacy and oil price marks will stay critical. Any progress on a framework for reopening the Strait of Hormuz could ease energy prices and provide some relief to India's import bill and the indian rupee, while renewed geopolitical tensions could keep volatility elevated," Ajit Mishra, SVP – Research, Religare Broking, stated.
2) Oil price marks: Crude prices have been a focal point for Indian markets since late February when the US and Israel rolled out joint strikes on Iran, triggering a war in West Asia.
"Brent crude near USD 105–106 a barrel stays too elevated to provide meaningful macroeconomic relief. Progress in the US-Iran negotiations could help reduce the geopolitical premium in crude prices, while renewed escalation or supply disruptions could intensify inflationary pressures," Hariselvan Radhakrishnan, Founder & CEO of HST Wealth, a Research Market observer firm, stated.
3) FII activity: The trend of FPI flows turning negative after positive inflows in July and August has continued. Total equity outflows through exchanges have touched Rs 25,682 crore this month through August 25.
At the same time, FPI investment through the primary market has continued, with total investment at Rs 8,551 crore up to August 25. This trend of selling through the exchanges and investing through the primary market has taken total FPI selling this year through exchanges to Rs 2,95,971 crore, while total investment through the primary market during the period stood at Rs 54,398 crore.
"Given the high US bond yields and better returns from India’s IPO market, this trend is likely to continue. Yet another significant trend in FPI investment is that even though they are sellers in large-caps, they have been sustained buyers in mid-and small-caps. FPIs additionally are chasing the market momentum," further noted Dr. V K Vijayakumar, Chief Investment Strategist at Geojit Investments.
4) Macroeconomic data: On the domestic front, industrial production data for August and the HSBC manufacturing PMI reading will be released during the week.
According to Siddhartha Khemka, Head of Research, Wealth Management, Motilal Oswal Financial Services, markets will track India's August industrial production and the federal fiscal deficit for cues on domestic momentum and the consolidation path.
5) Bond yields: Equity market participants will closely watch bond yields as elevated yields keep tighten global financial conditions and can reduce the relative attractiveness of emerging-market assets.
"The US 10-year Treasury yield, at present near 5.2 percent, will stay an important constraint on global risk appetite," Radhakrishnan further noted.
"Global bond yields will additionally stay important following the The US central bank's September policy decision. Further increases in yields and the dollar could weigh on emerging-market capital flows, while a moderation in yields could provide some relief," Ponmudi R, CEO – Enrich Money, an online trading and wealth tech firm, further noted.
6) Indian rupee movement: The indian rupee appreciated 24 paise to close at 95.75 against the US dollar on Friday. At the interbank foreign exchange market, the indian rupee opened at 95.92 against the American currency. Through the session, the local unit eased to an intra-day low of 95.94, but recovered lost ground to close at 95.75, a 24 paise climb from its previous close.
"The indian rupee will stay an important factor to watch, with persistent oil-related demand for dollars and continued FII outflows potentially keeping the currency under pressure, although RBI intervention has helped contain excessive volatility," Ponmudi R further noted.
7) US data: A series of economic data releases from the US will additionally be important for global risk sentiment. Globally, US consumer confidence and JOLTS job openings, and the eurozone September inflation cluster will shape expectations around the global rate cycle.
8) IPO Market: The primary market will keep stay busy over the upcoming week, with 20 IPOs opening for subscription and looking to mobilize a combined Rs 1,292 crore.
The week will be led by four mainboard IPOs — SRIT India, Vishal Nirmiti, Nityas Gems & Jewellery and Shah Investor’s Home — which together plan to mobilize Rs 595 crore.
The rest of the action will come from the SME segment, where 16 firms are anticipated to mobilize around Rs 697 crore.
9) Technical Outlook: Nifty 50’s broader technical structure stays weak, with the index continuing to trade below key moving averages and the broader trend remaining under pressure.
On the upside, 23,200 stays the immediate resistance zone. A sustained move above 23,300 could provide some stability and backing a recovery towards the 23,500 region. That stated, unless the index decisively reclaims this band, recovery attempts could keep face selling pressure.
On the downside, 23,000 stays the immediate and crucial backing level. A decisive break below 23,000 could intensify selling pressure and expose the index to the 22,800 region.
Momentum stays weak, with the RSI having eased into bearish territory during the recent sell-off and the MACD continuing to stay negative.
Overall, the near-term technical outlook stays wary to bearish, stated Ponmudi R, CEO – Enrich Money, a SEBI-registered online trading and wealth tech firm.
Daily Voice: Are private-sector banks trading at cheap valuations? Ladderup’s Raghvendra Nath sees…

Biocon shares rise 3% after stake sale in Rs 635-cr block deal; company eyes $1 billion biosimilars…
Adani Enterprises stock jumps 4% as BlackRock, Temasek, Premji Invest sign up for Adani Airports stake
About The Author
